

18 September 2026
Weekly Market View
A Fed credibility – induced bounce
The Fed’s unanimous decision to hike rates this week for the first time since 2023 and pencil in another hike by December confirms our expectations of a central bank willing to establish its independence against political pressure.
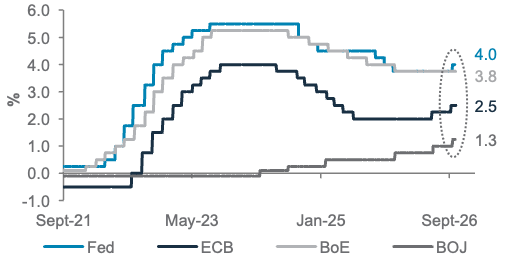
The BoJ also hiked rates this week. It is the first time on record all three major central banks – Fed, ECB and BoJ – have hiked in the same month, as they respond to a resurgence in energy-driven inflation amid tight job markets.
We expect the Fed to hike once more by year-end to 4.25% and follow up with another hike in H1 2027 to 4.5%. With the revised estimates, we revise up our US government bond yield forecasts.
Nevertheless, with Fed policy uncertainty easing, we see an opportunity to use the equity market dip to add exposure amid solid corporate earnings.
What is the outlook for US government bond yields following the Fed meeting?
Will the step-up in the Fed’s risk-free rate trigger a repricing of equities?
What is the impact of BoJ and BoE policy meetings on their respective currencies?
Charts of the week: Fed joins the fray
The Fed hiked for the first time since 2023, joining its peers, and moderately upgraded its policy rate estimate for this year
Fed, ECB, BoJ and BoE policy rates
Fed’s updated economic projections
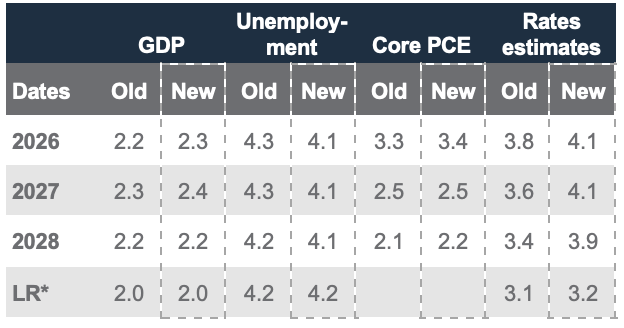
Source: Federal Reserve, Bloomberg, Standard Chartered
Editorial
A Fed credibility-induced bounce
Strategy summary: The Fed’s unanimous decision to hike rates this week for the first time since 2023, and pencil in another hike by December, confirms our expectations – flagged in the last two weeklies – of a central bank willing to establish its independence against political pressure. The Fed’s moderately hawkish pivot is helping restore its inflation-fighting credentials. The BoJ also hiked rates this week. It is the first time on record all three major central banks – Fed, ECB and BoJ – have hiked in the same month, as they respond primarily to a resurgence in energy-driven inflation amid tight job markets.
We expect the Fed to hike once more by year-end to 4.0-4.25% and follow up with another hike in H1 2027 to 4.25-4.5%. With the revised estimates, we revise up our US government bond yield forecasts. Nevertheless, with Fed policy uncertainty easing, we see an opportunity to use the equity market dip to add exposure amid solid corporate earnings.
Fed moves to restore credibility: The Fed’s policy pivot this week followed Chair Warsh’s hawkish Jackson Hole speech and recent economic data prints, namely: a pick-up in job creation and inflation over the summer and a sharp rebound in oil prices due to the re-escalation of the Middle East conflict. Given the unanimous Fed decision to hike rates this week, we expect two more hikes by June 2027 on the back of robust growth amid strong AI investments and a tight labour market, keeping inflation elevated. We expect this pivot to help the Fed rebuild credibility as an inflation fighter.
Policy outlook less aggressive than market pricing: The updated Fed policy rate estimates are lower compared with money market pricing of three more rate hikes by June 2027 since we expect disinflation to take hold by Q2 2027 as the impact of oil prices and tariffs fade. We believe policy rates can return to the 4.0–4.25% range by end-2027, with the possibility of cuts in H2 2027 as inflation pressures ease.
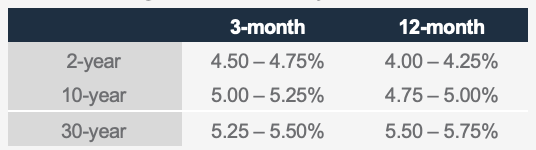
Upgrading near-term US rates and USD estimates: Based on these revised estimates, we also upgrade our 3-month target for the US 10-year government bond yield to 5.0-5.25%. We also revise up our 12-month target for the US 10-year bond yield to 4.75-5.0% (see page 4).
Buying the equity dip as focus turns to fundamentals: Fed hikes typically do not hurt equities over the medium-term when accompanied by strong earnings growth. We estimate a 25bps rise in Fed rates (the discount rate) would impact the S&P500 index and global equities by 3-4%. However, we expect the headwind from higher rates to be offset by strong earnings growth, driving positive performance for global equities. Furthermore, a hawkish Fed is largely priced in and we expect the Fed to deliver fewer rate hikes than currently priced by markets. Meanwhile, we believe concerns over AI industry leaders slowing the pace of development are overdone. Hence, we maintain our preference for a diversified group of large cap technology and semiconductor industry leaders (see page 5-6).
BoJ hikes; modestly bullish JPY: The BoJ hiked rates by 25bps to a three-decade high of 1.25%, as expected, but the 7-2 split vote led to renewed JPY weakness on concerns it may slow the pace of further hikes. We remain constructive on JPY amid narrowing rate differential vs peers as the BoJ potentially hikes rates by 25bps once per quarter until Q2 2027 to curb rising domestic wage-driven inflation pressure . Any sign of BoJ slowing the pace of hikes could lead to renewed JPY weakness, fuelling inflationary pressures (see page 7).
BoE holds; rangebound GBP: The BoE held rates this week, bucking the hiking trend among peers, as weakening UK job and housing markets offset rebound in energy-driven inflation. We expect BoE to deliver fewer rate hikes than the 100bps of increase currently priced by markets as the job market slows further. This is likely to keep GBP rangebound (see page 7).
— Rajat Bhattacharya
The weekly macro balance sheet
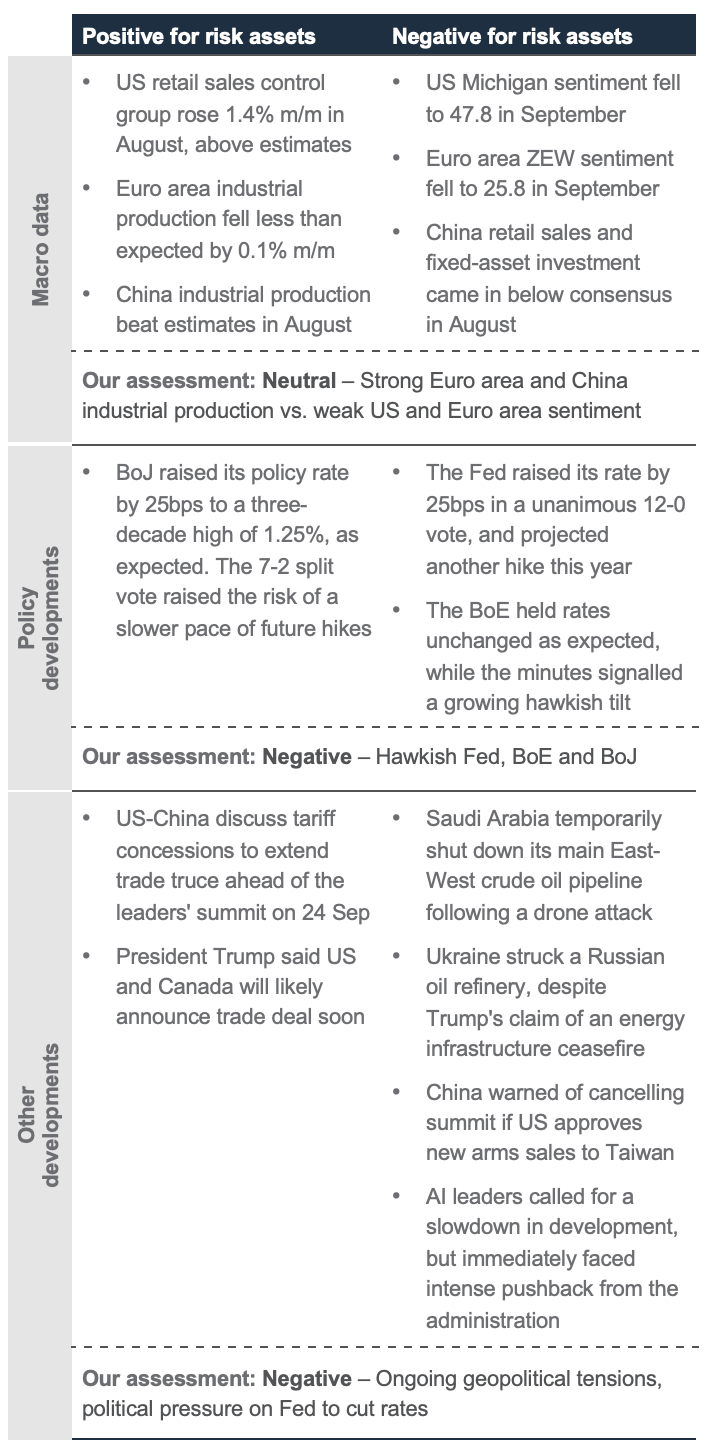
Our weekly net assessment: On balance, we see the past week’s data and policy as negative for risk assets in the near-term
(+) factors: Strong US retail sales; resilient China industrial output
(-) factors: Weak US and Euro area sentiment; hawkish central banks
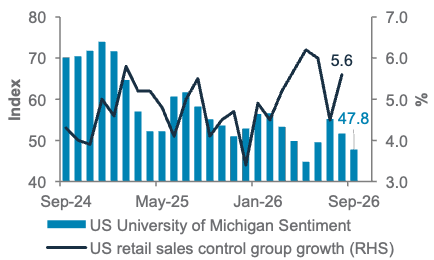
US retail sales growth accelerated in August; however, the Michigan consumer sentiment index declined more than expected in September
US Michigan consumer sentiment and retail sales control group (core retail sales)
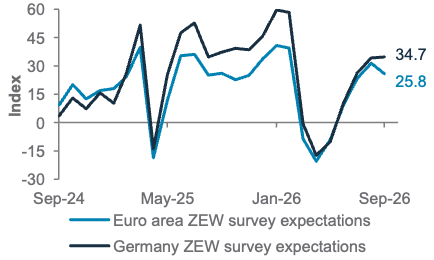
The ZEW survey indicated that Euro area optimism is fading outside of Germany
Euro area and Germany ZEW survey expectations
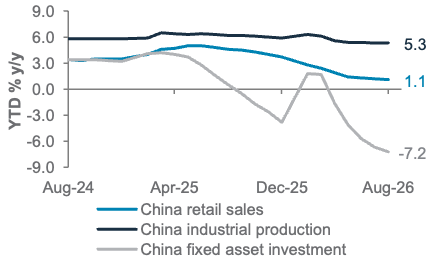
China’s retail sales growth was subdued and investment slumped in August
China retail sales, industrial production and fixed asset investment growth
Top client questions
Where do you see US government bond yields following the Fed’s 16 September decision to hike interest rates?
Our view: The US 10-year government bond yield is likely to retest the 5.00-5.25% range in the near term. We favour 3-7-year maturity bonds in the US, preferring credit over government bonds. We are looking for an opportunity to extend duration approaching Q2 2027.
Rationale: Over the next few months, we expect 2- and 30-year US government bond yields to remain rangebound, but the 10-year yield is expected to rebound up to the 5.00-5.25% range. The reasons for this include: 1) oil prices staying elevated and potentially rise further due to the fluid geopolitical situation in the Middle East, with Saudi Arabia’s East-West oil pipeline shut, the Houthis now firmly in control of the Strait of Bab-al-Mandab, the Strait of Hormuz still closed and China returning as a buyer of crude oil in the market; 2) despite notable AI leaders expressing the need to slow AI development, AI capex plans are showing no signs of slowing down, which continues to drive above-trend growth in the economy. This, in turn, also means AI-related heavy bond issuance is expected to continue. These issuers typically issue long-dated tenors, and this competition for capital will also exert upward pressure on the US 10-year yields.
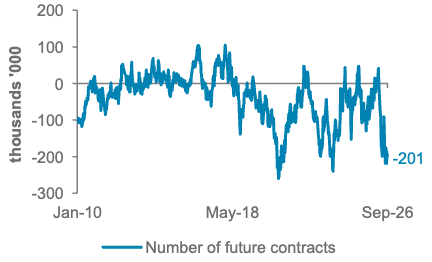
We note that the US 10-year bond yield has room to move lower, driven by short-covering activities in the very near term as net-short positions had moved to extreme levels before this week’s Fed meeting. However, we think such downshifts would be short-lived and the central tendency for the 10-year yield would be to move back up to the 5.00-5.25% range.
Meanwhile, we see US 30-year yields continuing to reflect the dire fiscal outlook for the US government. We expect US 2-year yields to continue trading in a range that reflects expectations of further federal funds rate hikes. For the record, we only expect two more rate hikes from the Fed into the middle of 2027, while money markets are pricing in three more for the same period.
Going into H2 2027, we expect oil prices to moderate (either through a resolution of the Middle East conflict or a re-routing of oil supply chains) and the inflationary effects from tariffs to fade. Inflation by then is likely be close to – if not at – the Fed’s target of 2%. At this point, we see room for the Fed to contemplate rate cuts. US 2-year yields (the tenor that is most sensitive to Fed policy changes) will likely start to price this in. With oil prices and inflation cooling, 10-year yields would also have room to come down.
US 30-year yields, on the other hand, are expected to remain elevated as the US fiscal deficit remains substantial next year and could become much worse than its already dire state today. As a result, the ‘term premium’ may keep the ultra-long end elevated. Short of some unorthodox policy to artificially cap them lower, 30-year yields could continue to drift higher into H2 2027.
We continue to favour the 3-7-year segment of the yield curve and prefer credit over government bonds. We see an opportunity for us to extend duration closer to Q2 2027.Looking more broadly at semiconductors, earnings growth continues to be supported by ongoing AI infrastructure spend and broadening AI adoption, with US AI adoption expected to reach 25.1% in Q4. The results season reaffirmed strong demand trends for semiconductors, while guidance points to persistent tightness in supply. The industry trades at around 16x forward earnings, below its five-year average of around 20x, despite the strong growth outlook. We view the pullback in valuations as an attractive entry point and initiate an Opportunistic idea on global semiconductors.
— Jonathan Liang, CFA, CIO for Fixed Income and FX
We have updated our three- and 12-month outlook for US government bond yields
Our latest US government bond yield forecast
Short-covering trades could move bond yields lower temporarily as net-short positions in US government bond futures have reached extreme levels this week
Bloomberg Commodity Futures Trading Commission Chicago Board of Trade US government bond net non-commercial futures positions
Top client questions (cont’d)
Will the step-up in the Fed’s risk-free rate trigger a re-pricing of equities?
Our view: We expect strong corporate earnings growth to offset the headwind of higher rates, driving positive performance for global equities. We remain Overweight global equities.
Rationale: The Fed’s latest 25bps rate hike had been anticipated by the bond market, partly reflected in the bond yield rise we have seen so far in 2026. Using the US 10-year government bond yield as a proxy for the risk-free rate, the yield has risen by 80-85bps this year. We estimate that each 25bps rise in the discount rate presents a valuation drag on global equities. On this basis, the rise in yields represents a potential 10-14% headwind for equities this year.
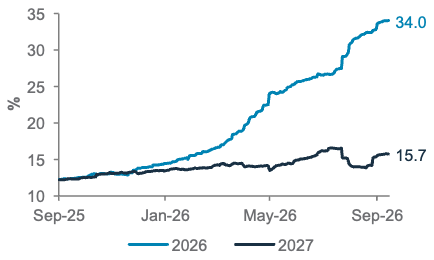
However, the Fed’s hike reflects a solid expansion of US economic activity, resilient domestic spending and robust capital investment. This is consistent with the positive earnings revisions we have seen this year, with 2026 earnings growth projections now at 34% (and 16% for 2027). Global equities are up 14% year-to-date (YTD), but even with a 14% valuation headwind from higher yields, we believe they can rise further, givenstrong earnings growth in 2026 and 2027.
— Fook Hien Yap, Senior Investment Strategist
Global equities’ earnings growth estimates have been revised higher this year, offsetting the headwind from higher rates
Evolution of consensus 2026 and 2027 earnings growth for the MSCI AC World Index (MSCI ACWI)
What is the outlook for the US 10-year government bond yield? What is your tactical view on the DXY?
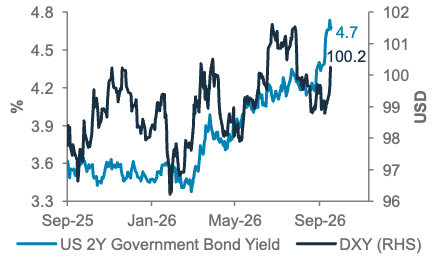
Our view: We raise our three-month US 10-year government bond yield forecast to the 5.00-5.25% range. Meanwhile, we see a near-term upward bias in the DXY after its recent downtrend, supported by recent Fed tightening and higher short-term US bond yields.
Rationale: The Fed’s decision to raise the target range for the federal funds rate by 25bps to 3.75-4.00% validates the upside policy risks we flagged recently, following Fed Chair Warsh’s Jackson Hole speech and a run of firmer US economic data. We expect growth to remain robust, the labour market to remain tight and inflation to stay elevated, supporting one more hike before year-end 2026 and potentially another in H1 2027 – fewer than the three additional hikes currently priced in by money markets. For the US 10-year government bond yield, further policy tightening and lingering US fiscal concerns should keep yields elevated, but the Fed’s visible response to inflation should limit additional upward pressure, leaving the 10-year yield holding around the 5.00-5.25% range.
Crucially, Warsh provided no forward guidance on further rate hikes. Markets had already priced in substantial additional rate hikes ahead of the Fed meeting, reducing the scope for further USD upside purely from rate repricing. Meanwhile, we expect further policy tightening from the ECB and the BoJ, while the RBA also remains biased towards further tightening. This should gradually narrow the US rate advantage and limit the extent of a DXY rebound.
— Vincent Tan, Senior Investment Strategist
— Anthony Naab, CFA, Investment Strategist
The US Dollar Index (DXY) remains closely linked to US front-end rate expectations
The DXY tracks US 2-year government bond yields
Top client questions (cont’d)
How should investors position in technology as AI lab CEOs call for a slowdown in frontier AI model development?
Our view: We believe concerns over “pacing the frontier” are overdone. We maintain our preference to remain invested in and diversified across Big Tech and semiconductor leaders.
Rationale: We believe it is prudent for investors to avoid overreacting to the recent calls for a slowdown in frontier AI model development, as they focus on responsible AI development, rather than halting AI model development or reducing spending. The global AI leadership race, reinforced by the US and China’s strategic ambitions, also makes a coordinated slowdown unlikely.
While the near-term narrative may shift from AI training beneficiaries towards inference plays, hyperscalers continue to signal strong AI infrastructure commitments and improving monetisation, supporting our AI capex outlook. Rising AI adoption and agentic use cases should sustain inference demand, even if training activity moderates, benefiting custom AI chips, NAND flash memory and hyperscalers.
We believe the decline in valuations this year more than compensates for any downside risk to AI capex. Our Opportunistic idea on Global Semiconductors further reflects our conviction, with attractive valuations supporting selective additions during volatility.
— Ryan Goh, Investment Strategist
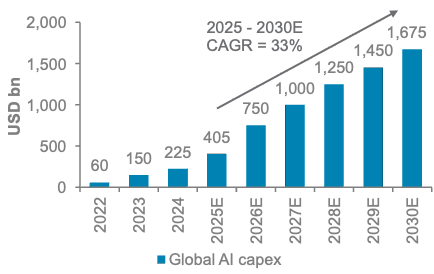
Our AI capex estimates are 15-20% below consensus expectations to account for execution risks
Global AI capex is expected to register a CAGR of 33% over 2025-30
With ASEAN and UK equities outperforming AI-focused markets in H2 2026, is it worth adding to these markets?
Our view: ASEAN and UK equities offer portfolio diversification, but we are Underweight both markets in favour of US and Asia ex-Japan (AxJ) equities, given their stronger earnings potential.
Rationale: The ASEAN and UK markets have outperformed the MSCI ACWI over the past three months, but both have underperformed on a YTD basis. Financials is the largest sector in the ASEAN (53%) and the UK (28%) and provides steady earnings. However, both markets have minimal exposure to the technology sector (just 3% and 1%, respectively), ultimately dragging down growth. Hence, while defensive markets offer value by increasing diversification and reducing volatility in a portfolio, we maintain our Underweight allocation for ASEAN and the UK, as we see much stronger earnings potential elsewhere in the US and AxJ markets.
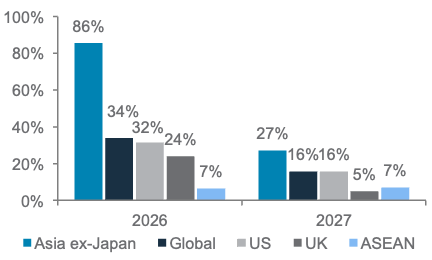
We remain Overweight US and AxJ, supported by robust earnings growth, as AI still has the potential to become a major economic growth driver. Our 12-month S&P500 Index forecast of 8,400 implies low-teens upside, supported by a strong earnings backdrop of 25-30% earnings-per-share growth for 2026 and 15-20% for 2027. AxJ also boasts the strongest earnings growth among major markets, fuelled by the AI semiconductor super-cycle.
— Cindy Lam, CFA, Senior Investment Strategist
Our Overweight views on AxJ and US equities are supported by robust earnings growth
Consensus 2026 and 2027 earnings growth estimates for MSCI equity indices
Top client questions (cont’d)
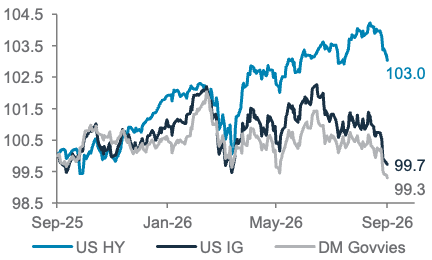
Why is it still appropriate to have a positive stance on US high-yield (HY) bonds?
Our view: We remain opportunistically bullish on US HY bonds. Lower sensitivity to interest rate volatility, a below-trend default rate and a maturity wall pushed out to 2028-29 drive this view.
Rationale: Recent interest rate volatility has highlighted a key structural advantage of US HY bonds: their higher coupon rates and shorter tenors relative to Developed Market (DM) government bonds and US investment-grade (IG) corporate bonds translate into a much lower sensitivity to interest rates, cushioning bond prices during yield backup episodes, where bond yields rise sharply.
YTD, US HY has delivered 1.8% in total returns, outperforming DM government bonds and US IG corporate bonds by over 3% each on a relative basis. This outperformance was particularly evident during the recentback-up in bond yields, as inflation concerns re-emerged after renewed Middle East tensions – an environment where HY’s lower rate sensitivity provided a relative cushion even as broader fixed income markets came under pressure in absolute terms. On the fundamentals side, US HY corporate credit quality remains resilient. Default rates continue to track below long-run trend levels, and the maturity wall has been pushed out to 2028-29, reducing near-term refinancing risk. Against a non-recessionary macro backdrop, we expect these credit fundamentals to hold, supporting the case for continued opportunistic exposure to the asset class.
— Ray Heung, Senior Investment Strategist
We expect US HY bonds to continue delivering strong performance in the near term
Total returns: US HY corporate, US IG corporate and DM government bond indices
Do the latest BoJ and BoE meetings alter your view on the central banks’ rate paths and their corresponding currencies?
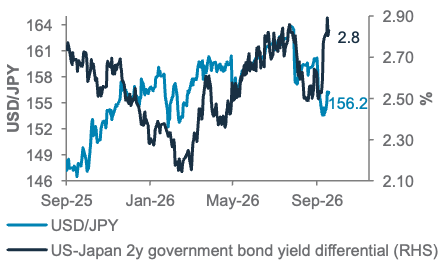
Our view: We remain constructive on the JPY and expect two BoJ rate hikes this year and potentially one hike per quarter in H1 2027 as policy normalisation continues. Meanwhile, the BoE held rates at 3.75%. We expect GBP/USD to stay rangebound within 1.32-1.36 over the next 1-3 months, with downside risk towards the lower end of our medium-term 1.30-1.36 range.
Rationale: Persistent inflation, higher energy prices and earlier JPY weakness support further BoJ policy normalisation. Continued hiking should progressively narrow the US-Japan rate gap, reduce the attractiveness of JPY-funded carry trades and support the JPY over the medium term towards the 153-155 range. However, with a September hike largely priced in, future tightening’s pace will be more important for the JPY. Meanwhile, the BoE was split 6-3 in its decision to hold rates at 3.75%, with three members preferring a 25bps hike, signalling elevated inflation risks. However, a weaker labour market is likely to limit the pace of BoE tightening. The US-UK rate divergence is expected to favour the USD over the next 1-3 months. Further BoE tightening (if inflation remains elevated) could narrow the rate gap and provide support to the GBP later in the cycle.
— Vincent Tan, Senior Investment Strategist
USD/JPY vs. US-Japan 2-year government bond yield differential
Market performance summary*
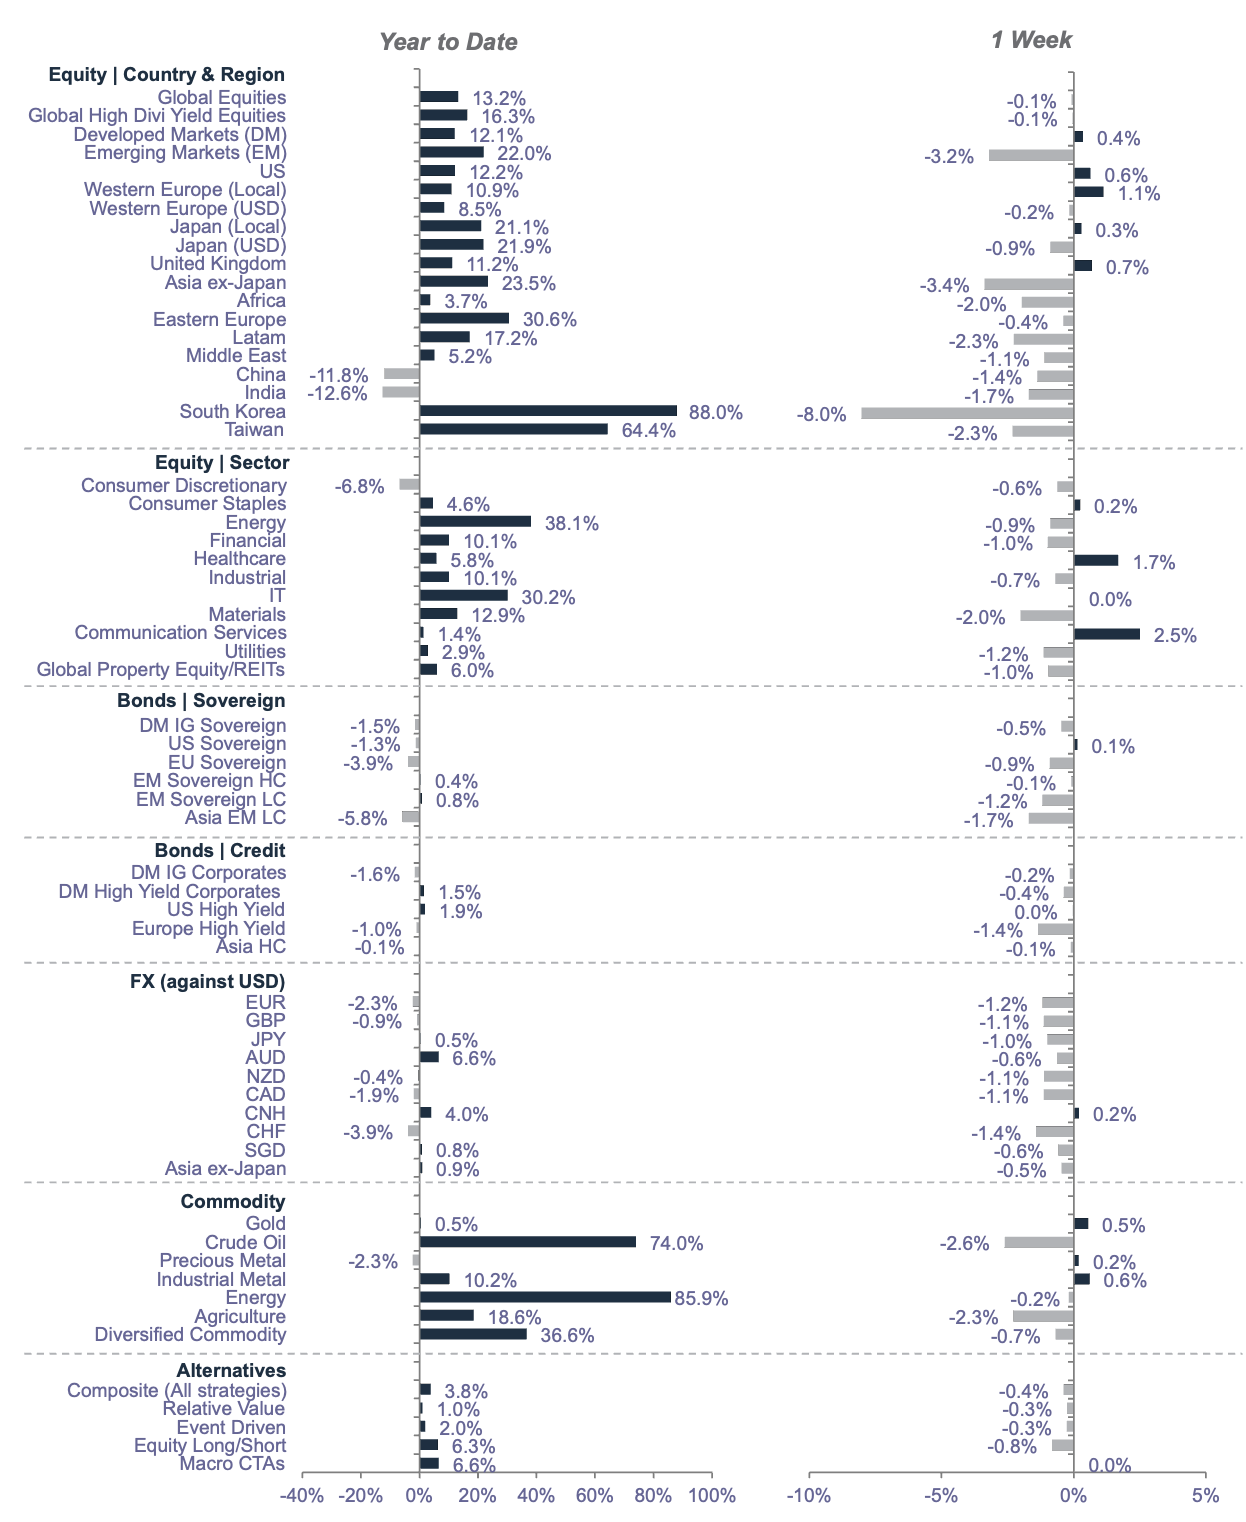
*Performance in USD terms unless otherwise stated, 2026 YTD performance from 31 December 2025 to 17 September 2026; 1-week period: 10 September 2026 to 17 September 2026
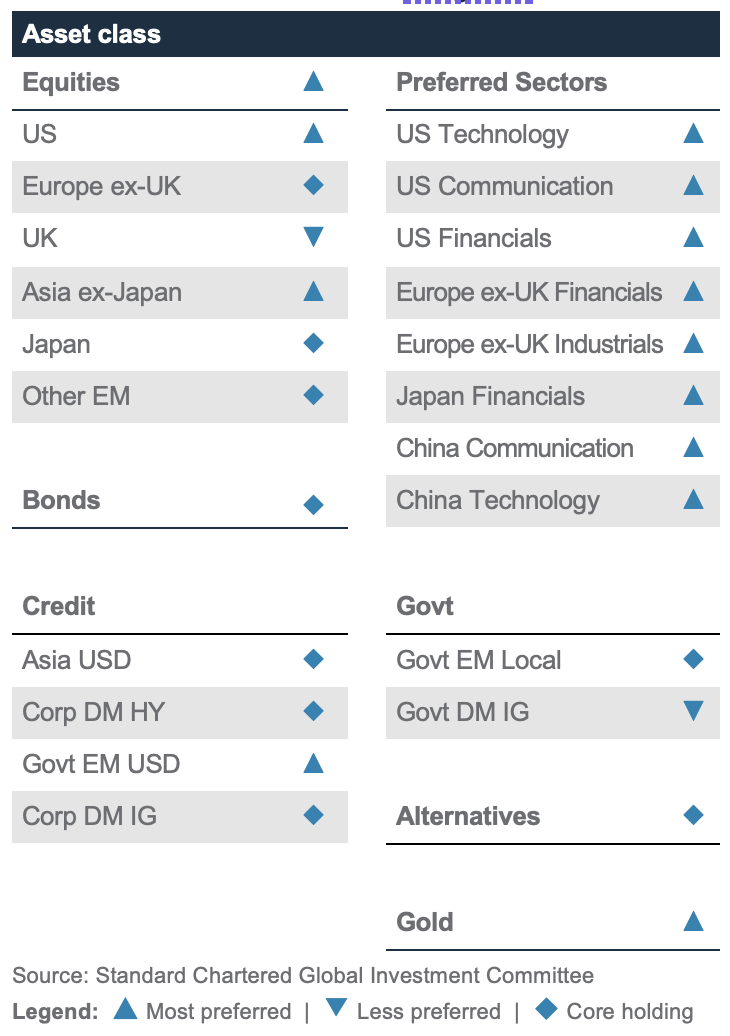
Our 12-month asset class views at a glance
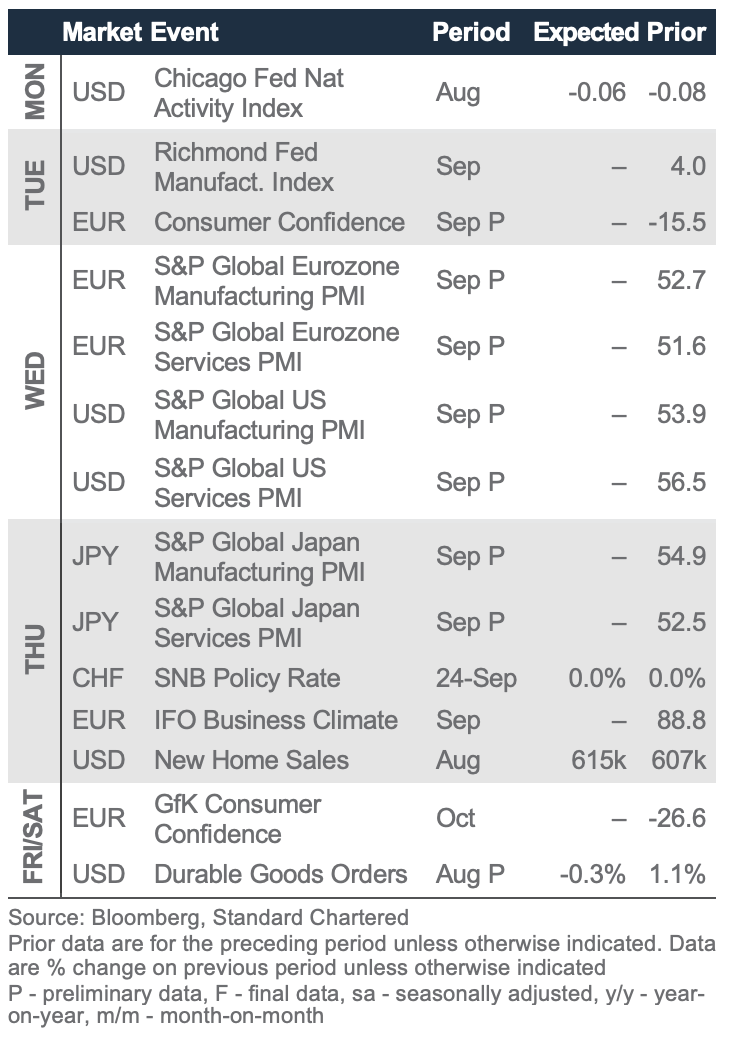
Economic and market calendar
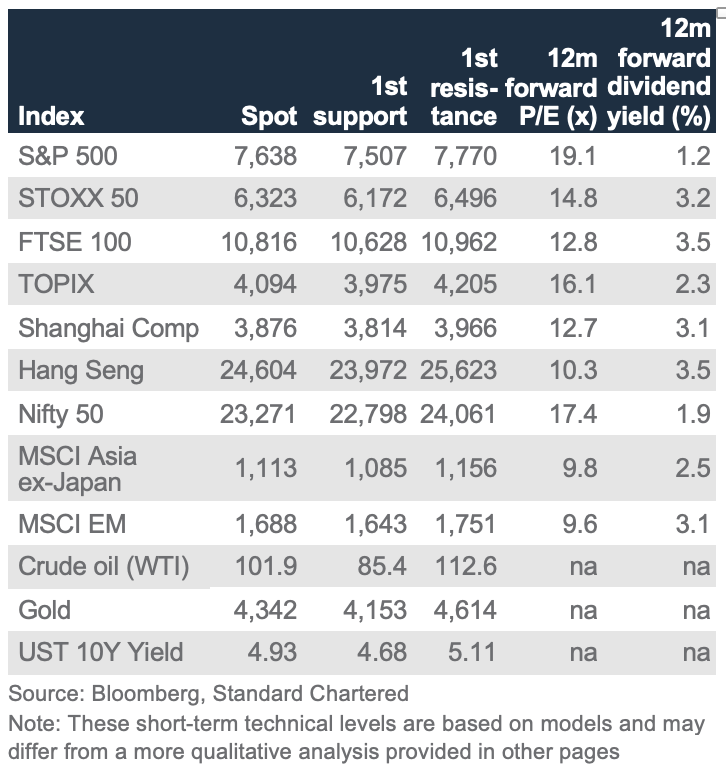
The S&P500 has next interim resistance at 7,770
Technical indicators for key markets as of 17 Sep close
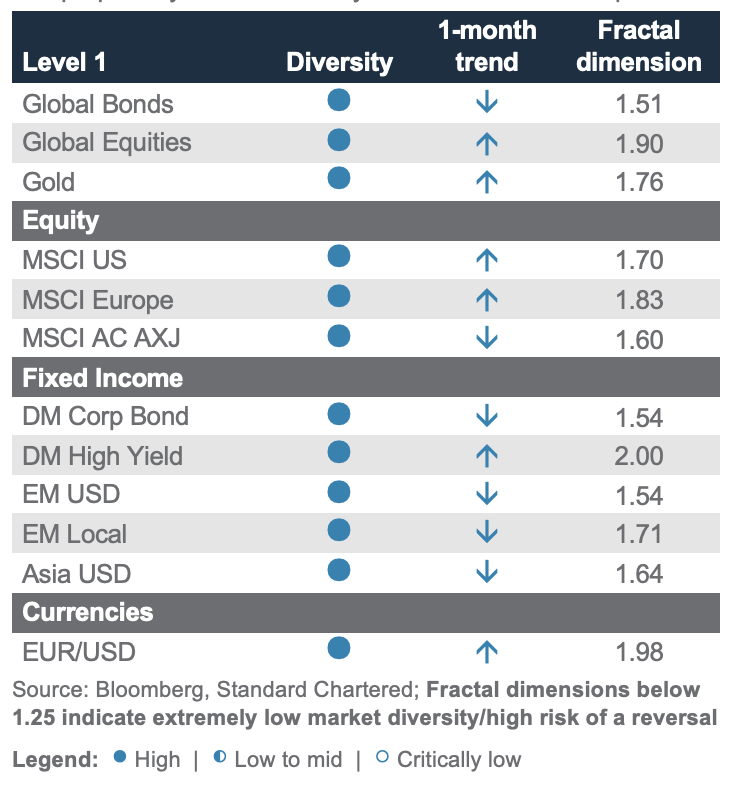
Investor diversity has normalised across asset classes
Our proprietary market diversity indicators as of 17 Sep close
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: This document is being distributed in India by Standard Chartered in its capacity as a distributor of mutual funds and referrer of any other third party financial products. Standard Chartered does not offer any ‘Investment Advice’ as defined in the Securities and Exchange Board of India (Investment Advisers) Regulations, 2013 or otherwise. Services/products related securities business offered by Standard Charted are not intended for any person, who is a resident of any jurisdiction, the laws of which imposes prohibition on soliciting the securities business in that jurisdiction without going through the registration requirements and/or prohibit the use of any information contained in this document. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: In Jersey, Standard Chartered Global Private Bank is the Registered Business Name of the Jersey Branch of Standard Chartered Bank. The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom and all business transacted with Standard Chartered Bank, Jersey Branch and other SC Group Entity outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.