

20 November 2026
Weekly Market View
Staying diversified,
adding US mega caps
AI-related concerns continue to weigh on equities, especially with new US restrictions on third-country access to advanced American semiconductor chips. Renewed volatility across the AI ecosystem drove the S&P500 volatility index (VIX) back above 25.
However, two major event risks this week turned out to be less concerning – Nvidia’s Q3 revenue and earnings exceeded expectations, while Anthropic’s record initial public offering was priced above its indicative range.
Our quant models are not signalling a strong buy signal yet. However, with VIX spiking above 25 and investor positioning and sentiment indicators suggesting limited downside, we see value emerging in the US mega caps segment following its recent underperformance.
We add an opportunistic idea on US mega cap equities, which we see benefitting from scale, financial strength and potential industry consolidation.
How will US chip restrictions impact the technology sector?
What are the implications of the Fed’s latest meeting minutes on bonds?
Do you see opportunities in gold after the latest selloff?
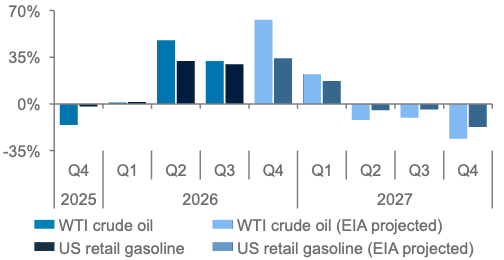
Charts of the week: Oil’s disinflation effect
Falling oil and fuel prices likely to support disinflation in 2027; bonds are starting to offer greater diversification benefits
Projected* y/y change in crude oil and gasoline prices by quarter
21- and 126-day rolling correlation of global equities and bonds
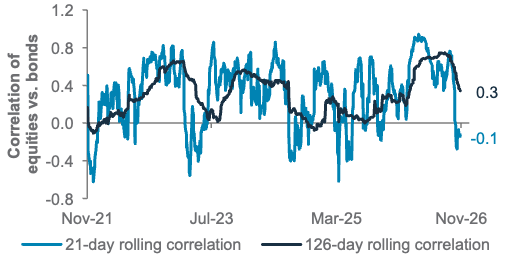
Source: US Energy Information Administration, Bloomberg, Standard Chartered; *EIA projections
Editorial
Staying diversified, adding US mega caps
Strategy summary. AI-related concerns continue to weigh on equities, especially with new US restrictions on third-country access to advanced American semiconductor chips. Renewed volatility across the AI ecosystem drove the S&P500 volatility index (VIX) back above 25. However, two major event risks this week turned out to be less concerning – Nvidia’s Q3 revenue and earnings exceeded expectations, while Anthropic’s record initial public offering was priced above its indicative range.
Our quant models are not signalling strong buy signal yet. However, with VIX spiking above 25 and investor positioning and sentiment indicators suggesting limited downside, we see value emerging in the US mega caps segment following its recent underperformance. We add an opportunistic idea on the segment, which we see benefitting from scale, financial strength and potential industry consolidation.
Opportunistically adding US megacaps. Asian equities led declines this week, led by Taiwan, China and Korea, after new US export controls targeted access to advanced AI computing through overseas data centres. Licensing requirements focus on capacity supplied to restricted customers, with additional controls affecting regional hubs. These measures increase compliance burdens and financing uncertainty, potentially weighing on AI capital expenditure. We expect the market’s AI capex estimates for 2027 to be cut towards our own more-conservative projections. Established cloud operators (hyperscalers) may be better equipped to manage customer checks than smaller providers. We initiate an opportunistic idea on US mega caps as we see a catch-up opportunity, given their established franchises, strong cash generation and relatively resilient earnings prospects (see page 7 for details).
Diversifying beyond the AI trade. Although positive cross asset and sector correlations returned this week, sector rotations earlier this month reinforces the importance of maintaining exposure to different drivers of equity returns. Our preferred US sectors remain technology, healthcare, financials and materials, combining technology participation with opportunities beyond AI. Beyond the US, we like Euro area and Japanese banks, which are benefitting from elevated interest rates, actively managed global dividend strategies for income
.
opportunities, and Indian equities due to their low correlation with the AI trade.
Allure of high dividend equities. While global dividend yields remain historically low, attractive pockets persist. The Swiss equity market yields almost 4%, versus 1.6% for global equities. Euro area (3.6%), Australia (3.5%) and Singapore (3.4%) are other leading dividend paying markets. Taiwan offers almost a 2% yield, combining income with structural growth opportunities. We favour active management over simply chasing yield, avoiding value traps. Dividend equities can complement bonds within a diversified portfolio, balancing income opportunities with broader exposure across markets.
Increasing diversification offered by bonds. The one-month correlation between global stocks and bonds has turned negative after more than a year. This means bonds are offering greater diversification benefits amid the equity drawdown. Minutes from the Fed’s October meeting suggest policymakers are likely to hike rates further. However, we remain dovish vs. markets on the Fed’s 12-month rates outlook (we see Fed target rate at 4.25% by end-2027 vs. market pricing above 4.5%) as lower oil prices and fading tariff effects lead to noticeable disinflation by H2 2027. Thus, we see particular value in the 3-7-year maturity bucket, with a preference for BB-to-BBB segment corporate bonds, which have resilient balance sheets and offer attractive yield pick-up. We see the US 10-year government bond offering value if the yield rises above 5.25%.
Dollar appears overbought; potential for gold upside: The USD index (DXY) has jumped over 2% in the past two weeks after stronger-than-expected US jobs and inflation reports for October revived Fed rate hike bets. Nevertheless, crude oil prices have slumped almost 20% this month as the Republican party’s heavy losses in the US mid-term elections raised the prospects of de-escalation in the Middle East conflict. Forward markets are pricing US crude oil below USD 75/bbl by Q3 next year. Lower oil prices are likely to support disinflation next year. With DXY technically overbought and Fed policy expectations excessively hawkish, we expect a rebound in USD. Conversely, gold looks oversold. We see an upside for XAU/USD, despite revising lower our 3- and 12-month targets (see page 7).
— Rajat Bhattacharya
The weekly macro balance sheet
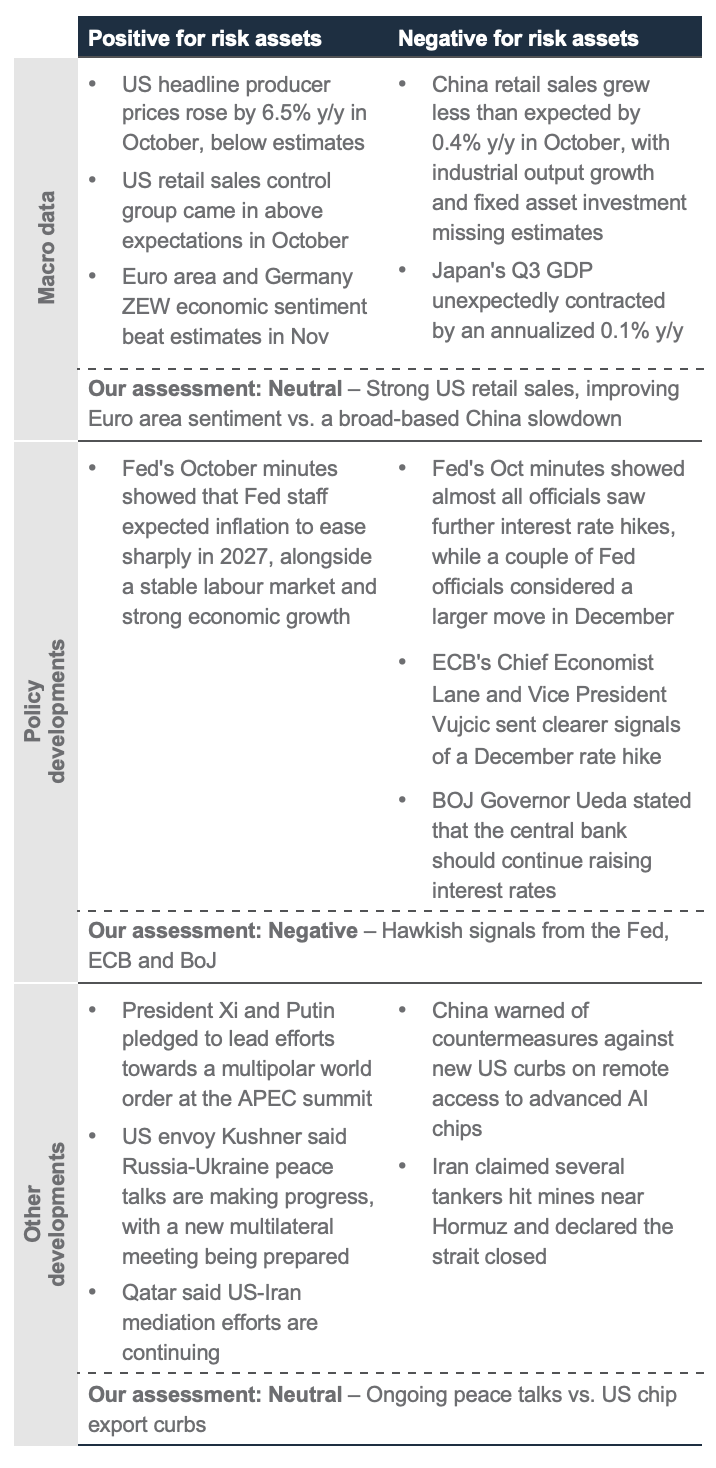
Our weekly net assessment: On balance, we see the past week’s data and policy as neutral for risk assets in the near-term
(+) factors: Strong US retail sales; ongoing peace talks
(-)factors: Broad-based China slowdown; hawkish central banks
US producer prices surged in October, though slightly below estimates, while retail control-group spending held up
US headline and core producer price inflation; US retail sales control group
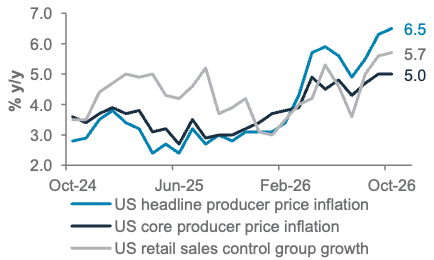
Source: Bloomberg, Standard Chartered
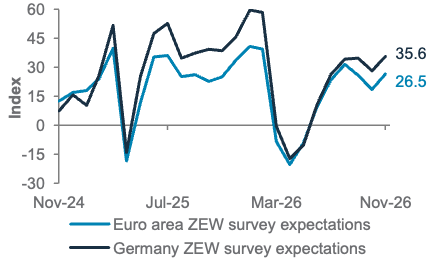
Euro area and German investor expectations both jumped to multi-month highs in November
Euro area and Germany ZEW economic expectations
Source: Bloomberg, Standard Chartered
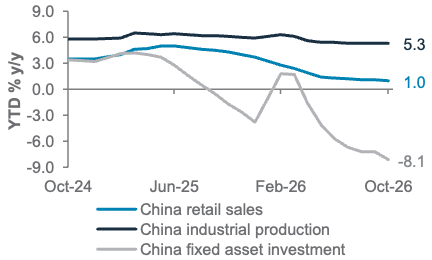
China’s fixed asset investment slump deepened in October, while retail sales and industrial output growth moderated
China retail sales, industrial production and fixed asset investment
Source: Bloomberg, Standard Chartered
Top client questions
How will the new US semiconductor restrictions impact the technology sector?
Our view: While compute is likely to remain a bottleneck for AI, greater US regulatory restrictions could weigh on AI capex.
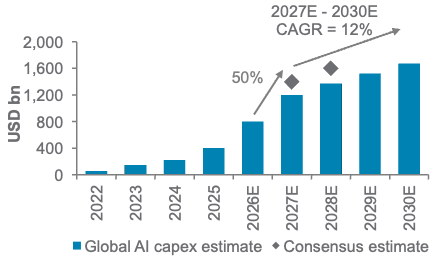
Rationale: The US has announced broader restrictions on overseas computing capacity used by Chinese and other restricted-country companies, extending controls beyond physical chip shipments to remote access through data centres. This could delay data centre deployments and raise financing costs, as affected operators may defer expansion plans until licences or replacement customers are secured. Lower spending could weigh on chip and hardware orders, bringing consensus capex estimates closer to our forecasts. While we expect AI capex to rise 50% to USD 1.2trn in 2027, supported by projects already under construction, the compound annual growth rate (CAGR) between 2027 and 2030 is likely to moderate to c.12%.
We therefore favour broadening technology exposure beyond semiconductors through our US Information Technology (IT) opportunistic idea, which also includes hardware and software industries. Investors should also consider diversifying into our other preferred sectors, such as US healthcare and financials.
— Ryan Goh, Investment Strategist
AI capital expenditure (capex) should continue to rise, but growth is expected to moderate from 2028
Global AI capex (USD bn)
Source: Company reports, Standard Chartered
How were Chinese technology giants’ Q3 2026 earnings?
Our view: Chinese tech giants’ Q3 earnings highlight growing demand for AI, but heavy spending is pressuring margins and cash flow, underscoring the need for stronger AI monetisation.
Rationale: Heavy AI capex continues to weigh on profitability, compressing near-term margins and deepening negative free cash flows, with share dilution a riskas tech giants may have to tap into equity markets for the AI buildout. Cloud growth points to genuine AI demand, but the AI-related revenue contribution remains small relative to the cost base. AI monetisation remains challenging, with competition set to intensify. Weak consumer spending was a common thread contributing to revenue misses. Major players reiteratedthe need for more tangible investment returns amid aggressive AI investments.
In the near term, investor sentiment remains weighed down by tightening US restrictions targeting China’s access to advanced chips, introducing downside risks to 2027 AI cloud revenue. While this could hamper the development of next-generation AI models, accelerating domestic AI chip adoption should benefit local semiconductor companies as China pushes for technological self-sufficiency.We expect rising AI adoption to benefit China’s IT sector over time, though we prefer diversifying our China equity exposure across preferred sectors, such as financials and healthcare.
— Cindy Lam, CFA, Senior Investment Strategist
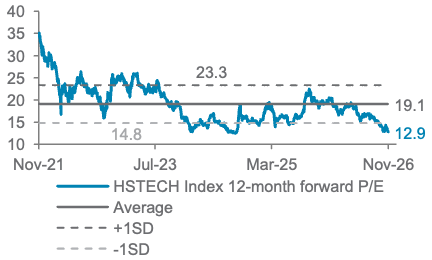
China’s technology sector valuation remains inexpensive at 12.9x, falling 1 standard deviation below the mean
Hang Seng Technology (HSTECH Index) 12-month forward price-to-earnings (P/E) ratio
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
What are the implications of the October Fed meeting minutes for the rate path forward and short-dated bonds? Do US 10-year government bonds now offer a good re-entry point?
Our view: October’s Fed meeting minutes maintained a hawkish-hold narrative. We continue to expect the Fed to raise rates by 25bps at its 8-9 December meeting. However, with short-dated US government bonds having largely priced in three hikes by June 2027, we see any spike above 5.25% in the US 10-year bond yield as an opportunistic bullish entry point.
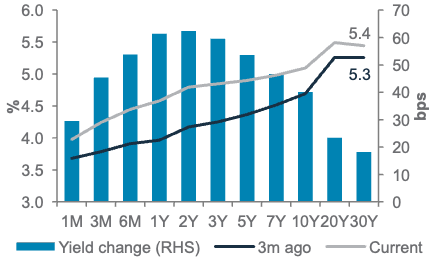
Rationale: The hawkish-hold tone of the Fed’s October meeting minutes suggests the December Fed meeting is ‘live’. The market is currently pricing in three hikes by year-end 2027 (vs. our expectation of two hikes by H1 2027 followed by a potential cut in H2 2027). Short-dated government bond yields – using the US 2-year yield as a proxy – have largely priced in three hikes, and we do not expect the hawkish minutes to have a material impact on them.
Should the US 10-year government bond yield spike above 5.25%, the near-term risk-reward would become favourable, in our opinion. As we expect inflation to moderate in H2 2027, we see scope for the Fed to pivot towards easing, and we would turn more constructive on short-dated government bonds. We expect the US 2-year government bond yield to decline to 4.00-4.25% in 12 months, contributing to yield curve steepening.
— Ray Heung, Senior Investment Strategist
US short-term government bond yields have largely priced in 2-3 Fed rate hikes
US government bond yield curve, current and three months ago
Source: Bloomberg, Standard Chartered
Is it time to add exposure to the EUR after its recent slide against the USD?
Our view: Yes, we are bullish on EUR/USD and favour gradually adding EUR exposure in the coming weeks. Markets are pricing in more Fed tightening than we expect. Lower oil prices support the Euro area and are likely to ease the Fed’s inflation concerns on a forward-looking basis.
Rationale: Lower oil prices are a double positive for EUR/USD, as they ease costs for Euro area households and businesses and temper US inflation, reducing the need for the Fed to tighten as much as markets expect.
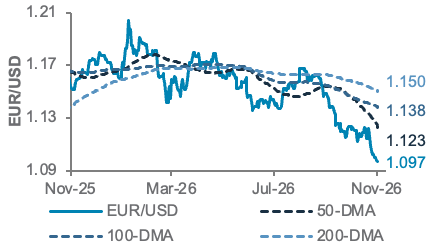
Markets are pricing in a terminal Fed funds rate close to 4.63%, down from 4.72% a week ago, with the yield curve now also pricing a rate-cutting cycle after the September 2027 peak. We expect the bullish near-term USD momentum to linger until markets’ peak rate expectations converge towards our view. EUR/USD’s relative strength index (RSI) is below 30, and consolidation above 1.0950 points to oversold conditions. We expect a rebound towards 1.11 to confirm our recovery view in the next three weeks.
— Vincent Tan, Senior Investment Strategist
EUR/USD oversold; near-term rebound risk grows
EUR/USD and technicals
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
What could support a sustained recovery in the AUD?
Our view: We believe a sustained AUD recovery requires a combination of domestic resilience and fading USD momentum.
Rationale: AUD/USD has been pressured by two key external headwinds: hawkish Fed repricing and weaker AI-related risk sentiment. A reversal in either could provide scope for recovery.
Softer US economic data or less hawkish Fed communication could ease upward pressure on US government bond yields, narrow rate differentials and weaken the USD. At the same time, a stabilisation in AI and broader equity sentiment could restore demand for the risk-sensitive AUD, particularly if Asian equities recover.
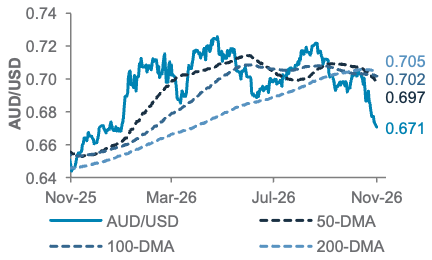
Domestic fundamentals remain a relative source of support. Still-elevated inflation should constrain the RBA’s ability to turn dovish quickly, while exporter and real-money demand for the AUD could cushion the downside. However, Australia’s rising unemployment raises the prospect of RBA rate cuts in H2 2027, potentially eroding the AUD’s carry advantage over time. With AUD/USD technically oversold, we see scope for a rebound from 0.6600, with 0.6830 as the key resistance level.
— Iris Yuen, Investment Strategist
Looking for a near-term AUD/USD rebound
AUD/USD and technicals
Source: Bloomberg, Standard Chartered
How will the improving oil supply-demand balance shape crude oil prices over the coming quarters?
Our view: Improving supply-demand balances should support inventory rebuilding and ease oil prices over time, despite persistent geopolitical risks, supporting disinflation in H2 2027.
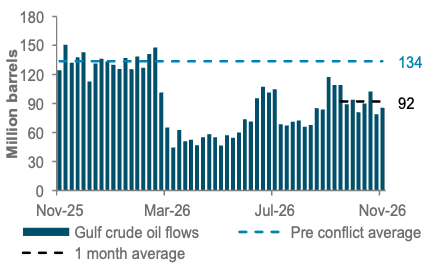
Rationale: Crude oil’s recent retreat marks an important transition: expanding physical supply is finally asserting control over headline geopolitical noise. With non-OPEC production resilient, Gulf exports recovering and alternative transit routes adapting, markets are steadily pricing in an approaching supply surplus.
However, high freight costs and extended voyage times keep significant crude oil volumes tied up at sea rather than refilling local storage tanks. Crucially, the US Strategic Petroleum Reserve’s crude inventories have fallen nearly 33% from pre-conflict levels, leaving a thinner buffer against renewed supply disruptions.
For investors, improving fundamentals point to gradual price normalisation as trade routes adapt, despite persistent geopolitical volatility. We expect near-term West Texas Intermediate (WTI) oil to range between USD 80/bbl and USD 90/bbl. Softer energy prices should provide some relief to headline inflation, but are unlikely to materially alter the Fed’s near-term policy trajectory.
— Anthony Naab, Investment Strategist
Gulf crude flows have recovered to nearly 70% of their pre-conflict levels, easing supply constraints
Gulf crude oil exports (mb/week)
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
Are there any tactical opportunities amidst the equity drawdown?
Our view: We introduce US mega cap equities as a new opportunistic idea, favouring their scale and financial strength amid heightened volatility and potential industry consolidation.
Rationale: We believe the mid-cycle backdrop favours large companies with strong cash generation, established competitive positions and the financial capacity to invest through periods of uncertainty. US mega caps’ forward P/E has fallen well below its two-year average and the -2x standard deviation level, offering a more attractive entry point into US market leaders.
A potential reset in AI capex expectations could also accelerate industry consolidation, favouring established leaders with the balance sheets, infrastructure and customer reach to sustain investment and capture market share. Key risks include a sharper-than-expected economic slowdown, weaker returns on AI investment, regulatory pressures, key man risks and concentration in a few dominant companies.
— Robin Xie, CFA, Senior Investment Strategist
We introduce US mega caps as a new opportunistic idea, favouring their scale and financial strength amid heightened volatility and potential industry consolidation
Equity opportunistic ideas: Adding US mega caps
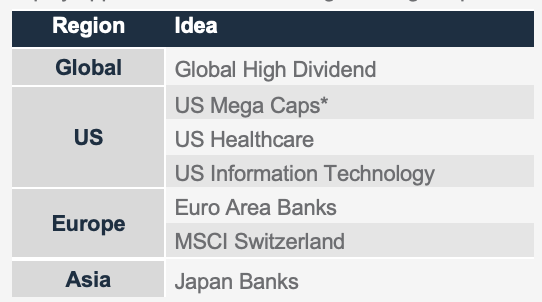
Source: Standard Chartered. * Denotes new idea, with performance measured based on the S&P Top 20 Select 35/20 Capped Index
Do you see opportunities in gold after the recent sell-off?
Our view: We are lowering our gold price targets to USD 4,000/oz (three months) and USD 4,500/oz (12 months). Despite gold’s recent drop below our revised three-month price target, we continue to believe the precious metal can rebound in the medium term.
Rationale: Several factors have been driving down gold prices. A combination of stronger-than-expected US jobs, consumer inflation and producer inflation reports since early November has reinforced the case for Fed tightening. This, in turn, brought renewed hawkish Fed rhetoric, driving up the repricing of Fed rate-hike expectations. Higher rates raise the opportunity cost of holding non-yielding gold, while also strengthening the USD – a double headwind for bullion. In addition, recent volatility in the equity markets has raised liquidity needs for leveraged investors, causing some of them to sell gold to cover their losses.
However, at current levels, gold has undershot even our newly revised three-month price target for the precious metal. Emerging Market central banks remain structural buyers of gold as they continue to shift away from USD-denominated reserves. The US fiscal outlook remains dire, and with political gridlock now having returned to Washington, persistent fiscal deficits with no reforms will likely remain entrenched for the next two years at least. Confidence in US government finances and the USD is expected to weaken into 2027, and investors are likely to once again turn to gold as a store of value, informing our 12-month price target of USD 4,500/oz.
— Jonathan Liang, CFA, CIO, Fixed Income and FX
Gold has fallen in line with rising Fed rate-hike expectations this year
Gold vs market implied fed funds rate (inverted)
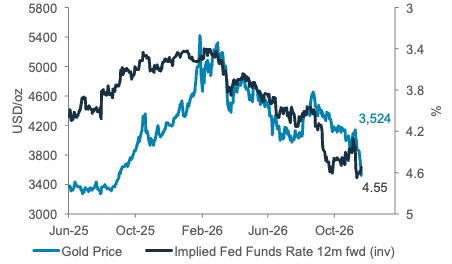
Source: Bloomberg, Standard Chartered
Market performance summary*
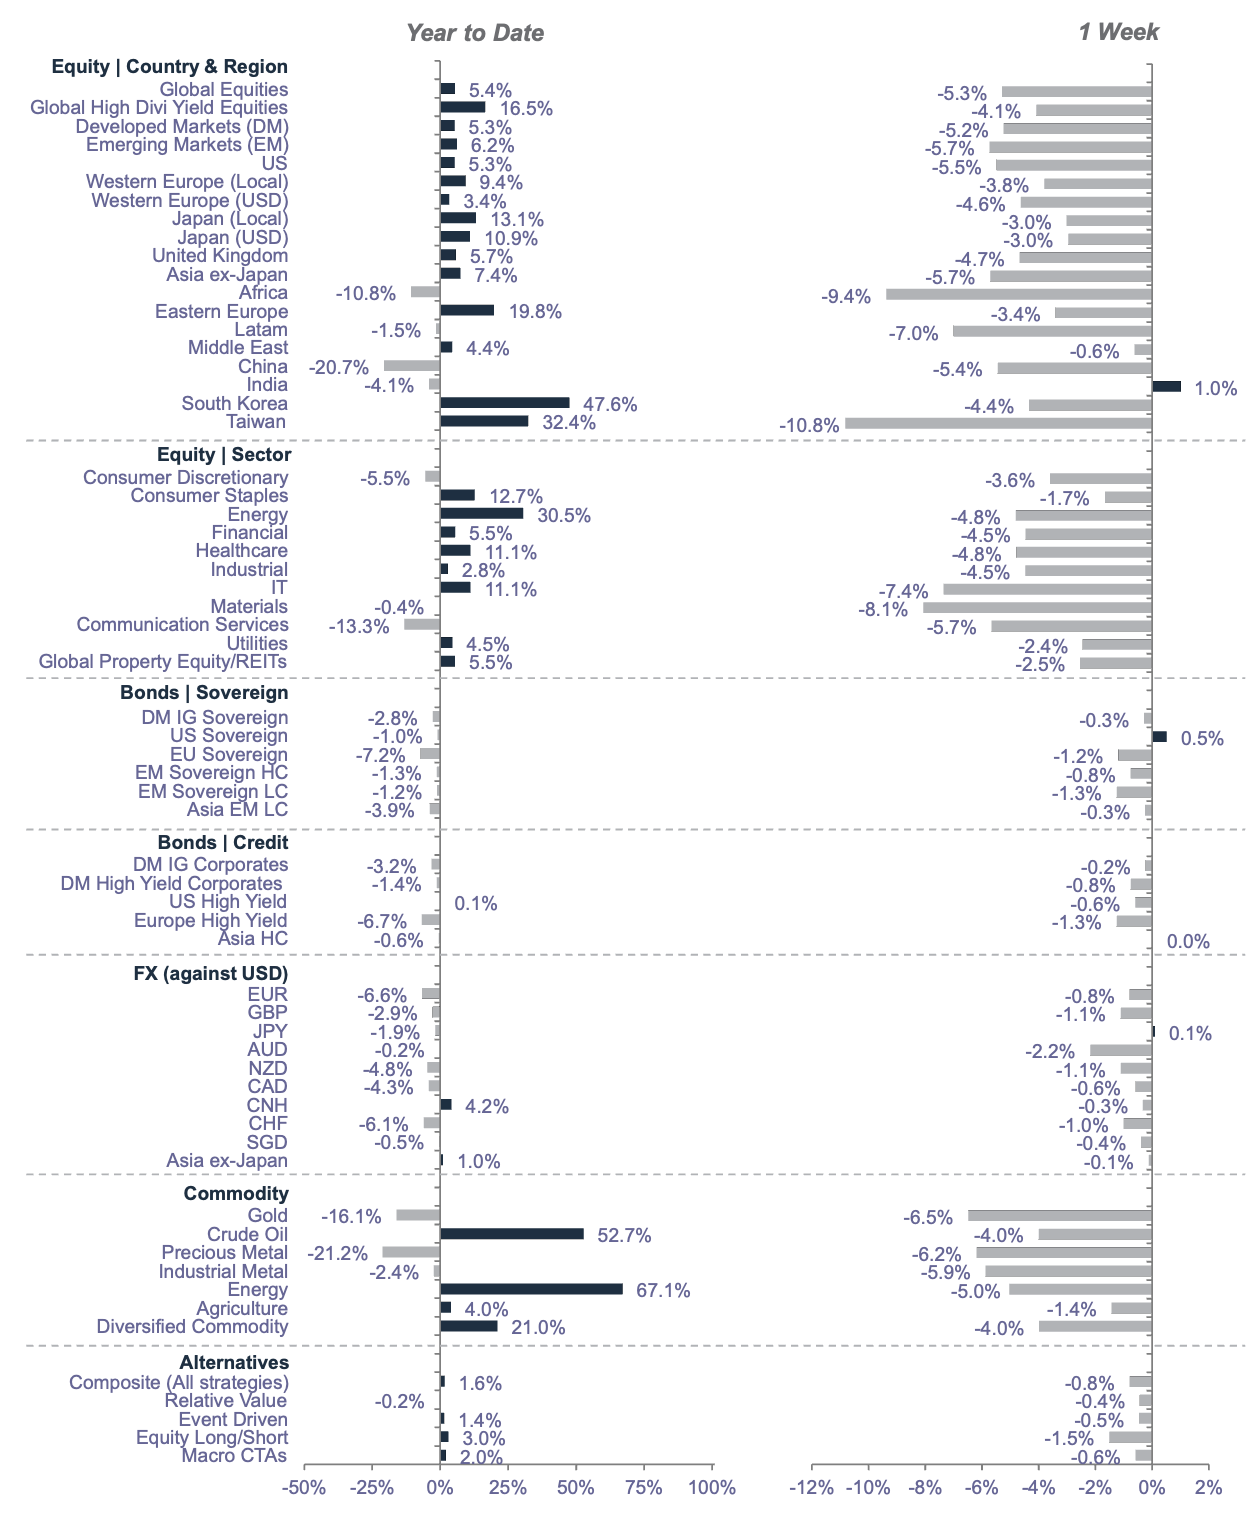
Sources: MSCI, JP Morgan, Barclays Capital, Citigroup, Dow Jones, HFRX, FTSE, Bloomberg, Standard Chartered
*Performance in USD terms unless otherwise stated, 2026 YTD performance from 31 December 2025 to 19 November 2026; 1-week period: 12 November 2026 to 19 November 2026
Our 12-month asset class views at a glance
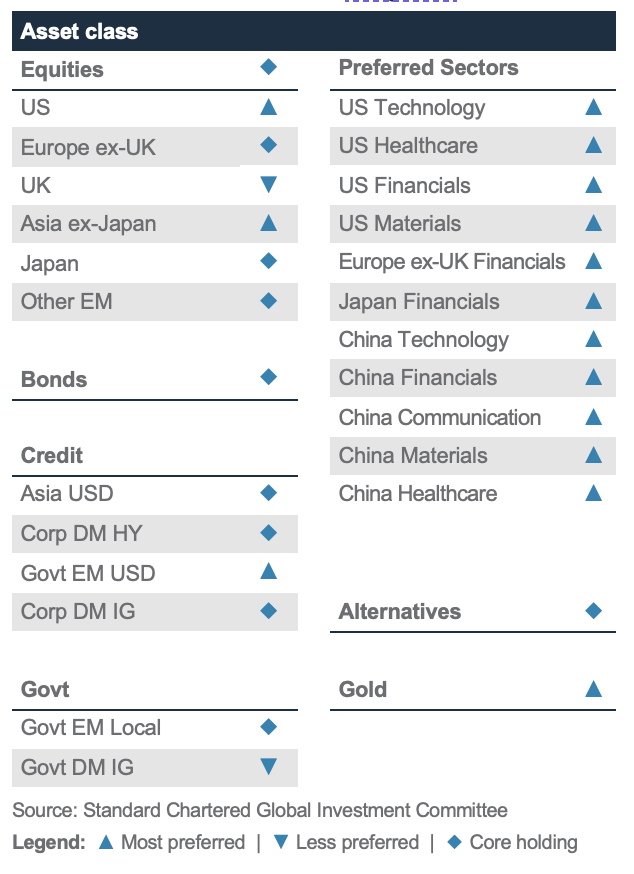
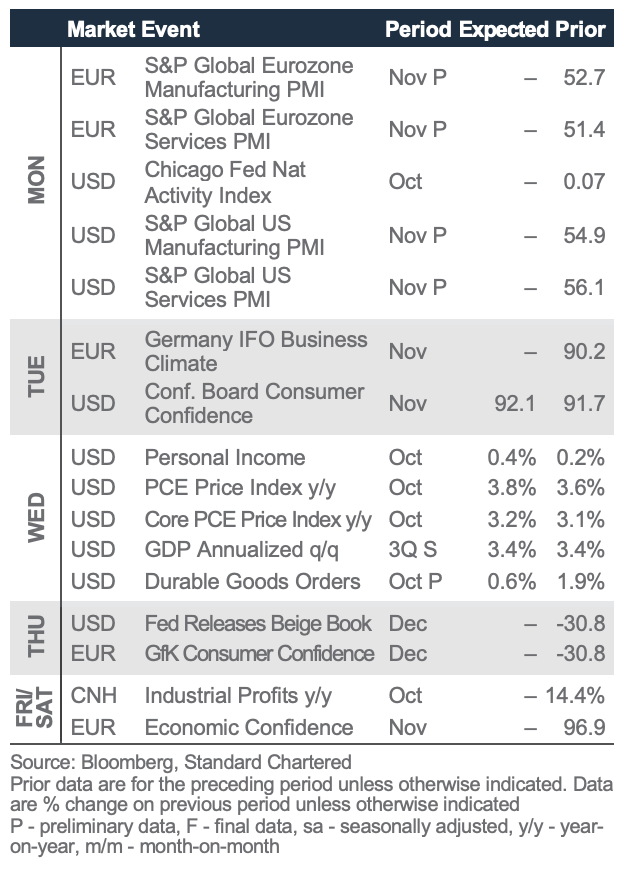
Economic and market calendar
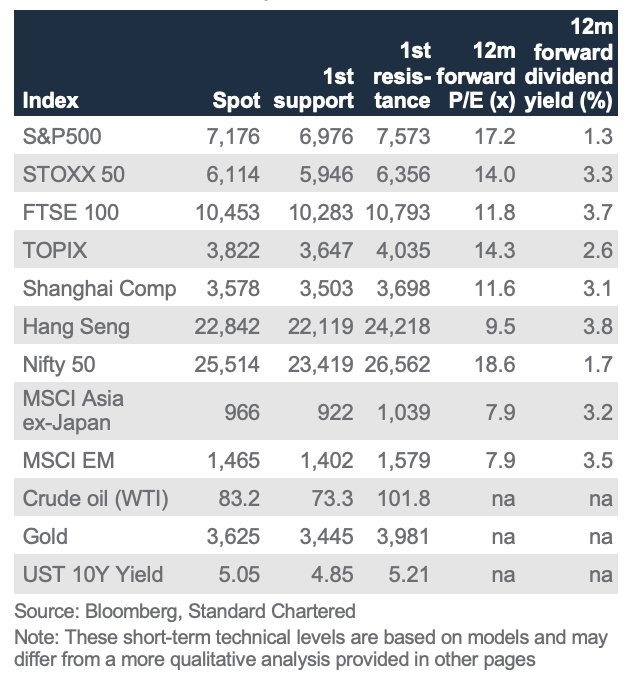
The S&P500 has next interim resistance at 7,573
Technical indicators for key markets as of 19 Nov close
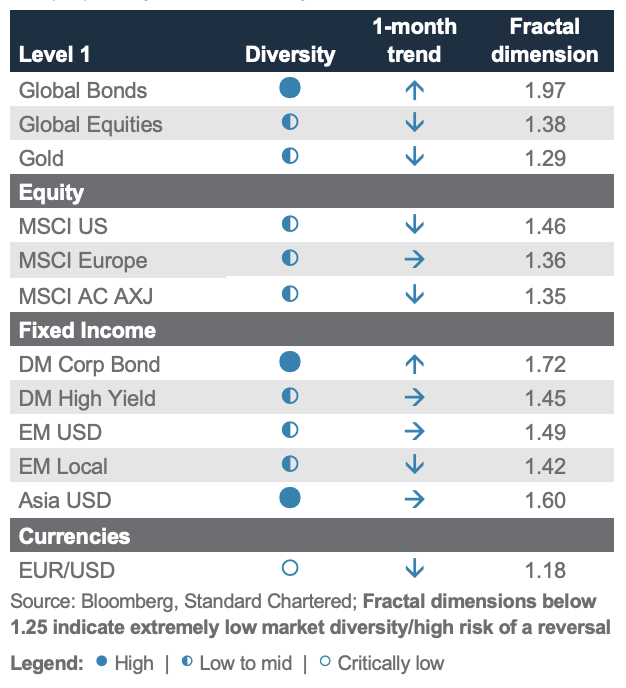
Investor diversity has normalised across asset classes
Our proprietary market diversity indicators as of 19 Nov close
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: Standard Chartered Bank, India (“Bank”) (ARN-1209) is an AMFI-registered distributor of select Mutual Funds and a referrer of certain third-party financial products. The Bank is not registered with SEBI as an Investment Adviser and does not provide investment advisory services or financial planning services as defined under the SEBI (Investment Advisers) Regulations, 2013. Any information contained herein is for informational purposes only and should not be construed as investment advice, recommendation, research report, or an offer to buy or sell any security or financial product. Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The services/products described herein are not intended for any person resident in a jurisdiction where their distribution, solicitation or use would be contrary to local laws or regulations. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom, and all business transacted with Standard Chartered Bank, Jersey Branch and other Standard Chartered Group Offices outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.