
23 October 2026
Weekly Market View
Policy, politics
and earnings
We retain our defensive and diversified stance across assets, sectors and regions amid near-term uncertainty around monetary policy, politics and earnings.
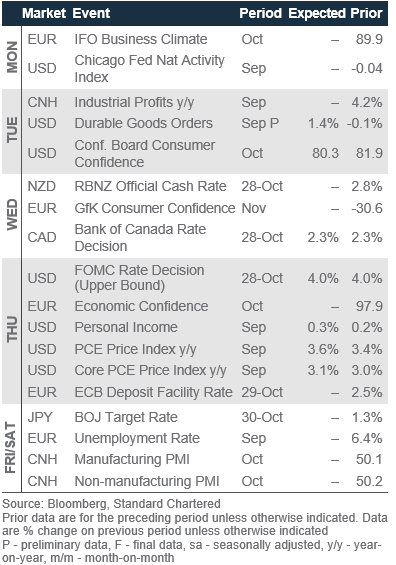
The next two weeks will be busy for major central banks, US political watchers and technology leaders powering the AI supercycle. We expect the Fed, ECB and BoJ to hold rates next week, but markets will focus on whether central banks are turning more hawkish due to the latest surge in fuel prices.
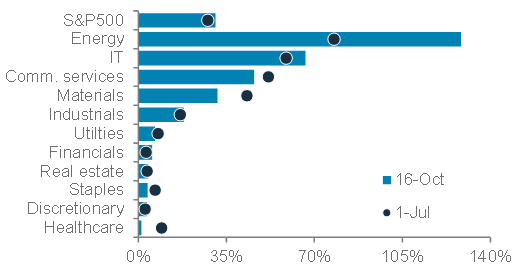
The US mid-term elections are expected to give Democrats control of the House and Senate, with implications for taxes and the AI-led investment boom. Meanwhile, the consensus is expecting the US tech sector to report over 60% y/y earnings growth for Q3.
Each of these three drivers has the potential to surprise markets. We close and lock in gains on our European CoCo1 bond and US 10-year government bond opportunistic ideas amid French and US political risks.
What are the takeaways from US tech sector earnings reported so far?
Are you still bullish on US 10-year government bonds?
Does Euro area fiscal and political uncertainty affect your EUR/USD view?
Charts of the week: Watching earnings and a potential ‘Blue wave’
US Big Tech earnings, mid-term elections and major central bank policy meetings are the near-term market drivers
Consensus S&P500 index Q3 earnings estimates by sector
Chance of Democrats winning control of US House and Senate*
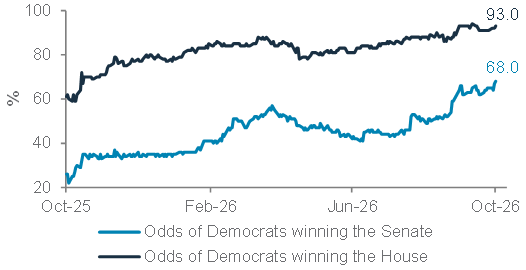
Source: Bloomberg, Standard Chartered; *Polymarket probability
Editorial
Policy, politics and earnings
Strategy summary: We retain our near-term defensive and diversified stance across assets, sectors and regions amid near-term uncertainty around monetary policy, politics and earnings. The next two weeks will be busy for major central banks, US political watchers and technology leaders powering the AI supercycle. We expect the Fed, ECB and BoJ to hold rates next week, but markets will focus on whether central banks are turning more hawkish due to the latest surge in fuel prices. The US mid-term elections are expected to give Democrats control of the House and Senate, with implications for taxes and the AI-led investment boom.
Meanwhile, the consensus is expecting the US tech sector to report over 60% y/y earnings growth for Q3, the biggest jump in over two decades outside the post-COVID rebound. Each of these three drivers have the potential to surprise markets.
Big Three to hold monetary policy: We expect the Fed, ECB and BoJ to hold policy rates next week, after September’s hikes, as they assess whether higher bond yields have tightened financial conditions enough to offset fuel-price-driven inflation. We expect the Big Three to hike next in December as fuel prices are likely to stay elevated into early next year due to refining capacity constraints. Nevertheless, the Fed and ECB are likely to deliver less than around 60bps of rate hikes priced in by money markets over the next 12 months on the back of an eventual easing of oil and fuel prices leading to disinflation by H2 2027. This outlook means 3-7-year Developed Market investment grade bonds currently offer attractive risk-reward.
Opportunity in Australian bonds. Other major central banks, such as the Bank of England, Bank of Canada and Reserve Bank of New Zealand are likely to hike rates by 25bps in the next two weeks given their focus on taming near-term inflation. However, we believe the Reserve Bank of Australia (RBA) is close to the end of its hiking cycle, even if it hikes one last time in the coming months (money markets give a 60% chance of a hike on 3 November). Australia’s domestic labour and housing markets and business confidence are softening after the RBA hiked its policy rate four times this year to a 15-year high.
Meanwhile, Australia’s cash rate is 60bps higher than the US policy rate, supporting the AUD. We continue to see attractive income and FX gain opportunities from AUD corporate bonds.
A ‘Blue Wave’ in the US? Prediction markets strongly favour Democrats taking the House of Representatives and possibly the Senate in the 3 November US mid-term elections. While an opposition sweep in the mid-terms has historically delivered the best 12-month returns for equities among all scenarios, partly due to the resulting policy gridlock, a decisive Democratic “blue wave” could increase longer-term risks of higher taxes and uncertainty over policy towards AI investment and data centres. With the Senate race still close and prediction markets fallible, we remain cautious on risk assets in the near term.
Closing EU bank contingent convertible bonds (CoCos1) and US 10-year government bond ideas: We lock in 2% gains in EU CoCos and 1.7% gain in US 10-year government bond ideas amid French and US political risks (page 5-6). We continue to hedge any inflation risks through inflation-protected bonds and geopolitical risk through an Overweight in gold.
Watching Big Tech earnings: Upcoming Big Tech earnings raises uncertainty as market leadership remains concentrated and share-price reactions more mixed. With valuations less likely to drive returns, earnings delivery and sustainability of AI investment, funding and monetisation and broadening out of earnings beyond tech will be critical, raising the risk of volatility and sector divergence. We remain invested but defensively positioned, favouring diversification across sectors and regions.
Staying defensive and diversified. We recently upgraded the defensive US Healthcare sector to Overweight, while retaining our Overweights to US tech and materials as well as financials in the US, Euro area and Japan. We also downgraded the more volatile Communications Services sector to Neutral and took profits on the semiconductor segment earlier this month before the latest correction. Our defensive and diversified stance should preserve participation in further equity upside, while reducing exposure to earnings disappointments and supporting resilience through the reporting season.
— Rajat Bhattacharya
The weekly macro balance sheet
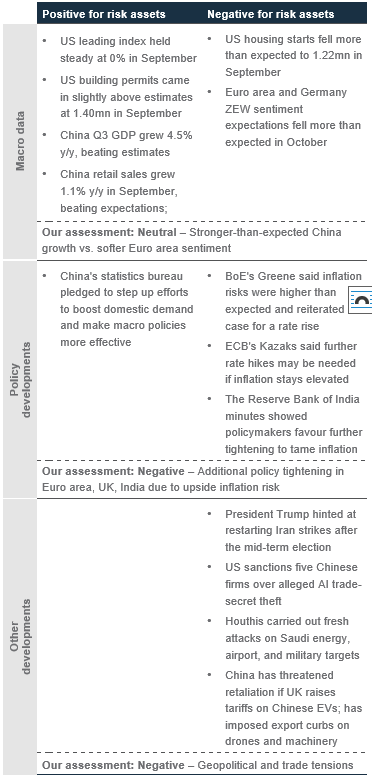
Our weekly net assessment: On balance, we see the past week’s data and policy as negative for risk assets in the near-term
(+) factors: Resilient China growth; potential China fiscal policies
(-)factors: Softer Euro area sentiment; geopolitical and trade tensions
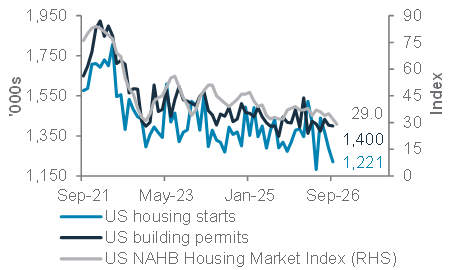
US housing starts slumped in September as high mortgage rates hurt, while housing permits offered limited support to future construction
US housing starts, building permits and the NAHB Housing Market Index
Source: Bloomberg, Standard Chartered
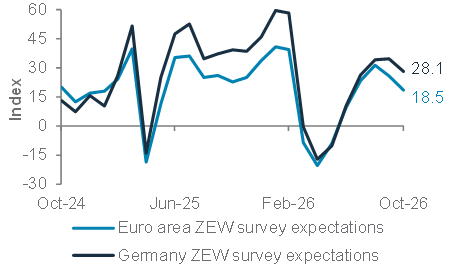
Euro area ZEW expectations fell to a four-month low in October, with Germany’s expectations missing estimates
Euro area and Germany ZEW survey expectations
Source: Bloomberg, Standard Chartered
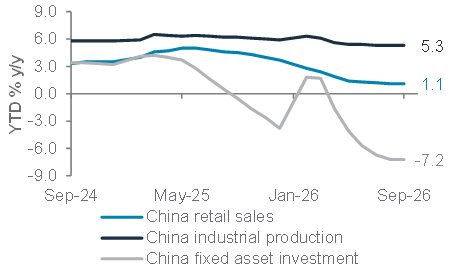
China’s recovery remains uneven, with resilient industrial production contrasting with subdued retail sales and contracting fixed asset investment
China retail sales, industrial production and fixed asset investment growth
Source: Bloomberg, Standard Chartered
Top client questions
What are the key takeaways from the technology sector earnings reported so far this week?
Our view: Recent technology sector earnings results point to strong compute demand and continued capex expansion, supporting our positive long-term view on the AI investment theme. However, rising funding and execution risks warrant near-term caution. We prefer to avoid increasing exposure to higher-risk areas within the technology sector for now.
Rationale: Earningsresults reported this week suggest major tech companies remain committed to expanding their AI infrastructure. While this bodes well for AI infrastructure providers, ambitious expansion plans imply that an increasing share of AI capex is likely to depend on debt financing. We expect debt-financed AI capex to rise from c.25% of AI capex in 2026 to c.40% in 2027.
Greater reliance on borrowing increases sensitivity to interest rates, while deployment delays could postpone revenue recognition amid ongoing financing costs. However, evidence of improving AI monetisation and adoption should strengthen operating cash flows and support internal capex funding. Against this backdrop, we will assess Big Tech earnings next week for greater clarity on capex guidance and funding and AI monetisation trends.
— Ryan Goh, Investment Strategist
AI capital expenditure (capex) is expected to become more reliant on debt financing
Estimated share of AI capex financed through debt
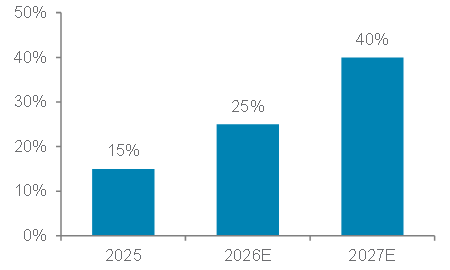
Source: Company reports, Standard Chartered
Are you still positive on Euro area bank equities amid heightened political and fiscal uncertainty in the region?
Our view: We remain positive on Euro area bank equities, supported by resilient earnings and shareholder-friendly capital return policies. While France’s fiscal uncertainty and a softer growth outlook warrant caution, the recent pullback in Euro area bank equities offers selective opportunities. We favour well-capitalised banks with strong deposit franchises and diversified earnings.
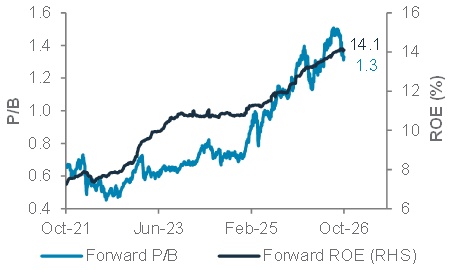
Rationale: We expect Euro area banks’ Q3 2026 net interest income to grow 1.5-3.0% q/q, led by Spanish banks, driven by higher rates and continued asset repricing. Resilient fee income from wealth management and investment banking activity, as well as dividends and buybacks, should provide further support. Price-to-book (P/B) valuations have eased, despite expectations for healthy return on equity (ROE), thus improving risk-reward.
Fiscal uncertainty in France has widened sovereign spreads, pressuring banks’ bond holdings and funding costs. Although French banks represent 13% of the Euro area Bank Index, volatility could spread to regional financial markets. However, stress in the broader banking system appears limited, supported by strong capital buffers and ECB tools to contain disorderly market moves and sovereign market contagion. We will continue to monitor credit trends, sovereign spreads and banks’ 2027 earnings guidance.
— Robin Xie, Senior Investment Strategist
Euro area banks’ valuations have eased despite resilient profitability expectations
Forward P/B ratio vs. expected ROE
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
What has driven the recent weakness in China equities, and what is your outlook from here?
Our view: We maintain China equities as a Core holding, as valuations remain inexpensive. Rapid technological innovation and investment in AI localisation provide tailwinds, but the potential for a re-rating appears delayed. Investors should seek to diversify their portfolios and reduce concentration risk.
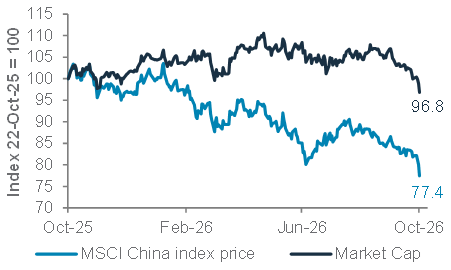
Rationale: China equities have weakened, driven by mounting scepticism over AI capex returns, structural margin compression and concerns about the country’s significant financing requirements. Another notable feature in China has been significant share issuance, which has diluted earnings per share and weighed on the MSCI China Index’s performance. These pressures have been compounded by geopolitical headwinds, restrictions on advanced chips, an enduring property sector contraction and weak domestic demand. September’s stimulus measures also disappointed markets in terms of their scale and pace of delivery.
Notwithstanding these headwinds, valuations remain inexpensive, supported by rapid domestic innovation and structural tailwinds in AI localisation, leading us to retain China equities as a Core holding. Elevated volatility reinforces the need to be defensively positioned, favouring diversification rather than relying on technology sector concentration. We also remain Overweight China’s healthcare, financial and materials sectors.
— Cindy Lam, CFA, Senior Investment Strategist
Significant share issuance has kept the market capitalisation fairly stable, while the MSCI China Index has declined c.20% over the past one year
MSCI China Index price and market capitalisation
Source: FactSet, Bloomberg, Standard Chartered
Are you still bullish on US 10-year government bonds?
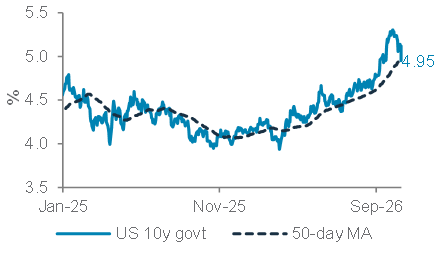
Our view: We are closing our opportunistic bullish idea on US 10-year government bonds at a gain of 1.7%. The risk-reward has become less compelling after the yield broke below 5%, the lower bound of our three-month forecast range of 5.00-5.25%.
Rationale: The US 10-year yield fell over 17bps to 4.97% on 22 October – its first move below 5% since 23 September and biggest one-day drop since March 2023. A sell-off in AI-related equities and renewed Middle East tensions drove investors towards safe havens. Earlier this month, the yield hit its highest level in over two decades. The forces behind the rally are fragile, though. Oil prices remain elevated amid escalating Middle East tensions, and September US consumer inflation rose to 3.7% y/y. Fed officials have signalled there is no urgency to raise rates at the 27-28 October meeting, but persistent price pressures keep further tightening on the table. We prefer to lock in gains and close our opportunistic bullish idea on 10-year government bonds at a gain of 1.7%.
— Jonathan Liang, CFA, CIO, Fixed Income & FX
Risk-reward of US 10-year government bond yields is less compelling after the yield broke below 5%
US 10-year government bond yields
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
What is your outlook for French bank bonds, especially ahead of France’s upcoming sovereign credit rating reviews?
Our view: The recent sell-off in French bank bonds is a repricing of tail risks, not a credit story. We expect further price volatility until the April 2027 French presidential election, particularly at the junior end of the capital structure, so we are closing our opportunistic EU bank contingent convertibles (CoCos1) idea at a gain of 2.0%.
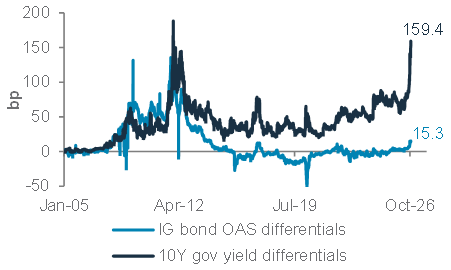
Rationale: We believe the recent sell-off in French bank bonds reflects domestic political and fiscal risks rather than weaker credit fundamentals. The sustained widening of the OAT-Bund spread has raised concerns about the profit and loss (P&L) impact on banks’ sovereign debt holdings. Banks provide limited disclosure on these exposures. However, banks’ investment portfolios are generally diversified, and holdings booked at amortised cost should soften the P&L impact. Near-term catalysts include the upcoming sovereign credit rating reviews. A sovereign downgrade could trigger bank rating downgrades, with domestically focused lenders potentially more exposed than regionally diversified peers. A sovereign credit event is not our base case, but we expect headline risks to persist until the French presidential election. Against this backdrop, we are closing our opportunistic EU bank CoCos idea.
— Cedric Lam, Senior Investment Strategist
A widening France-Germany 10-year government bond yield spread and a stable investment-grade (IG) bond option-adjusted spread (OAS) suggest a repricing of political and fiscal risk rather than credit risk
France-Germany IG bond OAS and 10-year government bond yield differentials
Source: Bloomberg, Standard Chartered
Will the November US mid-term elections and European bond volatility support a sustained Swiss franc (CHF) rebound?
Our view: We expect a near-term CHF rebound, supported mainly by safe-haven demand amid European bond volatility. We believe the US mid-term elections will be a secondary driver.
Rationale: European sovereign bond volatility provides the stronger catalyst for CHF strength. The France-Germany government bond yield spread remains elevated near 160bps, reflecting heightened French fiscal concerns and reinforcing the CHF’s safe-haven appeal. The US mid-terms could provide additional support for the CHF. A Democratic victory in either chamber is expected to constrain further fiscal expansion, potentially weighing on the USD. However, this would not necessarily lead to faster fiscal consolidation.
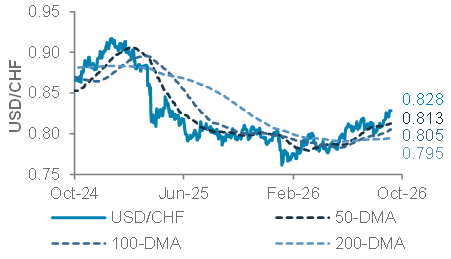
The SNB’s 0% policy rate leaves the CHF at a sizeable interest-rate disadvantage vs. the USD, constraining sustained CHF gains. With EUR/CHF below 0.90, excessive CHF strength could also increase the risk of SNB intervention. A decisive USD/CHF break below 0.8130 would strengthen the technical case for a more sustained CHF rebound.
— Vincent Tan, Senior Investment Strategist
— Iris Yuen, Investment Strategist
USD/CHF failed to break above 0.8400 and is likely to test support at 0.8130
USD/CHF and technical indicators
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
Would worsening budget deficits and political uncertainty across parts of Europe affect your view on EUR/USD and Euro area government bond yields?
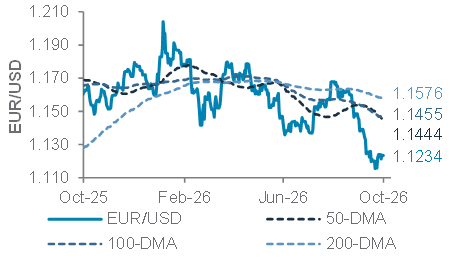
Our view: Fiscal and political concerns constrain near-term EUR/USD gains, with France being the primary vulnerability. We expect EUR/USD to recover towards the 1.17-1.18 range over the next 12 months, supported by continued Euro area economic growth and an expected fading of USD support. We expect wider differentials in Euro area government bond yields, with political risk premium elevated in French government bonds (OATs) and German government bonds (Bunds) supported by safe-haven demand.
Rationale: France’s high public debt, large budget deficit and political obstacles to fiscal adjustments are weighing on market confidence, with the country’s 10-year government bond yield rising above 5%. The risk of stress spreading to Italy and Spain adds to regional concerns, although current evidence does not establish a broad European fiscal crisis. German government bonds should benefit from safe-haven demand, while fiscal concerns keep risk premia on vulnerable countries’ bonds elevated. EUR/USD remains more sensitive to US-Germany interest-rate differentials and broader market confidence than to French bond yields alone.
France’s fiscal risks, elevated energy costs and high US interest rates weigh on the EUR in the near term. Over the next 12 months, Germany’s multi-year public investment programme, resilient exports and sound banking-sector fundamentals are expected to support Euro area growth. We expect the Fed’s rate-hiking cycle to peak by mid-2027, reducing USD support and driving the EUR towards 1.17-1.18 .
The principal tail risk is fiscal stress widening government bond yield spreads and spilling over into bank funding conditions and lending activity, weakening growth and delaying the EUR’s recovery.
— Vincent Tan, Senior Investment Strategist
— Cedric Lam, Senior Investment Strategist
France’s fiscal risks constrain near-term EUR/USD gains, but a modest recovery remains likely
EUR/USD and technical indicators
Source: Bloomberg, Standard Chartered
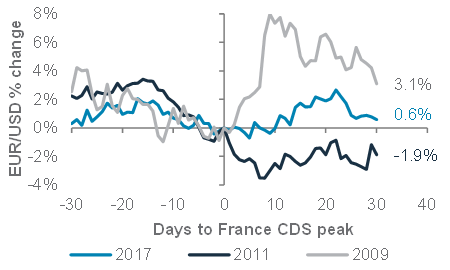
EUR/USD has tended to strengthen following France’s past credit default swap (CDS) peaks
EUR/USD % change, France’s five-year CDS
Source: Bloomberg, Standard Chartered
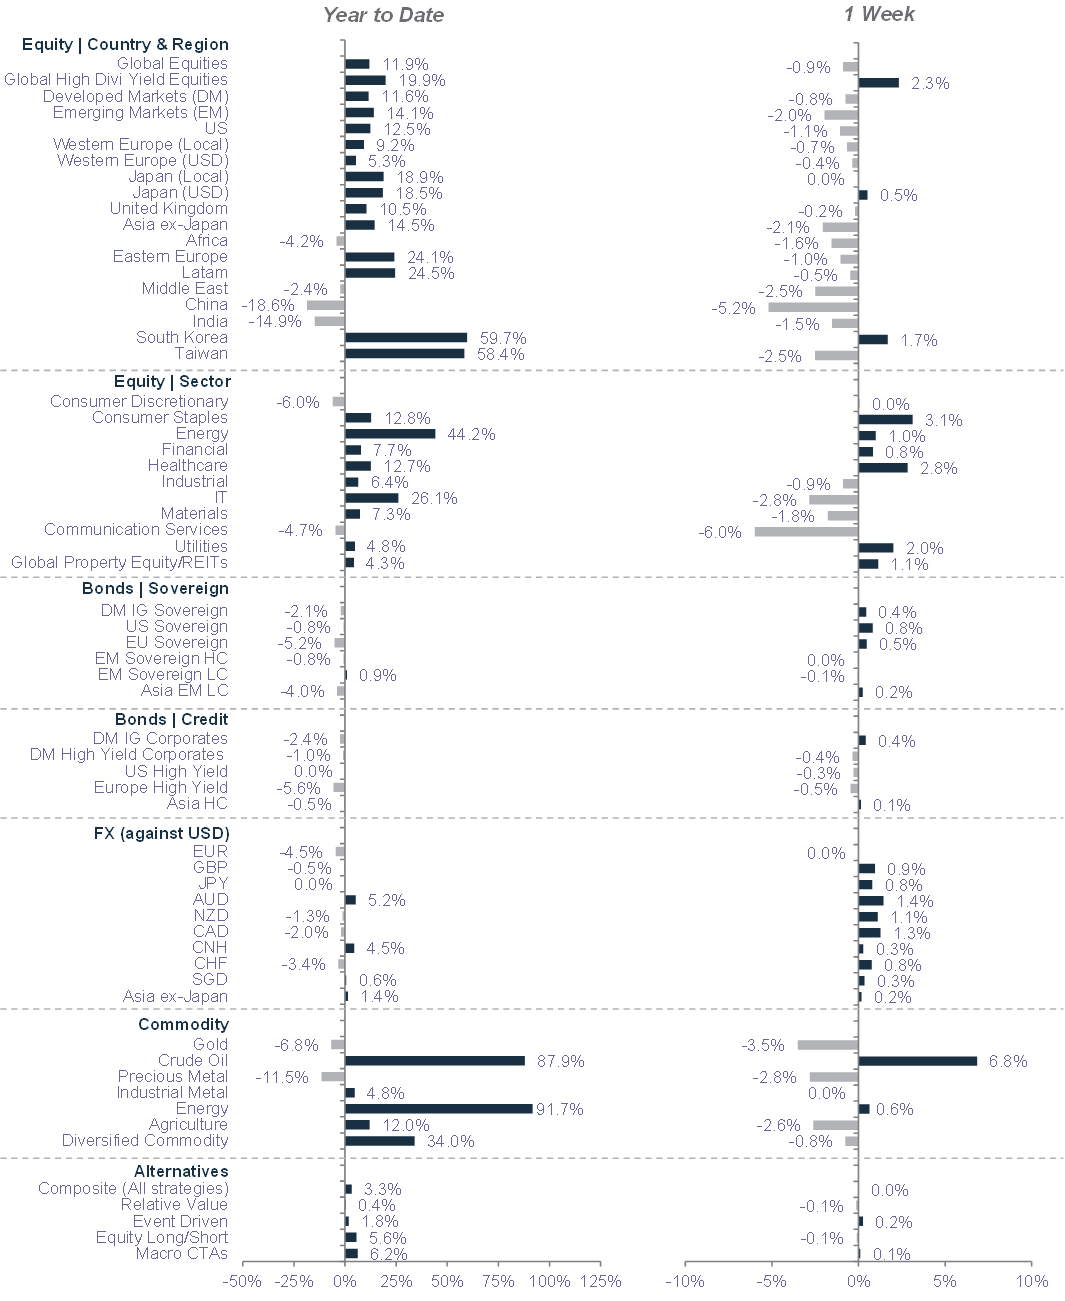
Market performance summary*
Sources: MSCI, JP Morgan, Barclays Capital, Citigroup, Dow Jones, HFRX, FTSE, Bloomberg, Standard Chartered
*Performance in USD terms unless otherwise stated, 2026 YTD performance from 31 December 2025 to 22 October 2026; 1-week period: 15 October 2026 to 22 October 2026
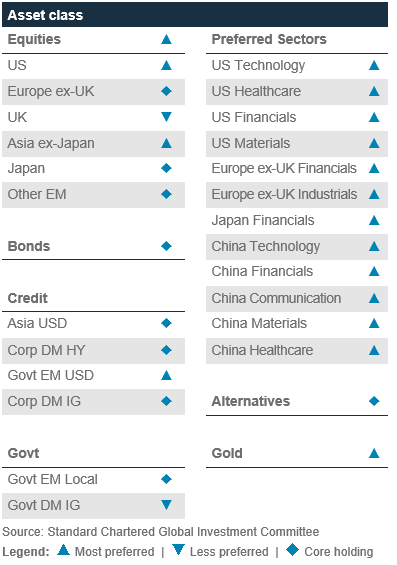
Our 12-month asset class views at a glance
Economic and market calendar
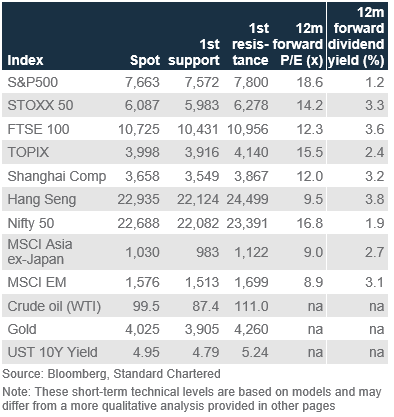
The S&P500 has next interim resistance at 7,800
Technical indicators for key markets as of 22 Oct close
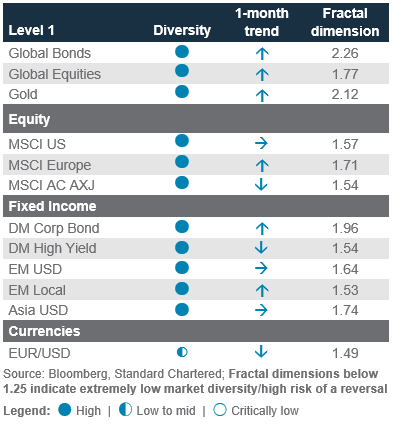
Investor diversity has normalised across asset classes
Our proprietary market diversity indicators as of 22 Oct close
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: This document is being distributed in India by Standard Chartered in its capacity as a distributor of mutual funds and referrer of any other third party financial products. Standard Chartered does not offer any ‘Investment Advice’ as defined in the Securities and Exchange Board of India (Investment Advisers) Regulations, 2013 or otherwise. Services/products related securities business offered by Standard Charted are not intended for any person, who is a resident of any jurisdiction, the laws of which imposes prohibition on soliciting the securities business in that jurisdiction without going through the registration requirements and/or prohibit the use of any information contained in this document. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: In Jersey, Standard Chartered Global Private Bank is the Registered Business Name of the Jersey Branch of Standard Chartered Bank. The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom and all business transacted with Standard Chartered Bank, Jersey Branch and other SC Group Entity outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.