

30 August 2024
Global Market Outlook
Global Market Outlook
Shifting winds
Uncertainty is on the rise. While we expect a soft landing in the US economy, focus on the US election is increasing and the geopolitical situation remains fragile. The good news is the Fed looks set to cut interest rates.
The rebound in global equities has discounted a lot of the positives. We expect bouts of volatility in the coming months. We are moving to a Neutral allocation for global equities, albeit with a continued preference for US equities within that.
The global monetary policy easing cycle is likely to reduce returns on cash. We would look at any yield surges towards 4% in US government bonds as an opportunity to add to high quality bonds. EM USD government bonds still preferred. Gold likely to be a beneficiary of lower interest rates and heightened uncertainty.
How to position ahead of Fed rate cuts?
Why do you still prefer US equities regionally?
How far can gold gains extend?
Strategy
Investment strategy and key themes
|
|
||||
|
Our top preferences
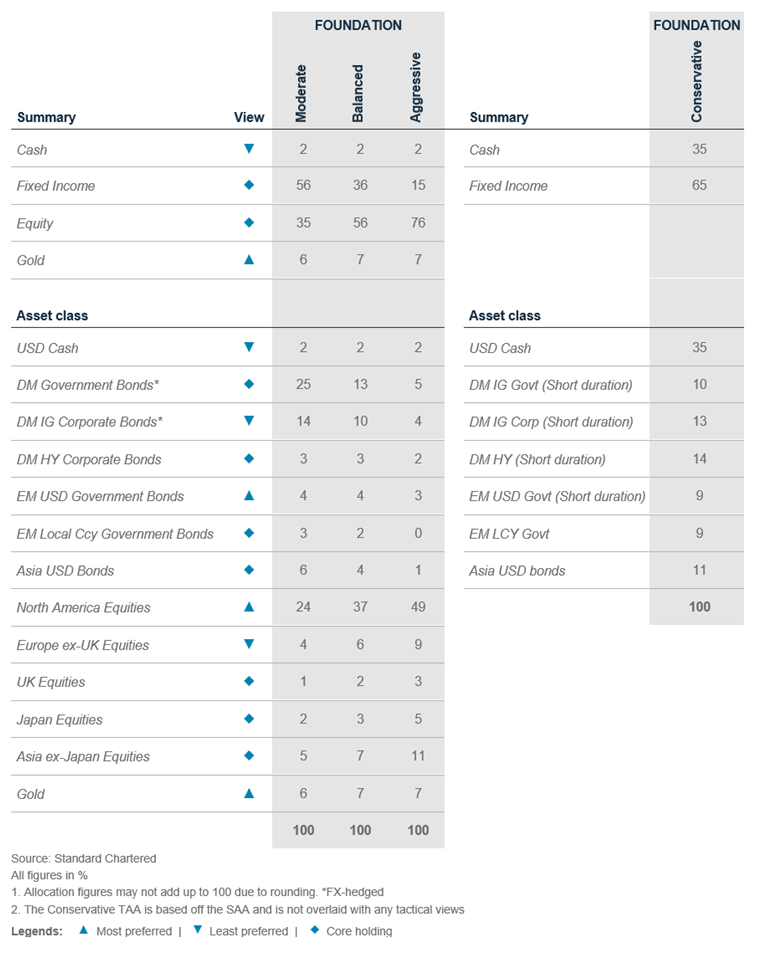
Foundation Allocations
- OW gold, N equities/bonds
- In equities: OW US
- In bonds: OW EM USD bonds
Opportunistic Allocations
Equity BUY ideas
- US technology, comm. services, healthcare sectors, large banks
- India large cap equities
- China non-financial divi SOEs
- Japanese banks
- Europe healthcare
Bond BUY ideas
- Europe govt. bonds (FX-hedged)
- INR local currency bonds
- US Agency MBS
- China USD bonds
- 20-year US government bond
- Global convertible bonds
FX views
- Modestly weaker USD
Shifting winds
- Uncertainty is on the rise. While we expect a soft landing in the US economy, focus on the US election is increasing and the geopolitical situation remains fragile. The good news is the Fed looks set to cut interest rates.
- The rebound in global equities has discounted a lot of the positives. We expect bouts of volatility in the coming months. We are moving to a Neutral allocation for global equities, albeit with a continued preference for US equities within that.
- The global monetary policy easing cycle is likely to reduce returns on cash. We would view any yield surges towards 4% in US government bonds as an opportunity to add to high quality bonds. EM USD government bonds are still preferred. Gold is likely to be a beneficiary of lower interest rates and heightened uncertainty.
Sailing with the wind
Our 2024 theme was ‘Sailing with the Wind’. We argued slowing growth and falling inflation would allow the Fed to cut interest rates, supporting both bonds and equities. After equity markets’ challenging start to August, the past few weeks have epitomised this, with a weaker labour market cementing expectations for the Fed to start cutting interest rates. This has brought bond yields markedly lower, supported equity markets and pushed gold prices to all-time highs.
Winds may be shifting
Two key uncertainties are facing markets in the remainder of 2024. First, will the US be able to pull off a soft landing? Second, what are the implications of the US election for markets?
On the former, we have seen another of our recession triggers, focused on the labour market, breached in the past month. Despite this, we maintain our central scenario for a US soft landing and only a 20% probability of a US recession in the next 12 months. Why is this? First, we all still have the scars from pre-emptively calling for a recession in 2022/3 based on indicators that had historically quite good hit rates (as high as 100%) when it came to forecasting a recession.
Fig. 1 US unemployment rises due to rising labour supply (good for equities) and falling demand (bad)
US hiring rate and flow of new entrants and re-entrants into the labour market
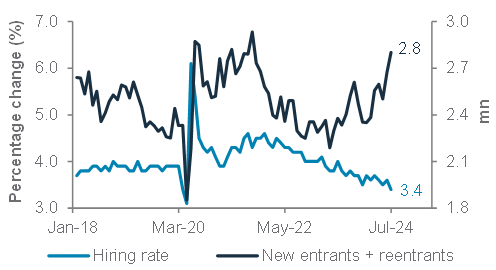
Second, the weakness in the labour market is not just all about falling demand – there has also been rising supply in the form of increased immigration. Falling demand is bad as it suggests the economy is weakening and business leaders are getting more cautious. However, increasing labour supply is great for the economy as it increases the pace at which the economy can grow without generating inflationary pressures.
On balance, we see increased labour supply, together with easing financial conditions as central banks ease policy, allowing the economy to experience a soft landing.
Neutral allocation to global equities
Despite this, we are downgrading equities to a Neutral (core holding) allocation this month. Markets appear to be priced for a soft landing and cash holdings remain relatively low, even though global investors seem to have raised cash holdings slightly. This suggests possible further bouts of volatility.
We believe the US election is a potential source of volatility. Harris’ entry has made the race a lot tighter. This increases the chances of a Democratic presidential victory, but also reduces the likelihood of a Republican clean sweep. As we argued last month, a Trump victory with a split Congress would likely be the most challenging backdrop for equity markets as you get the negative impact from aggressive trade policies without the positives from lower tax rates. If this scenario comes back into play, it could raise market concerns.
Meanwhile, geopolitics could also escalate in the short term. The recent sustained Ukrainian incursions into Russia could raise concerns about a step-change in Russia’s response. Elsewhere, the risk of an escalation in the Middle East conflict could place further upward pressure on oil prices, potentially threatening the soft-landing scenario.
Within equities, we continue to have a preference for US equities. The outlook for a soft landing and lower interest rates should support US equities, especially the growth areas of the market. Earnings growth estimates are also supportive and, in the event of a harder than expected economic landing, the US is likely to outperform (although valuations may limit the size of outperformance in this scenario).
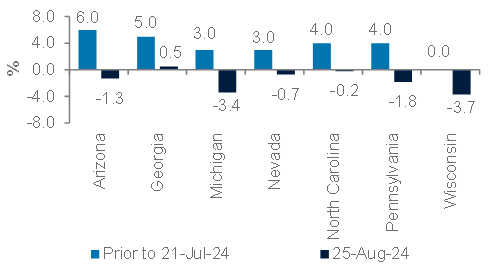
Fig. 2 Harris makes significant poll gains, including in the key swing states, but the hard work starts now
Trump’s lead in swing states versus Biden (before he exited the race) and Harris (latest)
Bond yields have peaked
Despite potential bumps along the ways, especially if oil prices surge further, we believe the outlook for weaker growth and falling inflation will mean that bond yields have peaked. We would look for any jump in US government bond yields towards 4% as an opportunity to add exposure to bonds and lengthen the maturity profile of bond portfolios.
Within bonds, we remain overweight Emerging Market USD government bonds, which have higher sensitivity to changes in yields, and spreads relative to history are wider than elsewhere in the credit space. Falling yields and interest rates should help support the performance of income investments relative to cash. In our multi-asset income allocation, we have reduced our floating rate and sub-financials exposure and added to Developed Market High Yield bonds.
Gold the outperformer
We are upgrading gold to an overweight allocation. Gold has performed quite well this year. However, we believe its role as a portfolio diversifier will be increasingly important during the expected bouts of equity market volatility. The outlook for lower US interest rates, a still-weak US dollar and strong central bank demand are also likely supportive factors.
Opportunistic ideas
We are adding 4 opportunistic buy ideas this month. In the fixed income space, we are adding a long 20-year US government bond idea to take advantage of a kink in the yield curve, whereby the 20-year bond offers significantly more value than the 10-year bond. We are also adding a global convertible bond buy idea. This asset class still offers reasonable value and usually performs well after the first US rate cut when the economy experiences a soft landing. We are also seeing signs that asset class outflows are easing.
On the equity side, we are proposing US and Europe healthcare buy ideas. The sector generally has more stable earnings. In an environment where we expect increased equity market volatility, we see this as a valuable attribute.
Foundation asset allocation models
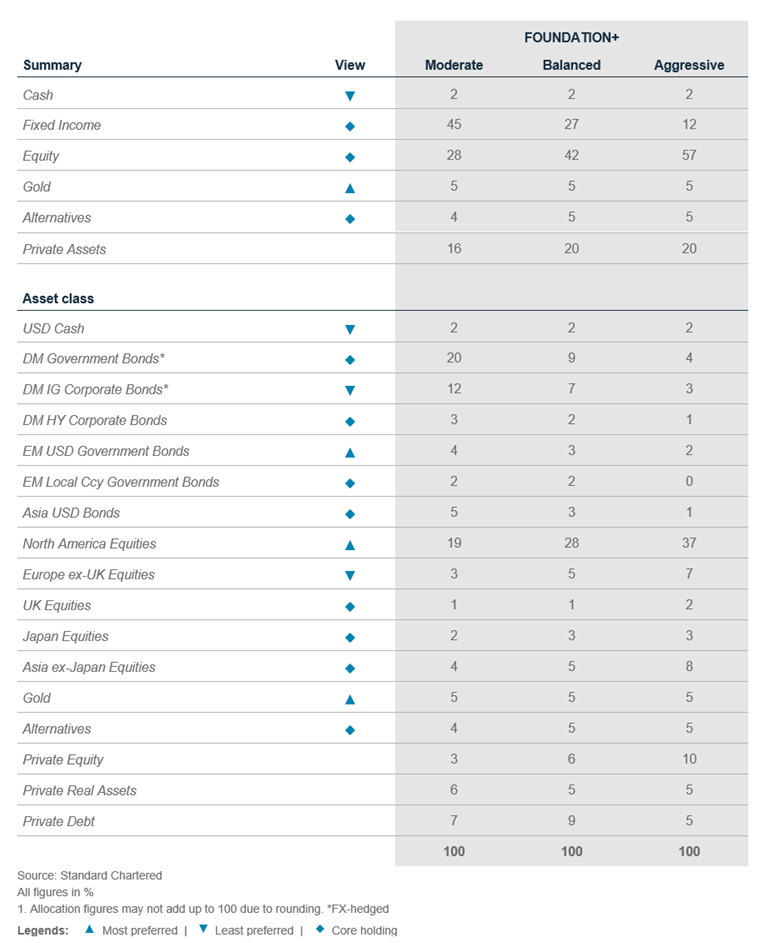
The Foundation and Foundation+ models are allocations that you can use as the starting point for building a diversified investment portfolio. The Foundation model showcases a set of allocations focusing on traditional asset classes that are accessible to most investors, while the Foundation+ model includes allocations to private assets that may be accessible to investors in some jurisdictions, but not others.
Fig. 3 Foundation asset allocation for a balanced risk profile
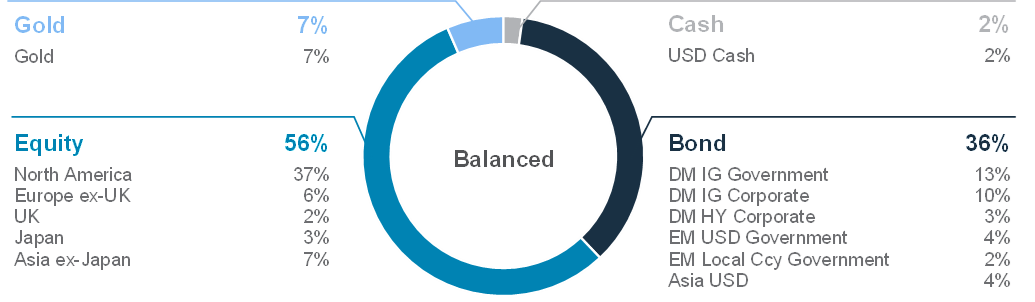
Fig. 4 Foundation+ asset allocation for a balanced risk profile
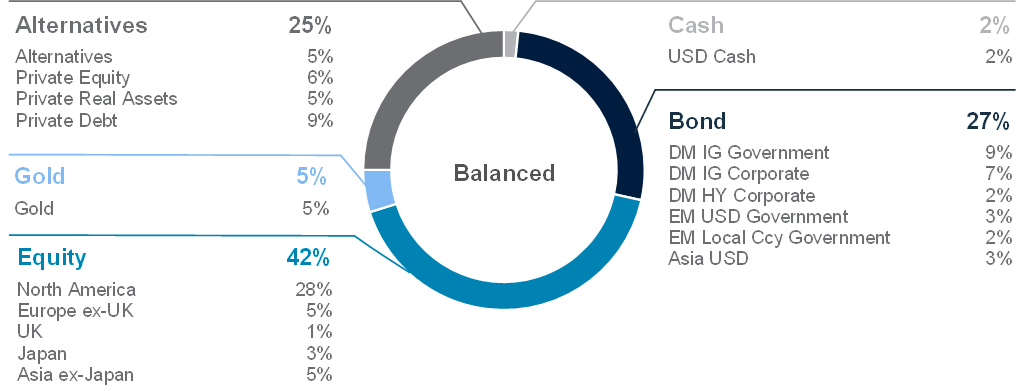
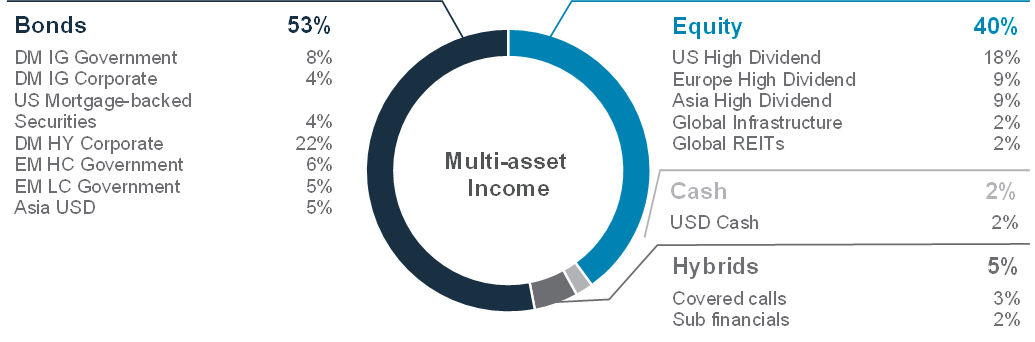
Fig. 5 Multi-asset income allocation for a moderate risk profile
Foundation: Our tactical asset allocation views
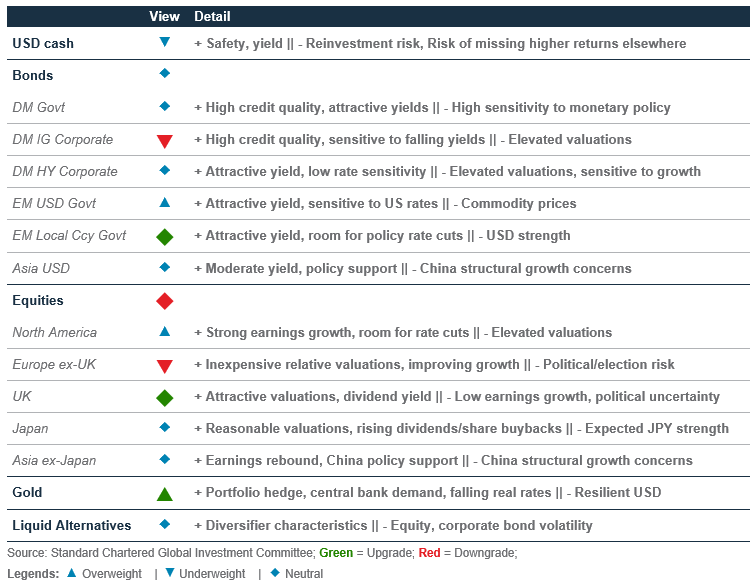
Fig. 6 Performance of our Foundation Allocations*
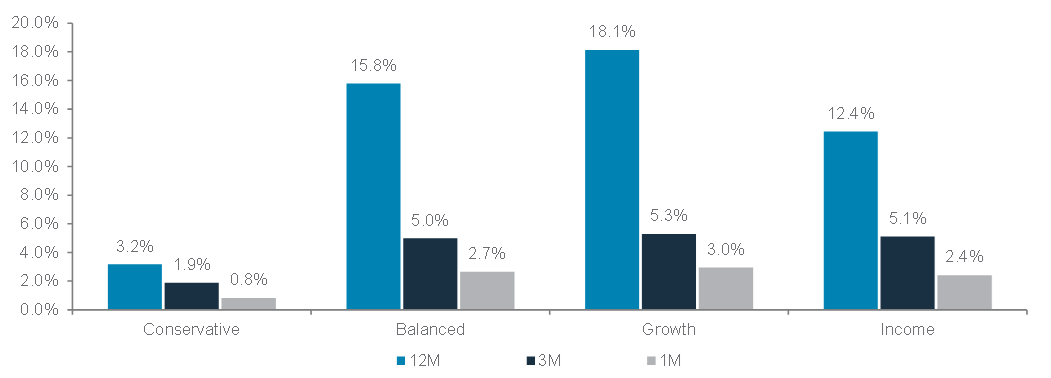
*12-month performance data from 29 August 2023 to 29 August 2024, 3-month performance from 29 May 2024 to 29 August 2024, 1-month performance from 29 July 2024 to 29 August 2024.
Perspectives on key client questions
|
|
||||
How to position ahead of a Fed easing cycle?
Global equities have had a rollercoaster ride in August. Despite a sizeable pullback and a subsequent rebound, investors who just stayed invested over the month still experienced relatively flat returns. While the debate continues between a potential soft landing or a recession in the US, one thing is clear: the Fed is poised to begin its rate-cutting cycle in September. “The time has come to cut rates,” said Fed Chair Jerome Powell at the recent Jackson Hole summit. As an easing cycle approaches, we look to history for insights on how major assets performed in the lead up to easing cycles and explore how investors can best position their portfolios to capitalise on this shift.
Bonds – historically a consistent performer; but cuts well-priced currently
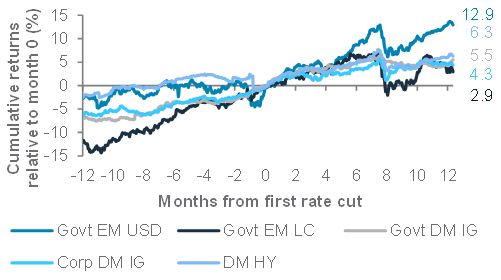
Developed Market (DM) quality bonds have historically generated the most positive returns during past easing cycles. In fact, in the majority of past easing cycles, most bond asset classes, including Emerging Market (EM) bonds and DM High Yield (HY) bonds, generated positive returns 6-7 months after the first rate cut before paths started to diverge as more apparent growth slowdown risks weighed on riskier bonds later in the easing cycles.
During episodes of soft landings in 1987, 1995 and 1998 (where there were no more than 3 rate cuts delivered), bonds also performed well, with riskier bonds such as EM USD and DM HY bonds in particular benefitting from US economic resilience. High quality bonds can also perform well in soft landing episodes, although in the 1998 cycle, gains in high quality bonds did pause as the cycle continued with little sign of further economic deterioration.
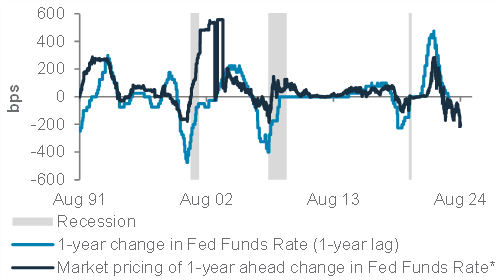
This time, market expectations for easing are significantly higher (by about 140bps) than they were ahead of past rate cutting cycles. Even if a soft landing occurs, as we anticipate, this could result in more limited gains in bonds relative to past cycles. Based on the current level of rate cut expectations one year out, the only comparable historical episode was during the Global Financial Crisis (GFC) easing cycle, when markets were pricing in as much as 185bps of cuts in response to the global downturn. For the Fed to surpass market expectations, growth will likely need to deteriorate much more significantly from here.
Fig. 7 Market pricing of rate cuts is aggressive by historical standards; Quality bonds performed consistently well during past easing cycles
Rate cut priced by markets vs actual cuts (1yr lag)
Performance 12 months before and after first Fed rate cut
Source: Bloomberg, Standard Chartered. *Generic 13th Fed Fund – Generic 1st Fed Fund
Despite this backdrop, there remains value in maintaining some bond exposure, especially to high quality bonds, given reasonably attractive yields and not-insignificant risks of a hard landing, which can result in much lower bond yields (and, hence, higher bond prices) from today’s levels. Therefore, while a recession is not our base case over the next 12 months, we maintain a core allocation to bonds.
Equities – Mixed performance. Positive in early easing
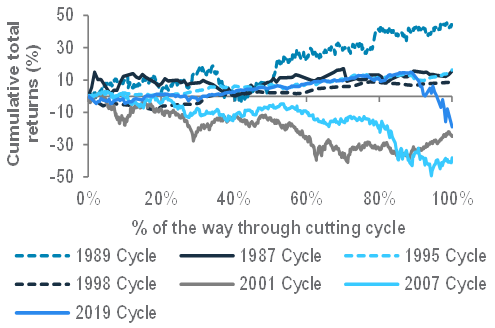
Equities generally perform well at the onset of rate-cutting cycles, according to historical data. On average, equities have gained about 9.5% in the 12 months preceding the first Fed cut, similar to what we have seen recently. Performance following the first cut is typically positive, although around 30-40% into the easing cycle, US equity returns start to become more mixed as the market contemplates both soft landing and recession scenarios.
Fig. 8 US equities* typically perform well prior to rate cuts; performance mixed post first cuts
US equities performance around Fed easing cycles
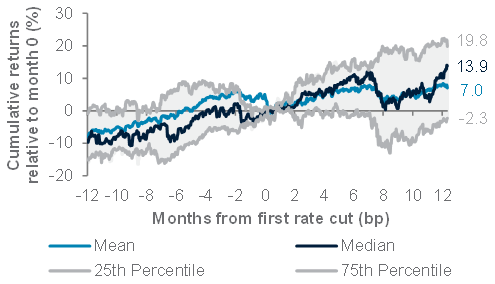
During past soft landing/Fed easing episodes in 1987, 1995 and 1998, US equities typically showed mixed performance leading into the first cuts. However, gains strengthened thereafter, roughly 30-40% through an easing cycle.
Fig. 9 Soft landings* positive for US equities
Bloomberg story count of trade tariffs
*Soft landing episodes – Oct 87, Jul 95, Sept 98
USD typically weakens into Fed cuts, but gains later
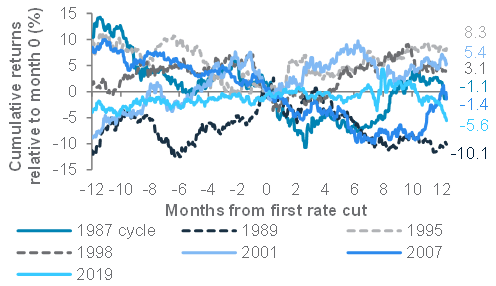
In FX, the US dollar (USD) typically weakens ahead of the first Fed rate cut. Among major currencies, the Japanese yen (JPY), Swiss franc (CHF), and Australian dollar (AUD) tend to strengthen modestly after the start of the Fed easing cycle. After its initial weakness, the USD generally traded within a range during the middle of the easing cycle before finding support as a safe-haven asset later in the cycle.
Focusing on past soft landing easing episodes, the US Dollar Index (DXY) tended to weaken in the months leading up to rate cuts, with some continued weakness after the first cut. However, 3-5 months after the first cut, the dollar typically began to strengthen again. A soft landing for the US has generally been supportive of the USD.
Fig. 10 USD tends to weaken into rate cutting cycles
USD (DXY Index) performance around rate cut cycles
*Soft landing episodes – Oct 87, Jul 95, Sept 98
Gold performs well early in the easing cycle
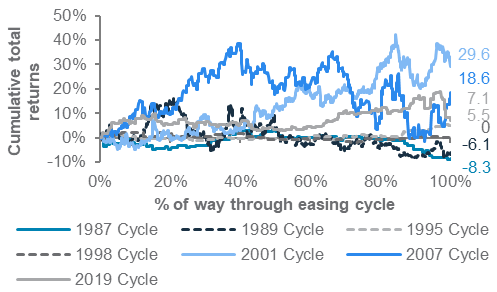
Gold historically performed well in the months leading up to rate cuts and early in the easing cycle, with particularly strong performance during episodes outside of soft landings. Historical data suggests that being long gold early in the easing cycle can be beneficial, although the performance tended to be more mixed in the middle of easing cycles.
Fig. 11 Gold generally positive during easing cycles, with stronger performance outside of soft landing episodes
Gold performance during easing cycles
Macro overview – at a glance
Our macroeconomic outlook and key questions
|
Key themes
Fed rate cuts to start in September: The US job market is slowing and manufacturing is contracting. Although service sector activity and consumption remain robust, forward-looking measures point to slowing labour demand, even as immigration sustains labour supply. While we continue to monitor hard landing risks, we believe cooling inflation will enable the Fed to guide the economy to a soft landing as it is likely to cut rates by 75bps this year, starting in September.
ECB to ease policy further, BoJ to tighten: Euro area growth expectations are tipping over after last year’s upturn. Manufacturing remains in contraction and monetary and fiscal policies tight. We expect the ECB to cut rates by 50bps more this year as inflation cools. In contrast, the BoJ is likely to continue tightening policy modestly amid rising wages.
China policy easing to continue: China’s economy has slowed in recent months after an upturn in H1. Money supply growth slumped to a record low of 6.3% y/y in July, underscoring deflationary pressures as property prices continue to fall. We expect authorities to ease policy gradually to support growth, although a large-scale stimulus remains unlikely.
Key chart
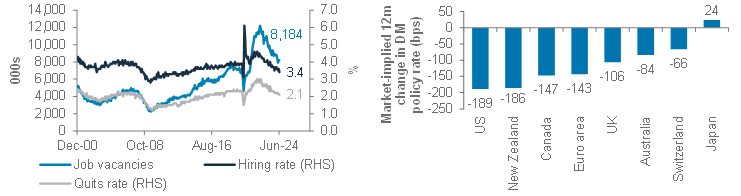
We expect the Fed to cut rates by 75bps this year as it shifts its focus towards supporting growth and employment as inflation cools. Other major central banks are also likely to cut rates pre-emptively to avoid a recession
Fig. 12 US job market is slowing; Fed seen cutting most in 12m among major banks
US job vacancies, hiring rate and quits rate; Money market-implied 12m policy rate change
The case for and against a US soft landing
“The time has come” to cut interest rates, said Fed Chair Powell at the recent Jackson Hole summit. We summarise the case for and against whether the US economy can achieve a soft landing as the Fed pivots towards supporting growth:
The case for a soft landing (our view: 65% probability):
Fed has ample capacity to ease policy. A Fed policy rate at a 23-year high and inflation that is almost 250bps below the policy rate allow the Fed to cut rates substantially, if needed.
Strong job market to sustain consumption. An unemployment rate of 4.3% is just above the Fed’s long-run rate (4.2%). The recent rise from cyclical lows was primarily due to increased worker supply. Job creation in cyclical sectors (eg, construction) is still robust.
Corporate sector healthy. Large corporates’ balance sheets remain robust, with borrowing costs still contained given past borrowings at rock-bottom rates during the pandemic. This bodes well for jobs and investment spending.
Productivity boost from AI, automation, green spending.
Disinflation easing cost pressures. Easing labour market shortages have lowered costs and wage pressures.
The case for a hard landing (our view: 20% probability):
Fed behind the curve. Fed policy and bank lending standards have been too tight for too long, hurting rate-sensitive sectors such as small businesses. This means the economy can slow and unemployment can rise even if the Fed starts easing now.
Job market cracking, clouding consumption outlook. The rise in the unemployment rate and jobless claims from cyclical lows has triggered historical recession indicators. Forward-looking measures such as the permanent jobless rate and the hiring rate point to deteriorating labour demand and, therefore, weaker consumption ahead.
Manufacturing contracting; construction at risk. A relapsein new orders points to a business cycle downturn. The rise in home inventory portends a construction slump.
Risk of another inflation flare-up. Fed easing amid loose financial conditions, rising fiscal deficits and potentially higher tariffs may cause an inflation rebound, and a halt to rate cuts.
Asset Classes
Bonds – at a glance
|
|
||||
Key themes
We are Neutral both government and corporate/EM bonds. We view Developed Market (DM) Investment Grade (IG) government bonds as a core holding (Neutral) amid softer DM growth and employment data. In our view, US election uncertainty and a lingering risk of hard landing could move yields lower. Thus, we move our 3-month target of the US 10-year bond yield lower to 3.75-4.00%.
Although rate cuts provide the prospect of capital gains on bonds, we believe picking where one takes this exposure to rate-sensitive bonds is key. We therefore maintain an Overweight allocation on Emerging Market USD government bonds, where we see attractive relative value compared with DM peers in addition to sensitivity to falling yields. To balance this, we move DM IG corporate bonds holdings to Underweight, especially given the currently tight yield premiums.
Meanwhile, we continue to view DM High Yield (HY) corporate bonds as a core holding (Neutral) for their solid fundamentals and likely performance in a soft-landing scenario. We raise EM local currency government bonds to a core holding (Neutral) as they offer decent carry amid stable EM currencies, as we anticipate the USD to weaken only modestly in the next 6-12 months. Additionally, Asia USD bonds remain a core holding (Neutral) and we now hold a balanced view on IG versus HY bonds.
Key chart
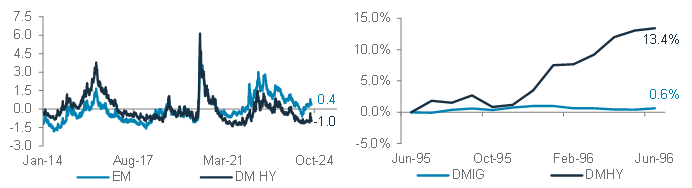
EM USD government bonds offer an attractive relative value when compared with DM peers; DM HY corporate bonds have outperformed DM IG peers in the last soft-landing episode in 1995.
Fig. 13 Relative value of EM USD government bonds is attractive; DM HY corporate bonds outperform IG bonds during soft landings, such as 1995
Mean-deviation of EM USD and DM HY bonds; US IG and US HY total return (Jul 95-Jun 96)
Add buy idea: US 20Y+ government bonds
The very long end of the US government bond yield curve has underperformed shorter tenors year-to-date. We believe they offer relative value and room to catch up as the Fed rate cut cycle kicks off. Shallower than expected rate cuts are a risk.
Add buy idea: Global convertible bonds
A soft-landing scenario is likely beneficial to risky assets, such as convertible bonds. We expect a catch-up with equity markets given their high correlation in this scenario. Technicals are also supportive, driven by higher new issue premium by Asian issuers. A hard-landing scenario is a risk.
Maintain buy: China USD bonds
We retain our tactical buy on China USD bonds, which remain supported by technical factors such as contained primary supply and strong regional demand. We are optimistic with the prospect of policy support but the extended timing is a risk.
Maintain buy: US Agency MBS
The asset class continues to offer an attractive yield pick-up over US government bonds. We expect the US housing market to stay resilient ahead of Fed rate cuts as repayment risk should be low. A hard-landing scenario is a risk.
Maintain buy: EUR government bonds
We retain our tactical buy on EUR government bonds (FX-hedged). After the first rate cut, we expect the ECB to further cut rates amid soft growth and contained inflation. Stronger than expected inflation is a risk.
Maintain buy INR bonds
We continue to see INR bonds offering an attractive yield relative to other EM bonds. While the exclusion of some bond tenors from foreign investor eligibility raised some concerns, we believe liquidity overall remains attractive, especially given expectations of a stable INR. Weaker than expected growth and capital outflows given elevated positioning are risks.
Equity – at a glance
|
|
||||
|
|
||||
Key themes
We downgrade equities to Neutral, expecting the asset class to perform in line with bonds. The Fed pivot is supportive, balanced by risks from the US elections and the slowdown in the labour market. That said, US equities remain our most preferred region, as companies continue to demonstrate solid long-term growth in earnings and the recent market shakedown creates pockets of opportunities in the growth space related to AI.
We upgrade UK equities to a core holding (Neutral), with cheap valuation, improving activity data and the catalyst of a strong and pro-business Labour government. However, it lacks growth exposure in its index composition. Japan equities remain a core holding (Neutral). The Bank of Japan is gradually normalising its rate policies, which is a headwind for equities. Its technicals also remain weak. This is offset by the structural improvement in companies’ corporate governance.
We have a core holding (Neutral) view on Asia ex-Japan equities. Within the region, we remain Overweight Indian equities, with its healthy mix of economic growth and consumption trend. Taiwan and Korea equities are core holdings (Neutral), with tailwinds from the AI theme balanced by expensive valuations versus history. China equities stay as a core holding (Neutral), with piece-meal policy support and mixed earnings. We are Neutral onshore versus offshore equities. We remain Underweight on ASEAN, which is overly defensive.
Finally, we downgrade Europe ex-UK equities to least preferred. Despite cheap valuation, there is headwind from the slowdown in growth and earnings. It is also exposed to the weakness in China and potential tariffs if Trump gets into power.
Key chart
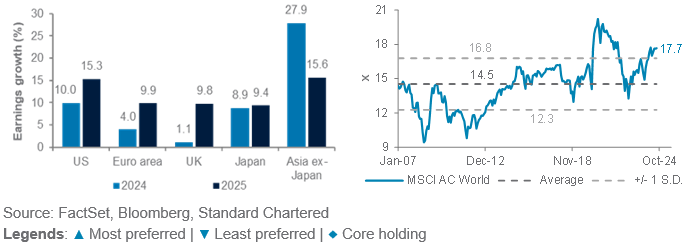
Equities supported with falling inflation and Fed pivot
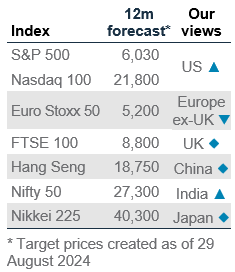
Fig. 14 US equities’ earnings growth expectations continue to be the highest among developed markets, rising further in 2025; Elevated valuations in global equities could limit the upside
Earnings growth across key regions in 2024 and 2025; MSCI AC World 12m forward P/E
US still our favourite
A strong Q2 24 US earnings season continues to justify the relatively high valuation premiums, in our view. Earnings are forecast to grow by 10% in 2024 and 15.3% 2025 – well ahead of other developed markets. There is evidence of the broadening of sector earnings as well – this is a key reason behind our Overweight view on US equities.
The risk is a sharper than expected slowdown in the US economy, with the labour market especially prompting fears of the Fed being “behind the curve”. US elections also pose the risk of volatility in US equities.
Swapping the UK and Euro area
We upgrade UK equities to a core holding (Neutral). The economy is improving and valuation is attractive, trading at 12m forward P/E of 11.7x, below its long-term average. However, the lack of technology exposure could limit the upside potential. In contrast, we downgrade Europe ex-UK equities to Underweight on the subdued economic environment and EPS growth.
Equity opportunistic views
|
Taking some profit and diversifying
- We target positive absolute returns in our opportunistic buy ideas. This month, we add the US and Europe healthcare sectors to our buy ideas.
Two new buy ideas
US healthcare: We are adding defensive exposure, as healthcare sector earnings have historically been less volatile than of the broader market. Earnings growth remains the main share price driver, in our view. This can be seen in the recent price momentum tracking growth expectations higher, given a robust drugs pipeline. Headline risks from the US election remain as healthcare costs are often a focus, but we expect this to be manageable. Adverse regulations are a risk.
Europe healthcare: This sector also offers less volatile earnings growth that has historically been positive through the economic cycle. We see strong earnings expectations driven by oncology and obesity products. Valuation remains reasonable relative to its own history, in our view. Adverse regulations are a risk.
Existing buy ideas
US technology: We believe the case remains intact for earnings growth to drive the sector higher. Investments in AI and cloud computing continue to drive growth, while upcoming interest rate cuts could spur investors to seek robust growth. Any weakness in AI spending is a risk.
US communication services: The sector also offers strong earnings momentum from digital advertising and online entertainment, driving a robust growth story. A downturn in digital advertising is a risk.
US major banks: We expect a steeper US yield curve, which is supportive of banks’ net interest income. Major US banks are also seeing growth in fee income within investment banking and capital markets. A potential Republican president could also introduce deregulation tailwinds compared with status quo. A sharp slowdown in the US economy is a risk.
China non-financial high dividend SOEs: The idea has done well, and this can continue, as the income stability is attractive amid subdued risk sentiment in China. We focus on non-financial state-owned enterprises (SOEs) given the lack of clarity on the financial sector’s support for the troubled property sector. Adverse regulatory changes are a risk.
India large cap stocks: We believe the outlook for GDP and earnings growth remains robust, supporting India large cap stocks. Stable domestic inflows would also support the equity market, in our view. A risk is weaker-than-expected growth.
Fig. 15 Opportunistic buy ideas
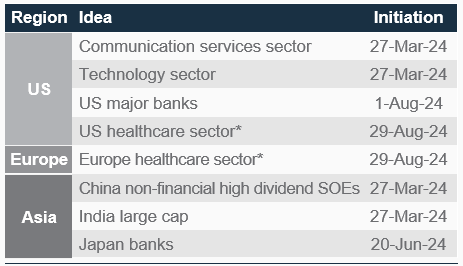
Japan banks: We retain this idea despite extreme volatility in the bank stocks in August, which we attribute to an unwinding of the JPY carry trade. We like the fundamental strength as the banks reported strong results with earnings estimates revised up, driven by higher interest rates. They continue to sell unprofitable assets to improve profitability. A reflationary environment also supports corporate profit growth and loan demand. A slowdown in Japan’s economic recovery is a risk.
Sector views: more barbell
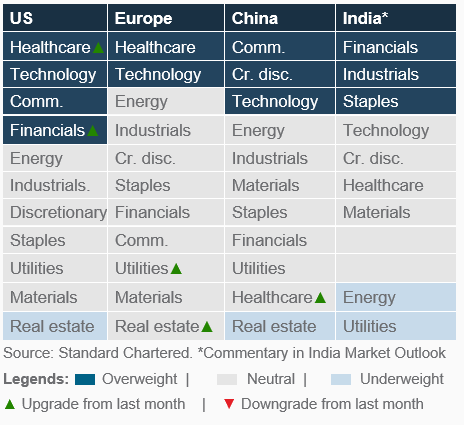
We adopt a barbell approach across the US and Europe. US healthcare is upgraded to Overweight alongside the growth sectors (technology and communication services). We also upgrade US financials to Overweight, a beneficiary of soft landing where valuation remains reasonable. We upgrade Europe utilities and real estate to Neutral as the expected rate cut support has driven strong rallies in these sectors recently.
Fig. 16 Our sector views by region
FX – at a glance
|
Key themes
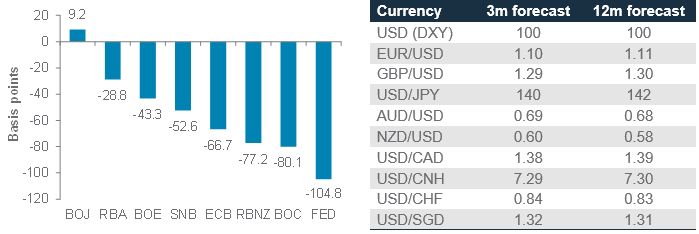
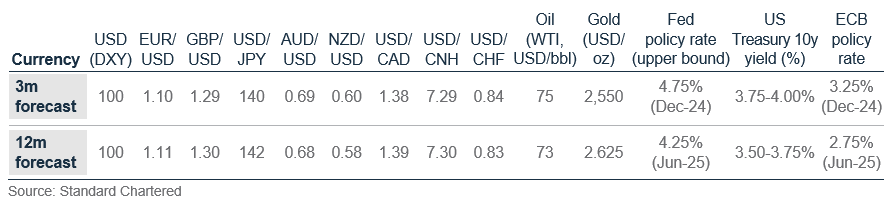
We are modestly bearish on the USD over the next 3 months. US housing and inflation data showed signs of cooling. Meanwhile, Fed Chair Powell said it is time to start interest rate cuts. We believe the Fed is set to deliver 75bps of rate cuts by the end of the year in a soft-landing scenario. While this is negative for the USD (DXY), we expect this to be balanced by safe haven demand (amid geopolitical tensions) and technicals. Therefore, we expect DXY to consolidate in the near term as these factors cap the downside. This leaves us with a 3-month forecast for the DXY Index at 100, an outcome we believe is consistent with FX markets remaining in their post-2022 range and FX volatility falling back towards its 5-year average. We see most of the central banks at a similar pace on their rate cut path in 2025. This gives us a more balanced and stabilised view on DXY with a forecast of 100 on the 12-month horizon.
Against this context, we see EUR/USD likely trading at 1.10 on a 3-month horizon as the ECB also cuts rates alongside the Fed. GBP/USD is also likely to stay resilient at 1.29 over the next 3 months, underpinned by a cautious BoE. The JPY has the most potential to strengthen further in the short term with the Bank of Japan likely to continue its rate hike policy. Any escalation in market volatility would also boost demand of the safe haven currency.
CAD and CNH weakness is likely to continue amid cooling commodity prices and moderate economic growth in China. The CHF is likely to consolidate over the next 1-3 months. The Swiss National Bank’s rate cuts make further CHF strength less likely, but a USD/CHF rebound back to the April high is likely to need more dovish SNB policy relative to the Fed, which currently appears unlikely. The AUD is expected to remain well-supported by a relatively hawkish RBA and firmer gold prices. Meanwhile, the NZD is likely exposed to more downside risk with the RBNZ turning dovish after its last rate cut.
Key chart
Fed is expected to cut rates faster than other major central banks this year, which should lead to JPY, AUD and CHF appreciating vs. the USD in the next 3 months
Fig. 17 Rate cut expectations drive USD softness
Market-implied policy rate changes until Dec 2024*; Table of forecasts
*As of 27 August 2024
Awaiting the Fed’s first move
We expect the AUD, JPY and CHF to be the biggest beneficiaries once the Fed starts rate cuts. The RBA position that policy will likely stay unchanged for an extended period creates sustained support for the AUD. We expect the JPY to continue to benefit from BoJ rate hikes and a further unwinding of the carry trade. Finally, the CHF is likely to witness stability rather than gains, with the SNB no longer actively supporting an even stronger currency. There is arguably less direct support for Asian currencies, with China’s modest recovery likely to act as a headwind for USD/CNH.
SGD shows resilience
Singapore’s monetary authority is not expected to ease policy until next year, later than the Fed. The MAS has maintained the rate of appreciation of the Singapore dollar’s nominal effective exchange rate (S$NEER) policy band since April 2024, with no change to the width of the band or the level at which it was centred. Since then, the S$NEER has continued to strengthen in the upper half of the appreciating policy band. This is likely to push USD/SGD lower, with the US dollar remaining the key driver of movements in the currency pair.
Gold, crude oil – at a glance
|
Key themes
We raise our 3- and 12-month gold forecast to USD 2,550/oz and USD 2,625/oz, respectively, led by falling interest rates. Consequently, we also upgrade the shiny metal to an Overweight relative to other major asset classes. July’s easing inflation and jobs data, coupled with Powell’s dovish signal at the Jackson Hole summit, suggest the Fed cutting cycle is on the horizon. The ensuing lower real (net-of-inflation) yields and USD weakness augur well for the metal, especially with the strengthening of the negative gold-real yield correlation. The upshot is that the recent pickup in momentum for gold ETF inflows could extend. In India, there were signs of higher consumer demand following the reduction in taxes. Meanwhile, India’s central bank continued its measured pace of gold purchases, adding to the still-robust official sector demand. Gold is now its second largest reserve asset, after surpassing the EUR recently, but there is still room for catch up to the USD which retains the largest share.
We trim our 12-month WTI oil forecast to USD 73/bbl, reflecting the weakening demand trends. The oil markets were quick to fade the geopolitical risk premium, as a string of slowing US and China economic growth data brought demand fears to the forefront. We expect global oil demand to normalise into 2025 as economic growth slows from the post-pandemic boom. We still assume that OPEC+ would start tapering production cuts in Q4, though the bloc would calibrate the pace to avoid a collapse in oil prices. On balance, our base case looks for oil prices to decline modestly in the next 12 months. In the short run, WTI oil price is likely to trade at around USD 75/bbl as demand-supply dynamics remain tight, especially after the Libya turmoil.
Key chart
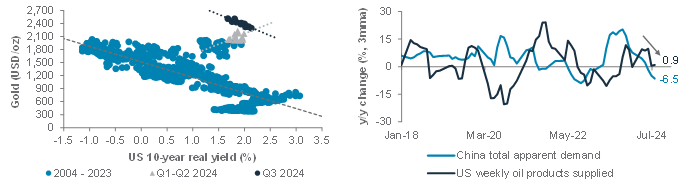
Real yields are back in the driver seat of gold prices
Global crude oil demand is unlikely to collapse, barring a hard landing
Fig. 18 Gold’s correlation with US 10-year real yield reverted to negative; US oil demand growth slowed, while China oil demand contracted y/y, in June and July
LHS chart: Gold price vs US 10-year real yield
RHS chart: US weekly product supplied, China apparent total demand
Real yields back in the driver seat
In June’s Global Market Outlook, we noted that we saw a breakdown in the negative correlation between gold and real bond yields. We also added that similar occurrences have happened in the past, with each episode lasting on average 2 months. It appears to be the case this time as well. In the latest quarter, we observed a resumption of the negative correlation between gold and real yields. In our assessment, there are two likely explanations: 1) the magnitude of decline in bond yields was large as markets priced in more rate cuts and 2) the nearing of the Fed cutting cycle and waning China demand cast the spotlight back on real yields.
With real yields back in the driver’s seat for gold, prices should rise further to a fresh record high as the expected Fed rate cuts come through over the next 12 months.
Oil demand growth slows as economy cools
Although we still see soft landing as the likely scenario, the risk of a hard landing has also risen in the past month. The oil markets are also reflecting the same story, specifically on the demand side. For one, US weekly oil products supplied, a barometer of domestic demand, slowed considerably from a near double-digit y/y growth in early Q2 to a low single-digit y/y growth in recent 2 months. In China, the demand slowdown was more pronounced on weaker petrochemical demand. Total apparent demand has flipped into contraction in the last 2 months. Correspondingly, OPEC and IEA downgraded their 2024 global oil demand forecasts. That said, for now, global oil demand is not plunging into the doldrums as we typically see in global economic downturns. The OPEC+ could also adjust its tapering plan to stave off a price collapse.
Additional perspectives
Quant perspective
Still bullish equities, but higher near-term risks
|
|
||||
Summary
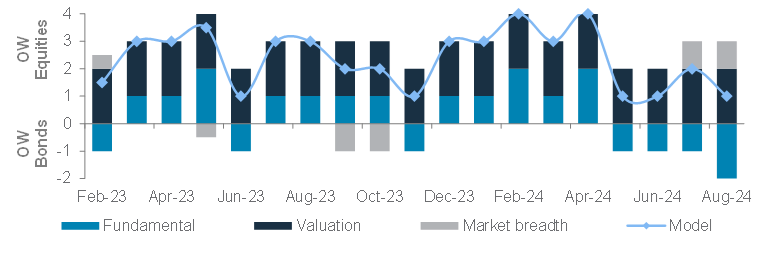
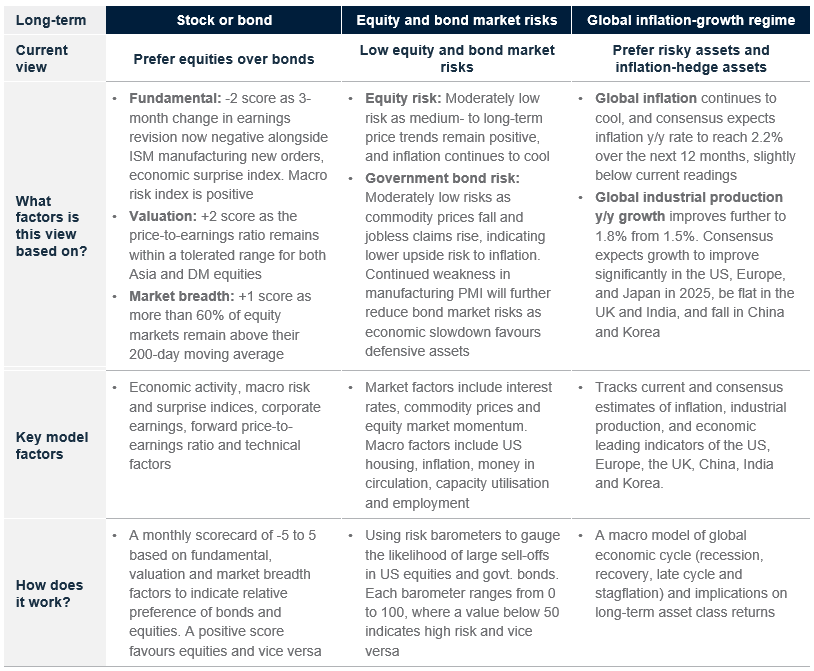
Our stock-bond model is still slightly Overweight equities, despite soft fundamentals. The model’s historical outperformance relative to a 60-40 equity-bond portfolio rose to 3.0% YTD from 2.7% last month, as global equities rebounded. However, the model has reduced the magnitude of its Overweight to equities further in August as the earnings revision turns slightly negative. Alongside other negative fundamental factors, such as the contraction in ISM manufacturing new orders and negative economic surprise index, the model score fell from +5 in May (maximum bullishness in equities) to +1 currently. Today, our valuation and market breadth factors are the only reasons that the model is still Overweight equities.
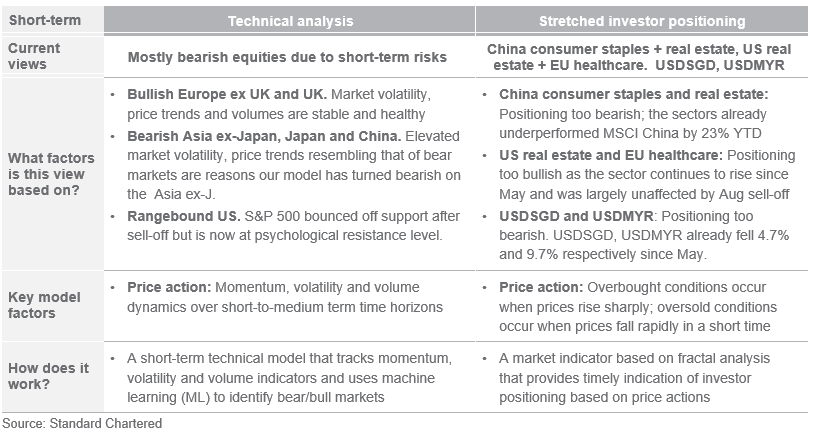
Our technical model is now bearish or rangebound equities in most regions, except for Europe ex-UK and UK equities. In the US, our model now has a rangebound outlook on the S&P500 after being bearish previously. Similarly, the model also turned bearish Asia ex-Japan equities after the August sell-off and maintains a bearish stance on Japan and China equities. This makes Europe ex-UK and UK equities the only markets where our model maintains a bullish stance given these markets have not experienced the same level of market volatility.
Our diversity indicator is flagging a high risk of reversal in China consumer staples, China real estate, US real estate and EU healthcare sectors. China consumer staples and real estate have underperformed the MSCI China Index by more than 23% YTD; this weakness may be overdone as our diversity indicator has flagged extremely bearish investor positioning in these sectors. Meanwhile, our indicator has also flagged extremely bullish investor positioning in US real estate and EU healthcare and, hence, a risk of near-term consolidation as the sector have been largely unaffected by the August sell-off and has continued to trade higher since.
Key chart
Stock-bond model’s score dropped further to +1 in August as the 3-month change in earnings revision turned negative
Fig. 19 Breakdown of stock-bond rotation model’s scores since inception in Feb 2023
Model scores as the total of fundamental, valuation and market breadth factors
Our technical model turns rangebound on the S&P500 and argues for reducing near-term exposure as the recent surge in market volatility resembles past bear markets
Fig. 20 Technical model turns neutral in the S&P500
S&P500 bounced off its support after sell-off but is now at psychological resistance level
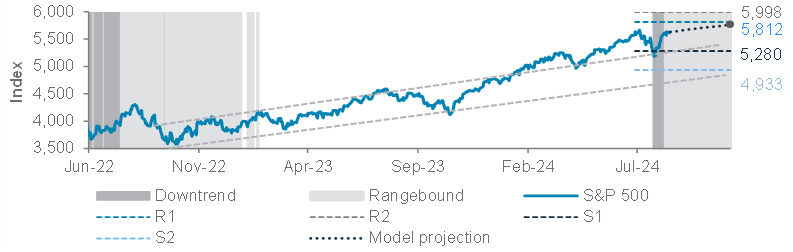
Fig. 21 Long-term quantitative models are bullish risky assets, but short-term models are more cautious
Long-term models below have a typical time horizon of 3–6 months, while short-term models have a 1–3 month horizon
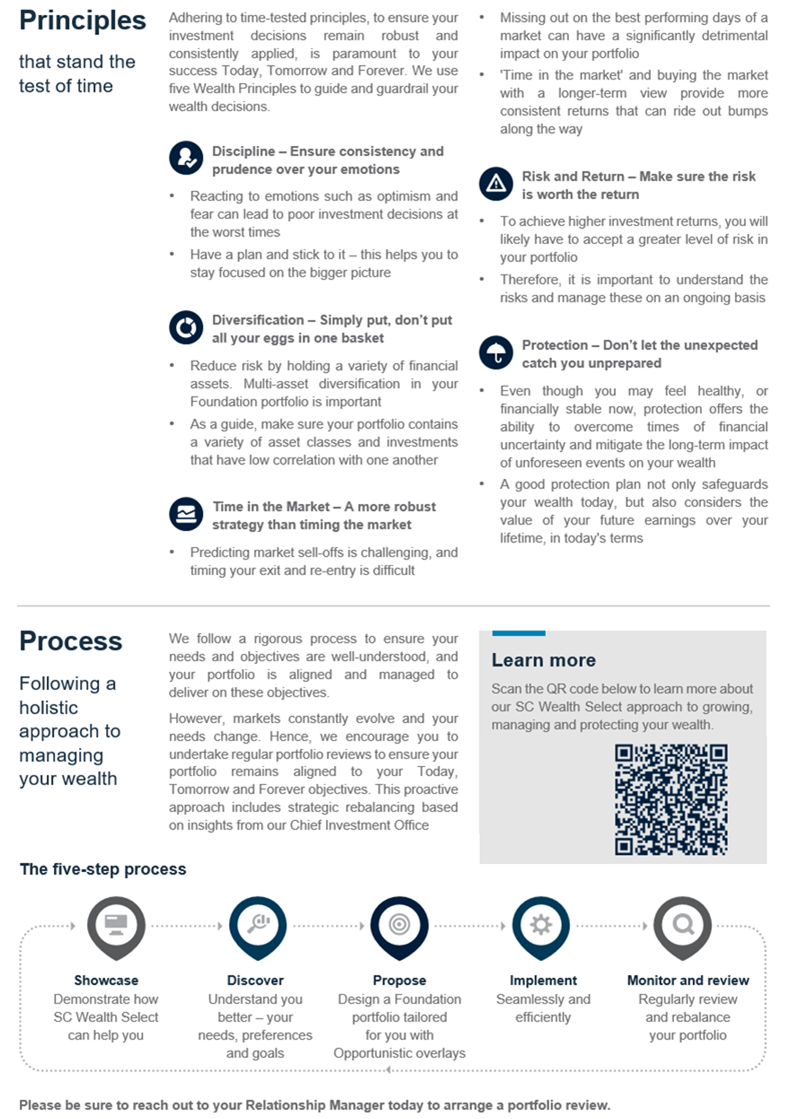
Today, Tomorrow and Forever
Performance Review
Foundation: Asset allocation summary
Foundation+: Asset allocation summary
Market performance summary
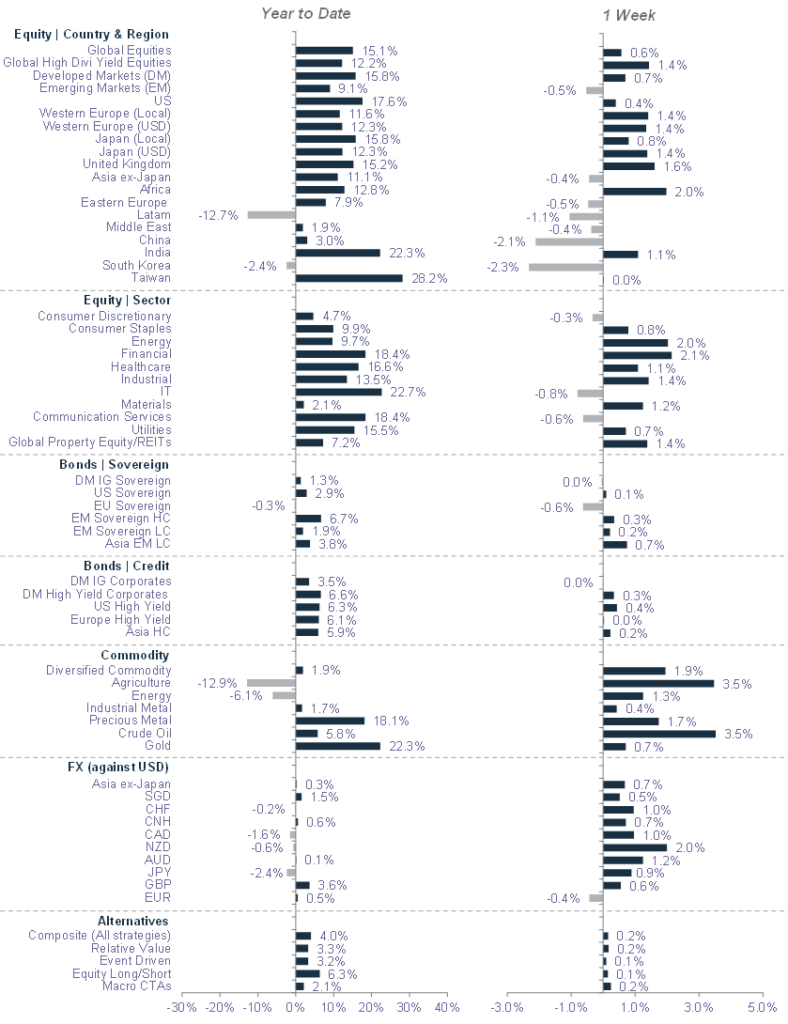
*All performance shown in USD terms, unless otherwise stated
*YTD performance data from 31 December 2023 to 29 August 2024 and 1-week performance from 22 August 2024 to 29 August 2024
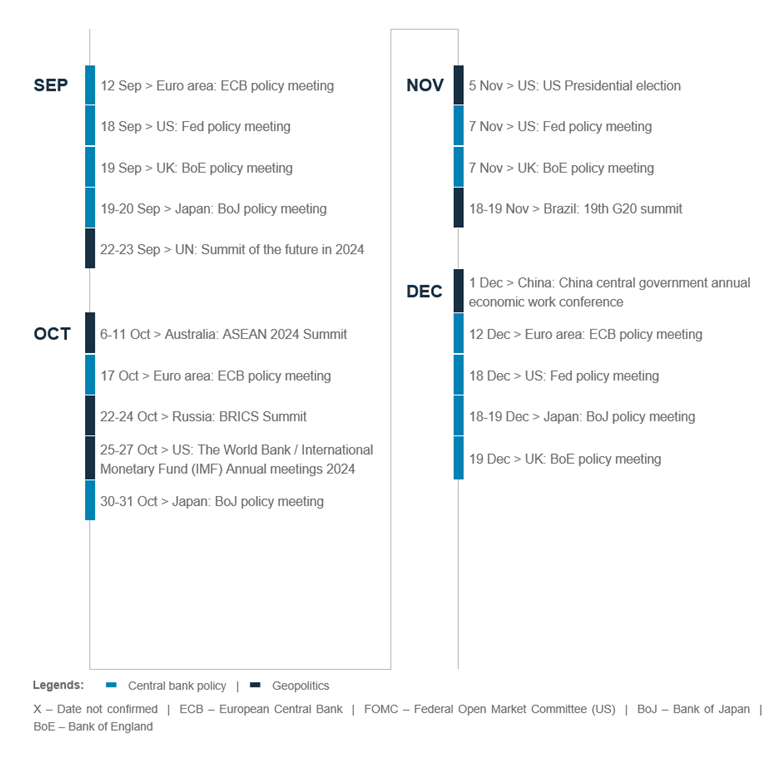
Our key forecasts and calendar events
For more CIO Office insights
Explanatory notes
1. The figures on page 4 show allocations for a moderately aggressive risk profile only – different risk profiles may produce significantly different asset allocation results. Page 4 is only an example, provided for general information only and they do not constitute investment advice, an offer, recommendation or solicitation. They do not take into account the specific investment objectives, needs or risk tolerances of a particular person or class of persons and they have not been prepared for any particular person or class of persons.
2. Contingent Convertibles are complex financial instruments and are not a suitable or appropriate investment for all investors. This document is not an offer to sell or an invitation to buy any securities or any beneficial interests therein. Contingent convertible securities are not intended to be sold and should not be sold to retail clients in the European Economic Area (EEA) (each as defined in the Policy Statement on the Restrictions on the Retail Distribution of Regulatory Capital Instruments (Feedback to CP14/23 and Final Rules) (“Policy Statement”), read together with the Product Intervention (Contingent Convertible Instruments and Mutual Society Shares) Instrument 2015 (“Instrument”, and together with the Policy Statement, the “Permanent Marketing Restrictions”), which were published by the United Kingdom’s Financial Conduct Authority in June 2015), other than in circumstances that do not give rise to a contravention of the Permanent Marketing Restrictions.
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: This document is being distributed in India by Standard Chartered in its capacity as a distributor of mutual funds and referrer of any other third party financial products. Standard Chartered does not offer any ‘Investment Advice’ as defined in the Securities and Exchange Board of India (Investment Advisers) Regulations, 2013 or otherwise. Services/products related securities business offered by Standard Charted are not intended for any person, who is a resident of any jurisdiction, the laws of which imposes prohibition on soliciting the securities business in that jurisdiction without going through the registration requirements and/or prohibit the use of any information contained in this document. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: In Jersey, Standard Chartered Global Private Bank is the Registered Business Name of the Jersey Branch of Standard Chartered Bank. The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom and all business transacted with Standard Chartered Bank, Jersey Branch and other SC Group Entity outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.