

6 November 2026
Weekly Market View
Increasing signs
of a bottom
Democrats’ thumping win in the US mid-term elections has three key implications: i) policy gridlock is back in Washington, likely stalling fiscal expansion and new tariffs; ii) the chance of a prolonged Middle East conflict is curtailed, lowering oil prices and inflation expectations; and iii) the pace of AI data-centre buildout is at risk, curbing AI-linked bond supply.
For portfolios, the election reinforces our mid-cycle playbook: remaining broadly balanced across assets, while looking for tactical opportunities.
As the S&P500 volatility index (VIX) surpasses 25, we see rising signs of equity market bottoming. We add an opportunistic idea on the US IT sector, while using volatility to earn income through structured strategies.
In bonds, we prefer the 3-7-year part of the Developed Market bond yield curve and BBB-to-BB-rated corporate bonds to earn attractive income as AI supply eases. In FX, we position for a modestly weaker USD over 6-12 months via our allocation to ex-US assets.
What are the equity market implications of the US mid-term elections?
Does emerging US jobs data alter your view on Fed rates and US bond yields?
What is your outlook for GBP after this week’s BoE meeting?
Charts of the week: Blue Wave drags oil and equities, lifts gold
Democrats’ emphatic win in the US elections should curtail President Trump’s powers to prolong the Iran conflict
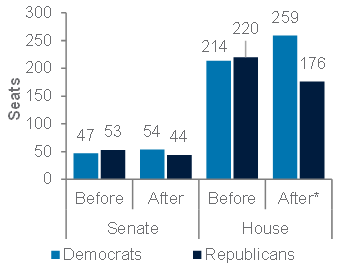
US Senate and House seats by parties, before and after the mid-term elections
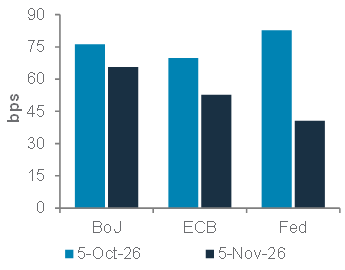
Money market expectations of key policy rate changes by Sep 2027^
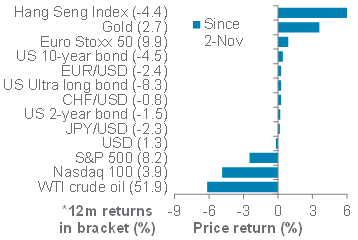
Performance of key assets since 2 November
Source: Bloomberg, Standard Chartered; *NBC News projections; ^5 November vs. 5 October
Editorial
Increasing signs of a bottom
Strategy summary: Democrats’ thumping win in the US mid-term elections has three key implications: i) policy gridlock is back in Washington, likely stalling fiscal expansion and new tariffs; ii) the chance of a prolonged Middle East conflict is curtailed, lowering oil prices and inflation expectations; and iii) the pace of AI data-centre buildout is at risk, curbing AI-linked bond supply. Higher corporate and wealth taxes are a long-term risk if Democrats win the 2028 presidential elections.
For portfolios, the election reinforces our mid-cycle playbook already in place: remaining broadly balanced across assets, while looking for tactical opportunities. As the S&P500 volatility index (VIX) surpasses 25, we see rising signs of equity market bottoming. We add an opportunistic idea on the US IT sector (see page 4), while using elevated volatility to earn income through structured strategies. In bonds, we prefer the 3-7-year part of the Developed Market bond yield curve and BBB-to-BB-rated corporate bonds to earn attractive income as AI supply eases. In FX, we position for a modestly weaker USD over 6-12 months by allocating to ex-US assets.
Policy implications: Oil fell 12% over the past week as Democrats captured the US Senate and House. The party also flipped governorships in five states – Georgia, Iowa, Nevada, Ohio and Texas – securing a majority of governorships among 50 US states for the first time since 2010. Vice President Vance and Republican leaders attributed the defeat to the Iran conflict, making it harder for President Trump to sustain it. Democrat control of the defence budget from next year further constrains conflict escalation. Despite near-term escalation risks, we see the geopolitical risk premium in oil prices fading, with oil easing towards USD 80/bbl over 6-12 months. Oil-driven disinflation should allow central banks to adopt less aggressive policies.
Adding tactical exposure to US IT sector: Semiconductors slumped this week amid concerns over data-centre moratoria, while beneficiaries of Democrat policies include defensives, affordability-related stocks, tariff rollback beneficiaries and the healthcare sector. We use the volatility to add tactical exposure to the US IT sector. As we enter mid-cycle dynamics, equities
.
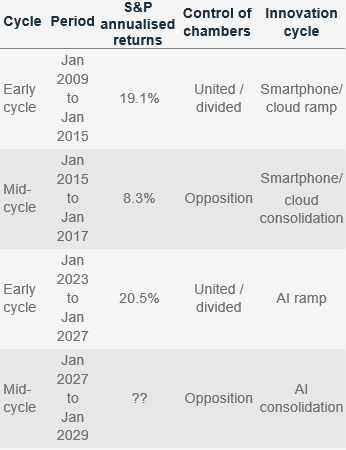
should return 8-10% annually. The 2015–2017 mid-cycle offers a useful comparison: with an opposition Congress, S&P 500 returns slowed to 8.3%, but remained positive. Diversification across sectors and regions remains a priority amid the rotation.
Prefer belly of the bond curve: Government bonds rallied on expectations of slower growth. We still expect two more Fed hikes by H1 2027, given sticky near-term inflation and a robust economy. However, cheaper oil should lower inflation towards the Fed’s 2% target next year, allowing rate cuts in H2 2027. Ultra-long yields remain elevated due to fiscal challenges. Bonds, particularly those from non-hyperscaler investment-grade corporates, offer attractive income. The 3-7-year segment – the belly of the yield curve – offers the best balance of income and sensitivity to interest-rate changes.
Credit to benefit from restrained AI supply: Since states control data centre regulations, Democrat wins in governorship races in leading data centre states, such as Texas and Georgia, means growth in this segment is likely to be restricted. Slower data-centre construction could improve credit supply-demand conditions due to reduced issuance by hyperscalers. However, some data-centre-focused deals could become less viable, warranting caution towards lower-quality issuers. High-yield credit spreads have widened, but BB- and B-rated bonds have held up, while CCC-rated debt has reached distressed levels. We prefer the BBB–BB range, spanning the boundary between investment-grade and high-yield debt, for income.
A modest headwind for the USD, tailwind for gold: The dollar should remain range-bound near term before weakening modestly over 6-12 months. Democrat control of the Congress limits tariff escalation, fiscal expansion and rapid AI buildout, three pillars of US exceptionalism supporting the USD through 2026. Disinflation should also encourage a less aggressive Fed stance, removing another source of USD support. Near-term support for the USD index (DXY) remains at 100.7. A weaker-than-expected payrolls report tonight could accelerate the USD’s decline, and vice versa. A softer dollar and sustained central-bank buying, led by China, remain supportive of gold.
— Rajat Bhattacharya
The weekly macro balance sheet
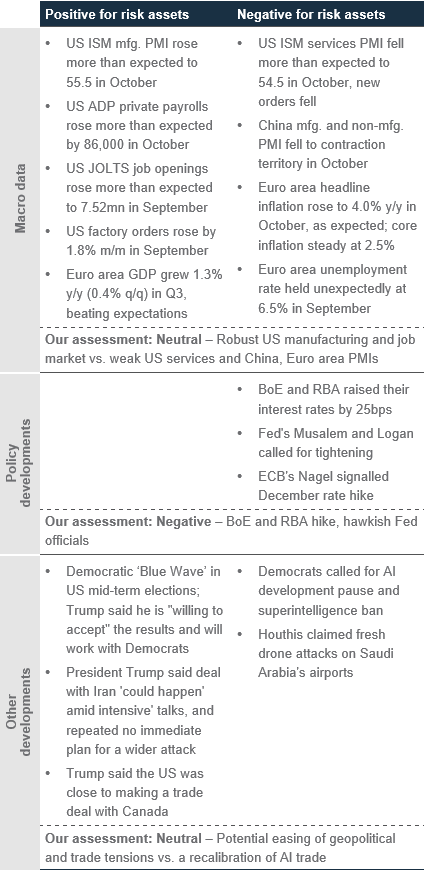
Our weekly net assessment: On balance, we see the past week’s data and policy as negative for risk assets in the near-term
(+) factors: Robust US manufacturing and job openings; Potential easing of geopolitical tensions after Democratic wave in US elections
(-)factors: Weak China PMIs; BOE, RBA hike; a recalibration of AI trade
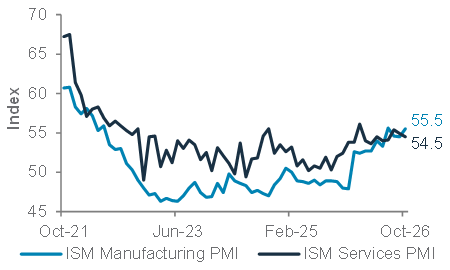
US manufacturing activity accelerated to a near four-year high, while services growth fell
ISM manufacturing PMI and services PMI
Source: Bloomberg, Standard Chartered
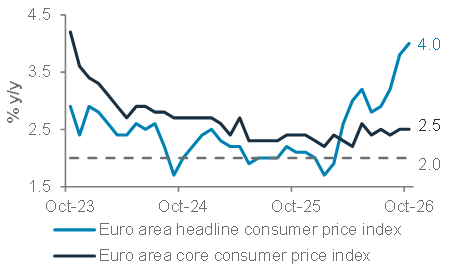
Euro area inflation rose to 4% in October, while core price pressures held steady
Euro area headline and core consumer price inflation
Source: Bloomberg, Standard Chartered
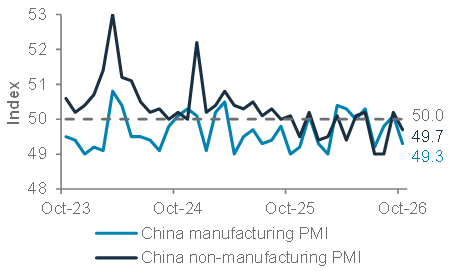
China’s factory and services activity both slipped back into contraction in October
China manufacturing and non-manufacturing PMIs
Source: Bloomberg, Standard Chartered
Top client questions
What are the equity market implications of the US mid-term election results?
Our view: The US mid-term election outcome adds political headwinds but does not alter our outlook for positive equity returns. Investors should maintain a Core allocation to global equities and continue to diversify their equity exposure across regions and sectors. We initiate an opportunistic idea on the US information technology (IT) sector, moving our opportunistic idea positioning from a defensive tilt to a more balanced positioning. Higher volatility also presents opportunities to use structured strategies for equity exposure.
Rationale: The Democrats’ victory in both chambers of Congress has supported the outperformance of themes aligned with their policy priorities, with clean energy stocks, including solar companies, among the notable beneficiaries. Affordability-related themes have also benefited, including companies that could gain from potential tariff rollbacks. Medicaid-related stocks have also risen on hopes that healthcare will gain from policy changes.
Meanwhile, semiconductor stocks remain under pressure amid concerns about potential moratoriums on data centres. Our AI capital expenditure (capex) estimates remain conservative relative to consensus, but with a potential reset in expectations around data centre spending, investors should remain selective.
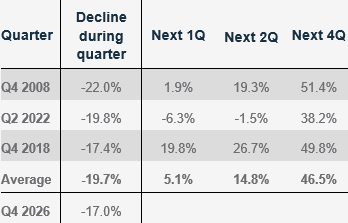
We initiate an opportunistic idea on the US IT sector after a significant 17% correction this quarter. Historically, this has been followed by strong positive returns over the next few quarters (see table). Semiconductors, about 40% of US IT, appears oversold after correcting more than 30% since we closed our opportunistic idea a month ago. Earnings growth for US IT continues to be solid, with volume driven growth in semiconductors, AI monetisation opportunities, ongoing cloud growth and resilient services revenue.
As we highlighted in our November 2026 Global Market Outlook, the transition to mid-cycle is typically characterised by greater political headwinds. The mid-term election outcome reinforces this trend. The mid-cycle experience of 2015-17 offers a useful historical parallel for returns that moderate, but remain positive. Although we trimmed global equities to a Core allocation last week, we continue to expect equities to deliver mid-to-high single-digit returns per annum during the mid-cycle, even amid political headwinds, supported by steady earnings growth in both 2027 and 2028.
Stay invested and diversify, with Overweight allocations to the US and AxJ, which offer the strongest earnings growth. Sector diversification is key as we expect market leadership to broaden. We are Overweight the US IT, US healthcare, US financial, US materials, Europe ex-UK financial and Japan financial sectors.
— Fook Hien Yap, Senior Investment Strategist
Policy uncertainty and a change in the innovation cycle is consistent with our view of a mid-cycle transition, where equity returns moderate but remain positive
Comparison of recent equity bull markets
Source: FactSet, Bloomberg, Standard Chartered
US IT sector has historically seen positive returns the next few quarters after a sharp quarterly decline
US information technology sector performance
Source: FactSet, Bloomberg, Standard Chartered
Top client questions (cont’d)
What are the key takeaways from Q3 2026 US earnings?
Our view: Q3 US earnings remain robust, but more modest earnings beats reinforce our view that equity markets are entering a mid-cycle phase. We remain Overweight US equities, but recommend investors to maintain diversified sector exposure as returns moderate and market leadership broadens.
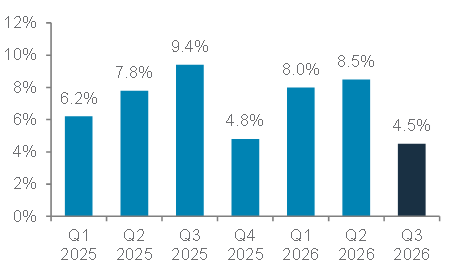
Rationale: As of 30 October, 82% of S&P500 companies that had reported had beaten earnings estimates. However, aggregate earnings were just 4.5% above expectations, a smaller beat than in recent quarters. Still, Q3 US earnings growth remains robust at 31.6% y/y, supporting expected full-year growth of 36.1% in 2026 and 16.4% in 2027 for the S&P500. The slower pace of upgrades suggests the bull market is maturing as investors focus on the sustainability of earnings growth. This raises the hurdle for positive share price reactions and makes selectivity more essential. For Big Tech, capex commitments remain high, while free cash flow is under pressure and expected to remain negative. Financing risks weigh on sentiment, particularly for companies with weaker balance sheets. We remain Overweight US equities, given the strong earnings growth, but we expect elevated volatility and modest returns. We prefer quality exposure within technology while maintaining diversified exposure across US financials, healthcare and materials.
— Ryan Goh, Investment Strategist
S&P500 Q3 2026 earnings surprises have been smaller than in previous quarters
S&P500 aggregate quarterly earnings surprise relative to consensus estimates (%)
Source: LSEG I/B/E/S, Standard Chartered
What to expect from Japanese banks’ upcoming results?
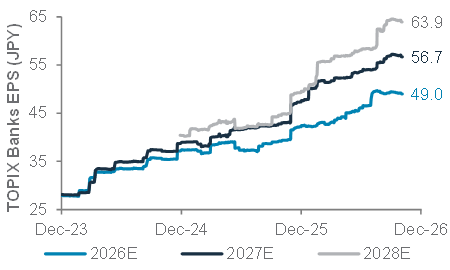
Our view: We expect Japanese banks’ earnings growth to continue over the medium term, supported by higher domestic net interest income (NII) and resilient fee income. We remain positive on the sector, favouring banks with strong deposit franchises and scope to increase shareholder returns. Investors will focus on whether full-year guidance upgrades and buybacks exceed expectations.
Rationale: The BoJ’s September rate hike to 1.25% took effect late in the quarter, so its benefit should be more visible from the December quarter as loans reprice. We expect three further BoJ rate hikes by June 2027, supporting further NII expansion. We will also look for signs that stronger corporate investment is driving faster loan growth and higher financing and advisory fees.
We prefer to place more weight on guidance upgrades driven by recurring lending and fee income than on those driven by gains on equity disposals. Continued reductions in cross-shareholdings could free up capital for additional buybacks, providing a further boost to return on equity (ROE). Key risks: faster-than-expected deposit rate repricing, rising credit costs and bond portfolio losses.
— Robin Xie, CFA, Senior Investment Strategist
Japanese banks’ earnings expectations have risen
TOPIX Banks Index consensus EPS estimates for 2026-28 (JPY)
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
What are the fundamental reasons behind your India equity upgrade? Which sectors offer favourable risk-reward?
Our View: Indian equities offer an increasingly attractive risk-reward profile. With India’s valuation premium to Emerging Markets (EMs) narrowing, foreign ownership near decade lows, Underweight EM positioning and a stabilising Indian rupee (INR), conditions are increasingly supportive of Indian equity outperformance vs. the broader AxJ region.
Rationale: We have upgraded Indian equities to Overweight within our AxJ equities allocation. While Indian markets have witnessed USD 32bn of foreign investor outflows in 2026 year-to-date, strong domestic institutional investor inflows of USD 74bn have more than offset foreign selling. These outflows and the Indian equity market’s underperformance vs. global peers reflect broader EM allocation shifts towards AI, rather than weakening Indian fundamentals. Capital has gravitated towards markets such as the US, Taiwan and South Korea, which offer direct exposure to AI beneficiaries. However, we expect market leadership to broaden, as the rapid AI buildout is increasingly debt-funded, and US mid-term election results raise uncertainty. We prefer to diversify and we see investors reallocating towards structurally strong growth markets such as India, which offer non-AI driven growth.
The RBI’s measures have supported INR stability, but underlying USD demand remains elevated. Lower oil prices would improve external balances, but the INR is likely to follow a path of gradual, controlled depreciation rather than a quick downward move. On valuation to its own historical average, the Nifty 50 one-year forward P/E is trading 18% below its long-term average while ROE at 14.7% is above historical averages. With India now marginally Underweight in large EM portfolios compared to the c.2% average Overweight historically, the case for a recovery in foreign flows is strengthening.
India’s earnings growth remains intact. The Nifty 50 clocked Q1 FY27 and Q2 FY27 profit-after-tax growth of c.20% y/y (ex-oil marketing companies). Large-caps offer greater earnings visibility and downside protection, while stronger growth in small- and mid-caps warrants a selective approach given elevated valuations.
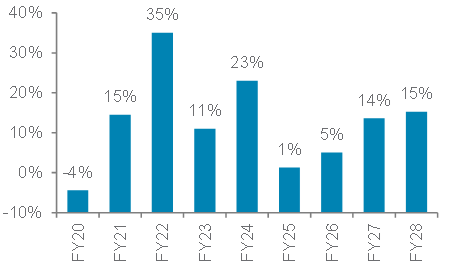
India’s growth outlook remains supported by a strengthening investment cycle, manufacturing momentum, supply chain diversification, resilient consumption and healthy corporate and banking balance sheets. Importantly, earnings growth remains robust and broad-based across the financial, metals, telecom, automobiles and other domestic sectors, with Nifty 50 earnings growth expectations of c.14-15% over 2027 vis a vis AxJ’s technology driven earnings growth of 29% in 2027.
— Shaily Gang, Chief Investment Strategist, India
Nifty 50 to deliver 14-15% earnings growth in 2027
Annual earnings growth for Nifty 50 index
Source: Bloomberg, Standard Chartered
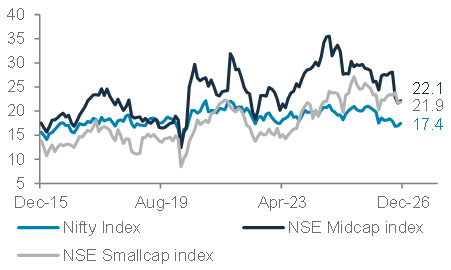
P/E valuation of Nifty 50 index appears reasonable
Consensus 12-month forward P/E for Nifty 50 (Nifty), Nifty Midcap 100 and Nifty Smallcap 100 indices
Source: Bloomberg, Standard Chartered
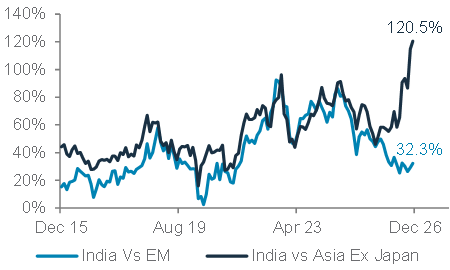
India’s P/E valuation premium to EM is at the bottom of its historical range, but the premium relative to Asia ex-Japan (AxJ) has spiked
P/E valuation premium of India vs. EM and AxJ
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
Does the emerging US job market data alter your view of the Fed’s rate path and government bond yields?
Our view: We do not expect the recent and incoming US job market data to alter our outlook unless there are significant deviations from the US economy’s current trajectory.
Rationale: The US economy continues to exhibit resilience, with the latest Job Openings and Labour Turnover Survey data showing job openings surprising to the upside at 7.5mn. Initial jobless claims remain near three-month lows. There is little evidence of a material slowdown in labour demand. Inflation is expected to trend lower through H2 2027, but the disinflationary impulse remains a medium-term story and is unlikely to manifest meaningfully in the near term.
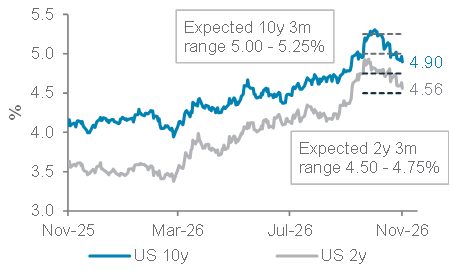
The market is now pricing in two additional 25bps hikes by H1 2027 (down from three previously), in line with our view. These two rate hikes are largely priced into the US government bond yield curve. We estimate 2- and 10-year US government bond yields to range between 4.5-4.75% and 5-5.25%, respectively, over the next three months. Our twelve-month forecast for 2- and 10-year US government bond yields are 4.25-4.5% and 4.75-5%, respectively, The2-year yield is already trading within our expected range and would only move materially higher if a significantly stronger-than-expected payrolls print led markets to price in a third hike. With two hikes baked in, long-run disinflation expectations intact and an uncertain fiscal outlook, the longer end of the yield curve is expected to be less sensitive to a single payrolls release.
— Ray Heung, Senior Investment Strategist
We expect 2- and 10-year US government bond yields to range between 4.5-4.75% and 5-5.25%, respectively, over the next three months
US 2- and 10-year government bond yields and expected range
Source: Bloomberg, Standard Chartered
What is your outlook for the GBP following the BoE’s rate hike this week? Do you see any impact on EUR/GBP?
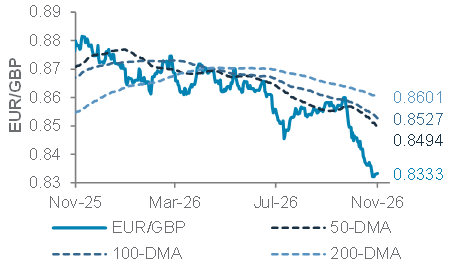
Our view: The BoE rate hike supports the GBP, but upside remains limited. We remain constructive on EUR/GBP, expecting a rebound towards 0.8450.
Rationale: The BoE hiked by 25bps to 4% as expected. The GBP was little changed, despite hawkish inflation guidance. With markets pricing only around 50bps of additional BoE tightening over the next 12 months, we see the GBP remaining vulnerable. In contrast, the ECB held its deposit rate at 2.50% in October but signalled readiness to tighten if inflation remains elevated. We expect Euro area inflation to rise further, keeping the ECB’s tightening bias alive. This suggests EUR/GBP has fallen too far relative to interest rate differentials.
Germany’s planned increase in federal debt issuance should support Euro area growth, while Moody’s decision not to downgrade France has removed an important EUR tail risk. Meanwhile, tighter UK fiscal policy is likely to weigh on domestic growth and business investment. We expect EUR/GBP to recover towards 0.8450.
— Vincent Tan, Senior Investment Strategist
— Iris Yuen, Investment Strategist
EUR/GBP is oversold; we expect a technical rebound
EUR/GBP and technicals
Source: Bloomberg, Standard Chartered
Top client questions (cont’d)
Why is the AUD underperforming despite the RBA hike?
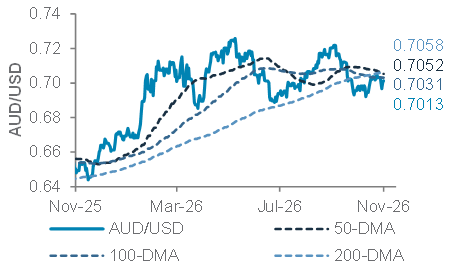
Our view: The AUD has lagged because markets had largely priced in the RBA’s November rate hike to 4.85%, and the bank gave investors less reason to expect another. Equity weakness also weighed on the currency. We remain bullish on AUD/USD and would add on pullbacks. Australia’s interest rate advantage and a sustained recovery in risk sentiment should support a move towards 0.72 in three months and 0.74 in 12 months.
Rationale: Ahead of the 3 November RBA rate decision, market pricing implied an 88% chance of a 25bps hike, leaving little scope for an upside surprise. What changed after the announcement was the pricing of the next hike. The RBA dropped its reference to further rate increases, and three members preferred a rate hold. Markets scaled back the odds of rates reaching 5.10% next year to around 30%, thus weighing on the AUD.
The AUD is sensitive to swings in global risk appetite, especially the US tech sell-off spread to global equities, triggering margin calls and weighing on the currency. An equity recovery would ease that pressure. Even after the two 25bps Fed hikes we expect by mid-2027, Australia would retain a 35bps rate advantage over the top of the Fed’s target range, supporting a gradual AUD recovery.
— Vincent Tan, Senior Investment Strategist
— Iris Yuen, Investment Strategist
We see AUD/USD upside risks on a sustained recovery in risk sentiment
AUD/USD and technical indicators
Source: Bloomberg, Standard Chartered
Market performance summary*
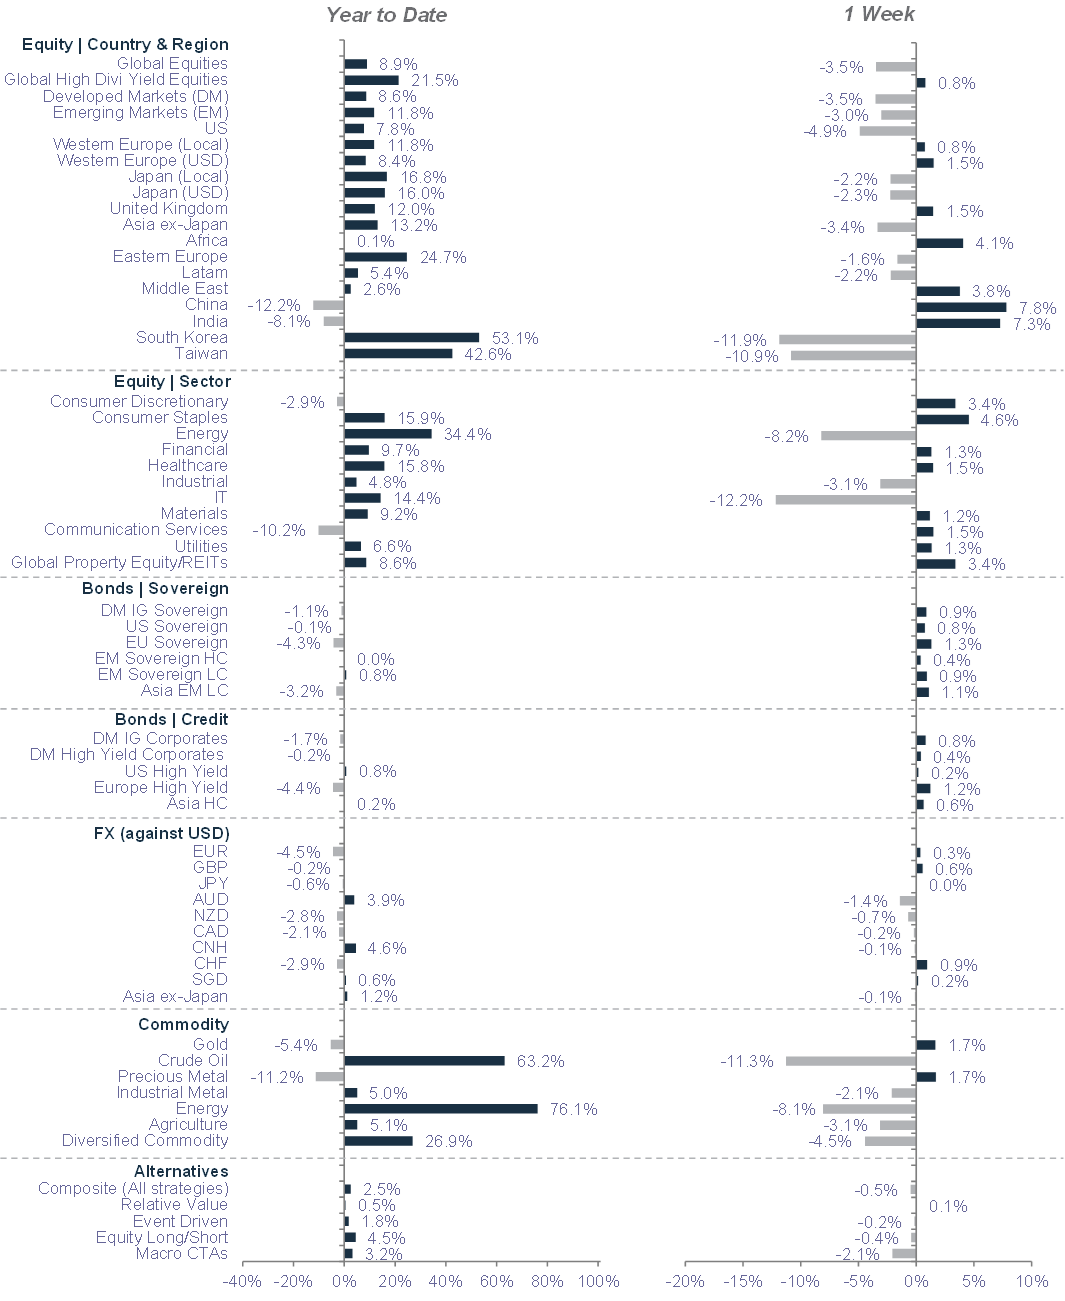
Sources: MSCI, JP Morgan, Barclays Capital, Citigroup, Dow Jones, HFRX, FTSE, Bloomberg, Standard Chartered
*Performance in USD terms unless otherwise stated, 2026 YTD performance from 31 December 2025 to 5 November 2026; 1-week period: 29 October 2026 to 5 November 2026
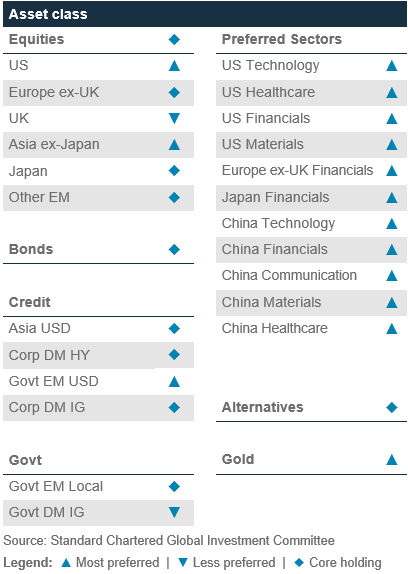
Our 12-month asset class views at a glance
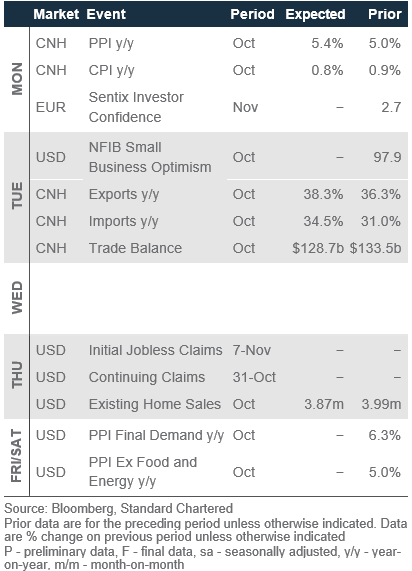
Economic and market calendar
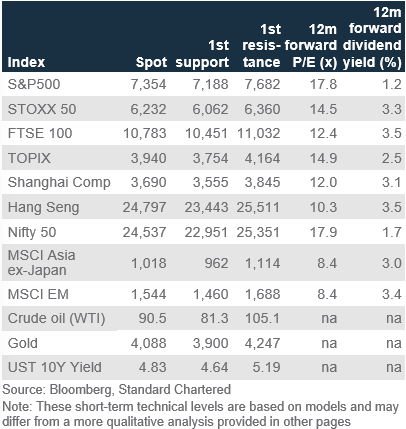
The S&P500 has next interim resistance at 7,682
Technical indicators for key markets as of 5 Nov close
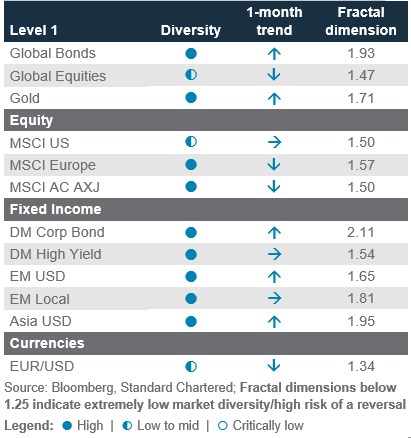
Investor diversity has normalised across asset classes
Our proprietary market diversity indicators as of 5 Nov close
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: Standard Chartered Bank, India (“Bank”) (ARN-1209) is an AMFI-registered distributor of select Mutual Funds and a referrer of certain third-party financial products. The Bank is not registered with SEBI as an Investment Adviser and does not provide investment advisory services or financial planning services as defined under the SEBI (Investment Advisers) Regulations, 2013. Any information contained herein is for informational purposes only and should not be construed as investment advice, recommendation, research report, or an offer to buy or sell any security or financial product. Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The services/products described herein are not intended for any person resident in a jurisdiction where their distribution, solicitation or use would be contrary to local laws or regulations. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom, and all business transacted with Standard Chartered Bank, Jersey Branch and other Standard Chartered Group Offices outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.