
30 October 2026
Global Market Outlook
Transitioning
to mid-cycle
We now favour a more balanced stance between stocks and bonds. Near-term event risks and high earnings expectations prompt us to trim equities to a Core holding. The US and Asia ex-Japan (AxJ) remain our preferred regions. We upgrade India to Overweight.
Higher bond yields are improving the outlook for future returns and offering increasingly attractive income opportunities. We are Overweight Emerging Market (EM) USD bonds and favour corporate over sovereign debt, but limit duration to 3-7 years.
We remain Overweight gold. Prices are likely to grind higher as near-term headwinds from higher bond yields are offset by EM central bank demand.
Where are the tactical opportunities?
Are central banks likely to continue hiking rates?
Are quantitative models still bullish on equities?
Strategy
Investment strategy and key themes
|
|
||||
|
12m Foundation Overweights:
- Gold
- US, Asia ex-Japan equities
- Emerging Market USD bonds
Opportunistic ideas – Equities
- Global: High dividend
- US: Healthcare^
- Euro area (EA): Banks, MSCI Switzerland^
- Asia: Japan banks
Top Global Sectors:
- US: Technology, healthcare^, financials, materials
- EA: Financials
- Asia: Japan financials
Opportunistic ideas – Bonds
- US: Treasury Inflation-protected Securities (TIPS), AAA-rated collateralised loan obligations (CLOs), US High-yield (HY)
- Others: AUD corporates
^New
Transitioning to mid-cycle
- We now favour a more balanced stance between stocks and bonds. Near-term event risks and high earnings expectations prompt us to trim equities to a Core holding. The US and Asia ex-Japan (AxJ) remain our preferred regions. Within AxJ, we upgrade India to Overweight.
- Higher bond yields are improving the outlook for future returns and offering increasingly attractive income opportunities. We are Overweight Emerging Market (EM) USD bonds and favour corporate over government bonds, but limit duration to 3-7 years.
- We remain Overweight gold. Prices are likely to grind higher as near-term headwinds from higher bond yields are offset by EM central bank demand.
Great expectations
Individual risk events, high earnings expectations and a higher cost of capital point to a more moderate return environment ahead. In the very near term, financial markets must navigate key event risks, such as (i) the US mid-term elections, which have historically been associated with elevated market volatility and (ii) renewed geopolitical tensions, with several reports suggesting the US is considering renewed strikes on Iran. These concerns have pushed the Brent oil price well above USD 110/bbl despite significant ongoing crude oil flows through the Strait of Hormuz.
Higher bond yields combined with high earnings expectations raise the risk of an expectations reset. The US Q3 earnings season is attracting significant attention given high earnings expectations, particularly for the AI sector. However, higher US bond yields may start to bite as debt-financed capex takes on a greater share of total capex over the coming year. This, combined with already-high expectations, raises the risk of disappointment and a near-term repricing of expected earnings growth pace.
Despite the current challenges, healthy growth continues to underpin the economic backdrop. The US economic outlook remains well supported, and the absolute level of year-ahead earnings expectations is high. We do not expect Fed rate hikes to result in overly restrictive policy. Our caution, thus, stems from the risk of an expectations repricing rather than an outright economic slowdown.
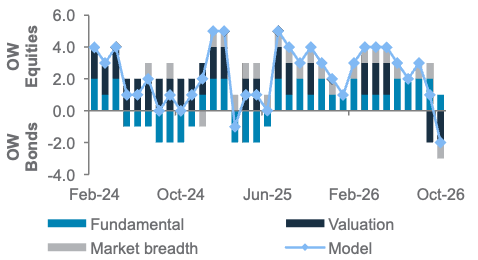
Fig. 1 Our quant model score has fallen to levels associated with flat-to-modestly-negative equity returns
Our quantitative stock-bond model
A more balanced stock-bond mix
We trim global equities to a Core holding, leaving us Neutral on both equities and bonds and Overweight gold. The concerns laid out earlier point to near-term volatility risks and a somewhat lower long-term growth trajectory for equities. Our quant model also reflects this cautious outlook, having downgraded equities to a level usually associated with flat-to-modestly-negative returns.
From a relative perspective, though, the higher yields on offer from bonds also raise the bar by presenting an increasingly compelling return outlook after several years of very low yields. We believe this argues for portfolios that are increasingly balanced between equities and bonds.
Ways to diversify equity exposure
We continue to favour global equity market diversification, with a preference for US and AxJ equities. We remain Overweight US and AxJ equities, expecting them to outperform other major regions. Earnings growth remains the main driver of this view – while growth rates could decelerate somewhat, we still expect them to remain higher than those of other major regions.
Japan and Euro area equities remain attractive as regional diversifiers. Our positive view on both markets’ financial sectors supports our Core holding view on them.
Within Asia, we are Overweight Taiwan and India. Indian equities have lagged the region this year, in part due to limited listed AI-related exposure. However, we believe this is increasingly likely to become an advantage as investors seek greater diversification away from excessive concentration in the AI theme. This comes at a time when the economic and earnings growth outlook for Indian equities is starting to improve. We retain a more Neutral view on Chinese equities amid a still-challenging growth outlook.
We also favour greater sector diversification. In the US, we favour diversifying across our Overweight sectors of technology, financials, materials and healthcare. We also favour financials in Japan and the Euro area.
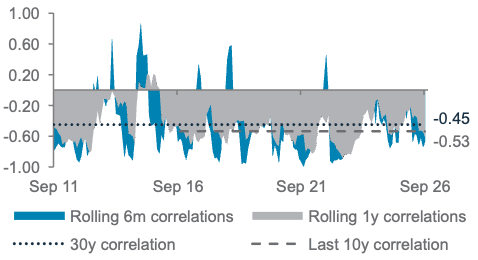
Fig. 2 Negative gold-USD correlation has held back gold amid USD strength. This is unlikely to persist
Gold and USD correlations over the last 15 years
Changes to our equity opportunistic ideas also reflect a more defensive stance. In recent weeks, we have closed our global semiconductors, MSCI Taiwan, US communication services and global power & electrification ideas and have opened new ideas on US healthcare and MSCI Switzerland.
Riding the yield train
We believe bond markets offer an attractive opportunity to lock in yields. The 10-year US government bond yield is now in a range last witnessed in 2007. While the process of rising yields results in lower bond prices – as painfully experienced in recent months – the yield level itself starts to significantly improve the outlook for future returns.
Favour corporate over government bonds, but check your duration. Still-high credit quality means that we continue to favour taking on credit risk to earn a higher yield (EM USD bonds are preferred, but we also see investment-grade (IG) and high-yield (HY) bonds as Core holdings). However, limiting duration to 3-7 years remains key to avoiding excessive exposure to any inflation surprises.
Changes to our bond opportunistic ideas also reflect a more balanced stance. We close our EU bank contingent convertible bonds (CoCos2 – please refer page 27) and US utilities corporate hybrids ideas. We also close our opportunistic idea on US 10-year government bonds following the recent pullback in yields, locking in gains.
Alternatives and gold to remain relevant
Alternatives are an effective tool for portfolio risk management. Hedge funds and private markets provide a differentiated return stream, while rotating into alternatives helps reduce equity beta exposure. We examine downside capture and how beta is reduced via hedge fund sub-strategies and private markets in our asset allocation section.
Gold remains a key Overweight. We trim our three- and 12-month forecasts modestly, but see gold forming a strong base above USD 4,000/oz. Rising bond yields and the USD were recent headwinds, but we expect a softer USD and continued EM central bank demand to result in 12-month gains.
Foundation asset allocation models
The Foundation and Foundation+ models are allocations that you can use as the starting point for building a diversified investment portfolio. The Foundation model showcases a set of allocations focusing on traditional asset classes that are accessible to most investors, while the Foundation+ model includes allocations to private assets that may be accessible to investors in some jurisdictions, but not others.
Fig. 3 Foundation asset allocation for a balanced risk profile
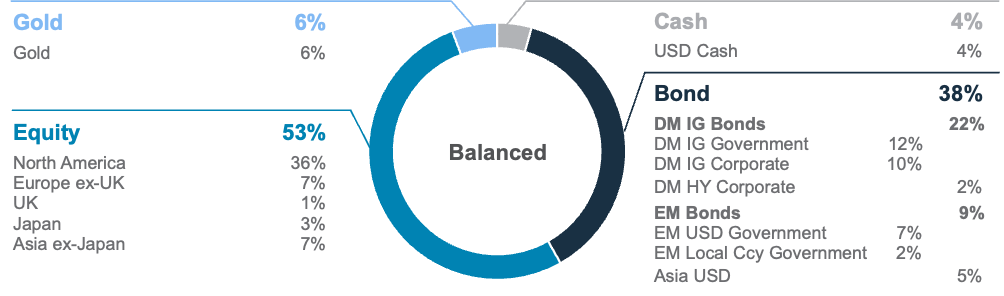
Fig. 4 Foundation+ asset allocation for a balanced risk profile
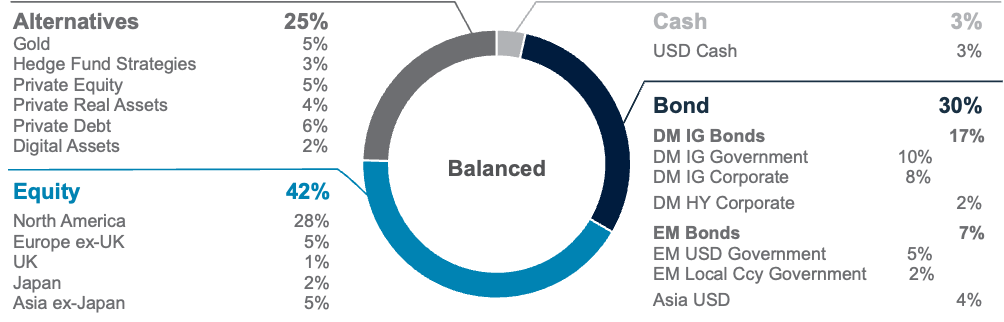
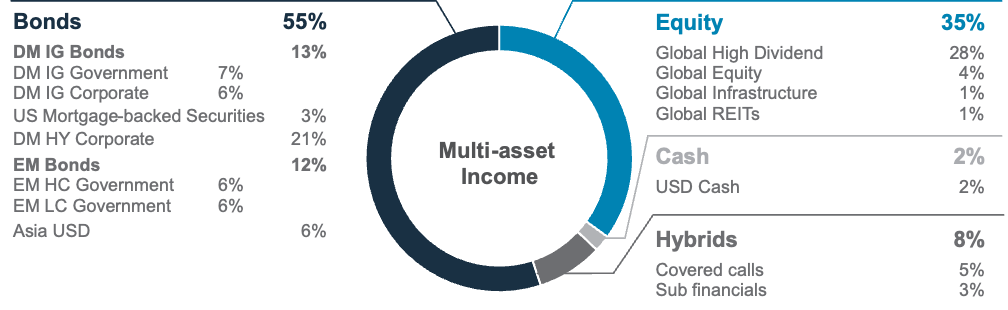
Fig. 5 Multi-asset income allocation for a moderate risk profile
Source: Standard Chartered
Notes: (i) Developed Market (DM) IG Bonds is an aggregate of DM IG Government and DM IG Corporate Bonds; (ii) EM Bonds is an aggregate of EM USD and EM Local Ccy Government Bonds
Foundation: Our tactical asset allocation views
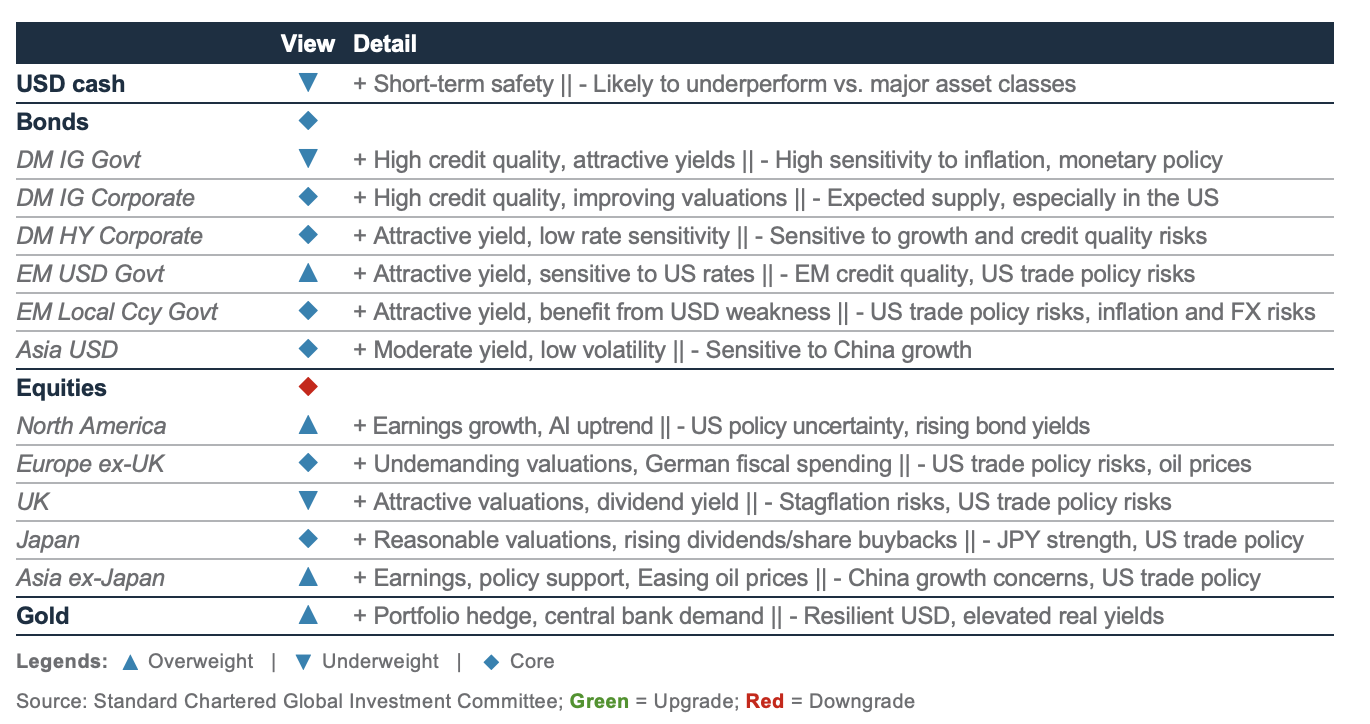
Fig. 6 Performance of our Foundation Allocations*
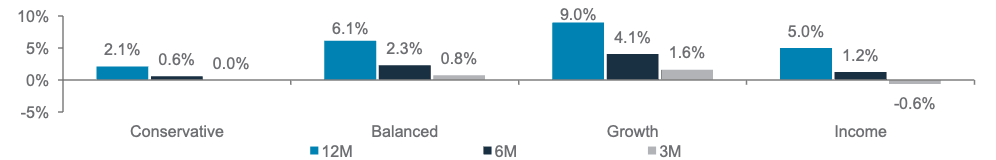
Source: Bloomberg, Standard Chartered; *12-month performance data from 28 October 2025 to 28 October 2026, Six-month performance from 28 April 2026 to 28 October 2026, Three-month performance from 28 July 2026 to 28 October 2026
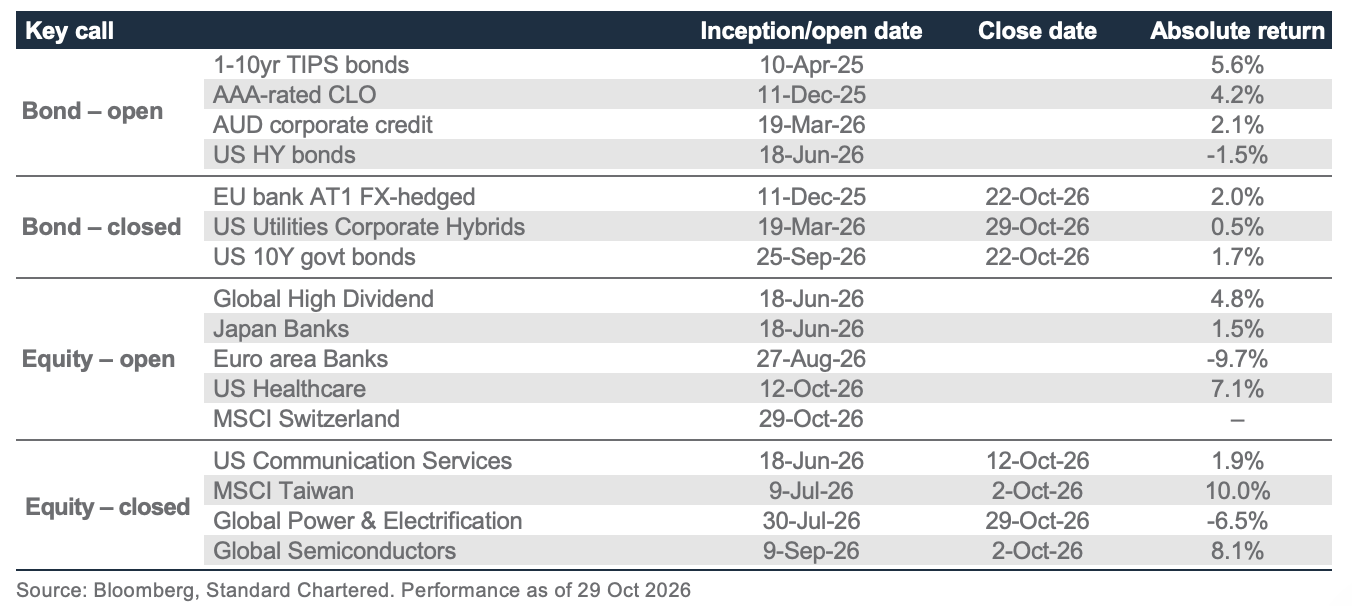
Fig. 7 Opportunistic ideas performance
Macro overview – at a glance
|
Key themes
Core scenario (soft landing, 45% probability): An economic soft landing remains our core scenario, with the global economy overcoming this year’s oil price shock thanks to a surge in AI investment in the US and Asia. Record wealth generation driven by the stock market rally is supporting US consumption. Fiscal easing in the US, Germany and Japan is supporting growth. Meanwhile, inflation has reaccelerated due to a rebound in fuel prices as the Middle East conflict drags on. Against this backdrop, the Fed, ECB and BoJ all hiked rates in the same month (in September) for the first time. Although all three subsequently paused in October, we expect the Fed to hike twice more, the ECB once more and the BoJ thrice more by June 2027. Nevertheless, we expect the energy and tariff effects on inflation to fade by H2 2027, enabling the Fed and the ECB to cut rates by Q3 2027. Meanwhile, China is likely to target credit easing and accelerate fiscal spending in H1 2027 to revive domestic growth.
Upside risk (no landing, 30% probability): We maintain the probability at 30% as AI-driven investment growth continues. There is a reasonable chance that lower oil prices next year, the AI-fuelled wealth boom and fiscal easing in Germany and Japan will boost ‘animal spirits’. A potential global defence spending boom, led by the US and Europe, could also lift global growth.
Downside risk (25% probability): We raised the risk of a recession to 15%, especially if central banks are forced to accelerate the pace of rate hikes to douse rising inflation. A stock market downturn negating the wealth effect or a bond sell-off due to fiscal concerns are other tail risks. We cut stagflation probability to 10% as we see low risk of oil prices sustaining above USD 120/bbl.
Key chart
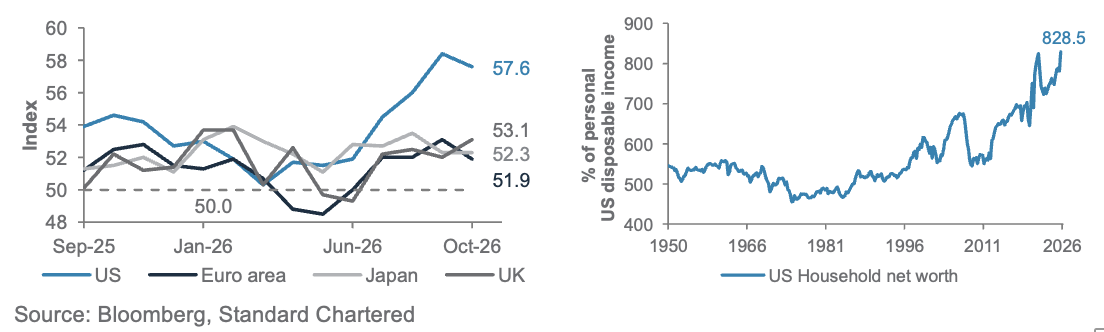
The US-led AI-focused investment boom has lifted business confidence. The resulting equity market rally has boosted US household wealth, supporting consumption
Fig. 8 Robust business confidence amid AI boom; equity rally lifts US household net worth
Purchasing managers indices; US household net worth as percentage of personal disposable income
Policy rates watch
We expect the Fed to hike twice more by Q2 2027, then ease in H2 2027, as AI-led expansion continues. The US economy remains firmly in expansion. In Q3, annualised GDP growth accelerated to 3.4%, led by AI investments and consumption. In October, the composite Purchasing Managers’ Index (PMI) remained strong at 57.6. Since our last monthly report, the consensus estimate for 2026 GDP growth has been nudged up to 2.3% from 2.1%, and the 2027 estimate has risen to 2.2%. That matches the Fed’s upgraded growth projection of 2.3% for 2026, but remains below the Fed’s 2.4% estimate for 2027. AI investment, fiscal support and household wealth are the main growth drivers, although consumer activity lags business spending. Higher bond yields and elevated oil prices are headwinds, but recession risks look contained. Our core scenario remains a ‘soft landing’, at 45%, with a meaningful 30% chance of a ‘no-landing’ upside.
Rising gasoline and diesel prices pushed US core personal consumption expenditures (PCE) inflation to 0.3% m/m and 3.1% y/y, matching estimates. Consensus sees core PCE inflation slowing from 3.2% in Q4 2026 to 2.4% by Q4 2027 as energy and tariff effects fade. Underlying price momentum is softening, and recent PCE methodology revisions have lowered core inflation. However, fuel costs passed on to wider consumers and AI-driven chip shortages remain upside risks.
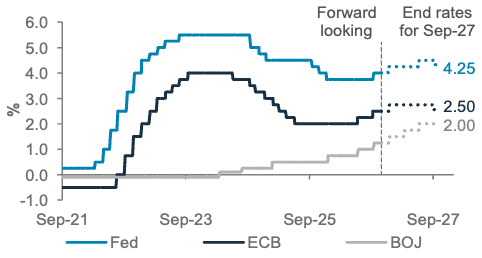
In October, the Fed held rates at 4.0%, after hiking in September for the first time since 2023. We expect the Fed to hike rates by 25bps in December and 25bps more in H1 2027 due to elevated near-term energy inflation. It is likely to follow with a 25bps cut to 4.25% in Q3 2027 as disinflation returns. This aligns with the Fed’s projected policy path, although it implies a more dovish trajectory than money markets, which are pricing another 56bps of hikes over the next 12 months. Political uncertainty after the mid-term election is a key risk.
ECB to hike once more in December, then pause. The Euro area recovery is firming. GDP grew 1.2% y/y in Q2 2026, up from 0.6% in Q1, and the manufacturing PMI stayed robust at 52.4 in October. Consensus 2026 growth has been raised to 1.0% from 0.9%, and 2027 is unchanged at 1.3%. The main supports are resilient exports and German infrastructure and defence spending. However, cautious consumers and soft private investment limit the recovery, and energy costs are squeezing household incomes and business margins. Recession is not the central expectation. French fiscal stress and sustained high energy costs remain the key risks.
Higher energy prices pushed Euro area headline inflation up to 3.8% y/y in September from 3.2% y/y in August, while core inflation rose to 2.5% y/y. Consensus expects headline and core inflation to ease to 2% y/y and 2.4% y/y by Q4 2027, respectively. Encouragingly, energy has had limited impact on core prices, and longer-term inflation expectations remain stable at around 2.1%. Together, these should allow inflation to moderate in 2027. The main risk is that energy, and especially gas, prices stay high for longer than expected.
The ECB held its deposit rate at 2.5% in October after raising it by 50bps this year. Inflation data continue to favour an additional hike in December. We expect an ECB rate hold in H1 2027, followed by a cut by Q3 2027 as disinflation returns. This policy path is more dovish than money markets, which are pricing more than 60bps of hikes over the next 12 months.
China to provide targeted support to defend growth floor. China’s growth momentum recovered in September. Both the manufacturing PMI (50.1) and the non-manufacturing PMI (50.2) moved back into expansion. The construction PMI rose above 50 for the first time this year as infrastructure spending started to take effect. Exports grew 36.3% y/y, pushing the trade surplus to a record USD 133.5bn. We expect growth in 2026 to meet the lower end of the 4.5-5.0% target. Growth is increasingly bifurcated, though, with technology firms and exporters doing well, while household demand stays weak.
Prices are rising again, but only narrowly. Consumer inflation edged up to 0.9% y/y in September, and producer inflation surged to 5% y/y, its highest since 2022, driven by energy and metals prices and concentrated in upstream sectors. With domestic demand weak and a high comparison base next year, the boost from energy prices is likely to fade in 2027.
domestic demand weak and a high comparison base next year, the boost from energy prices is likely to fade in 2027.
Policy is in ‘targeted easing’ mode. We expect a modest fiscal package to defend the growth floor rather than a large stimulus. The PBoC cut a key rate by 25bps to 1.5% to fund ‘Six Networks’ infrastructure projects and raised its relending quotas. A new interest subsidy on first-home mortgages provides limited support to demand. We expect no policy rate cut this year. There is still room to speed up fiscal spending, including by using CNY 500bn of unused local-government debt quota. If the PBoC switches to an overnight reverse repo rate as its policy rate, that would imply a de facto rate cut as the overnight rate is lower than the 7-day official policy rate.
BoJ to hike at a quarterly pace until Q2 2027. Japan’s economy remains solid. Wages are growing above 4%, and the labour market is tight. The main headwind is high energy prices, which is slowing growth. Fiscal spending gives some support: the FY27 draft budget includes ambitious spending plans, alongside a proposed two-year cut to the consumption tax on food and a new five-year defence programme. However, this extra spending raises questions about fiscal sustainability. The BoJ unveiled plans to triple the pace of ETF sales from January 2027, potentially funding the tax cut.
Price pressures now look firmly established. Headline and core inflation rose above 2% for the first time this year, and core-core inflation (ex-fresh food and energy) jumped to 2.4% and is expected to rise towards 3% in Q1 2027. Breakeven inflation rates have stayed above 2% most of this year. Real interest rates remain negative, hurting savers and pensioners.
The BoJ held its policy rate at 1.25% in October, after raising it in September, only three months after its previous hike. This points to an accelerated quarterly hiking pace. We expect the quarterly pace of hikes to continue, taking the rate to 2% by June 2027. Money markets have caught up with our hawkish view in recent months. The BoJ noted for the first time that underlying inflation has reached its 2% target, marking a shift from creating inflation to containing it. Politics could slow the hiking cycle in H2 2027. Two government-appointed board members voted against the September hike, and the two most hawkish members are due to leave in July 2027.
Fig. 9 Inflation is likely to ease globally by H2 2027
Consensus inflation estimates across major economies
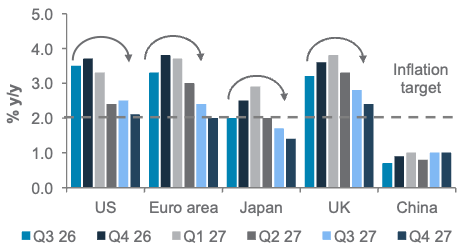
Fig. 10 We expect limited central bank hikes over 12m
Our estimates of key central bank policy rates over 12 months
Asset classes
Fixed Income – at a glance
|
|
||||
|
|
||||
Our view
Foundation: Bond yields remain near multi-year highs, offering an attractive entry point. We view fixed income as a Core holding (ie, a Neutral allocation) in our multi-asset portfolios. Within the asset class, we maintain an Overweight stance on EM USD government bonds, given their attractive risk-reward. We hold an Underweight view on Developed Market (DM) government bonds due to the tail risks associated with term premia.
The Fed’s decision to hold rates at 3.75-4.00% in October amid still-elevated energy prices suggests that every Fed meeting from here is ‘live’, with a rate change possible on incoming data. With US inflation still running hot and the labour market tight, we expect two more 25bps hikes (one by year-end and one in H1 2027), bringing the Fed’s target range for the federal funds rate to 4.25-4.5%. We continue to favour the 3-7-year part of the US government bond yield curve as the best hedge against any risk-off move driven by AI-related growth fears. As inflation pressures ease in H2 2027, we see room for the Fed to consider a rate cut, which should pull nominal yields lower. Solid corporate fundamentals and supportive technicals should keep spreads tight, but there is limited room for them to tighten further. We still favour EM USD over local-currency (LCY) government bonds.
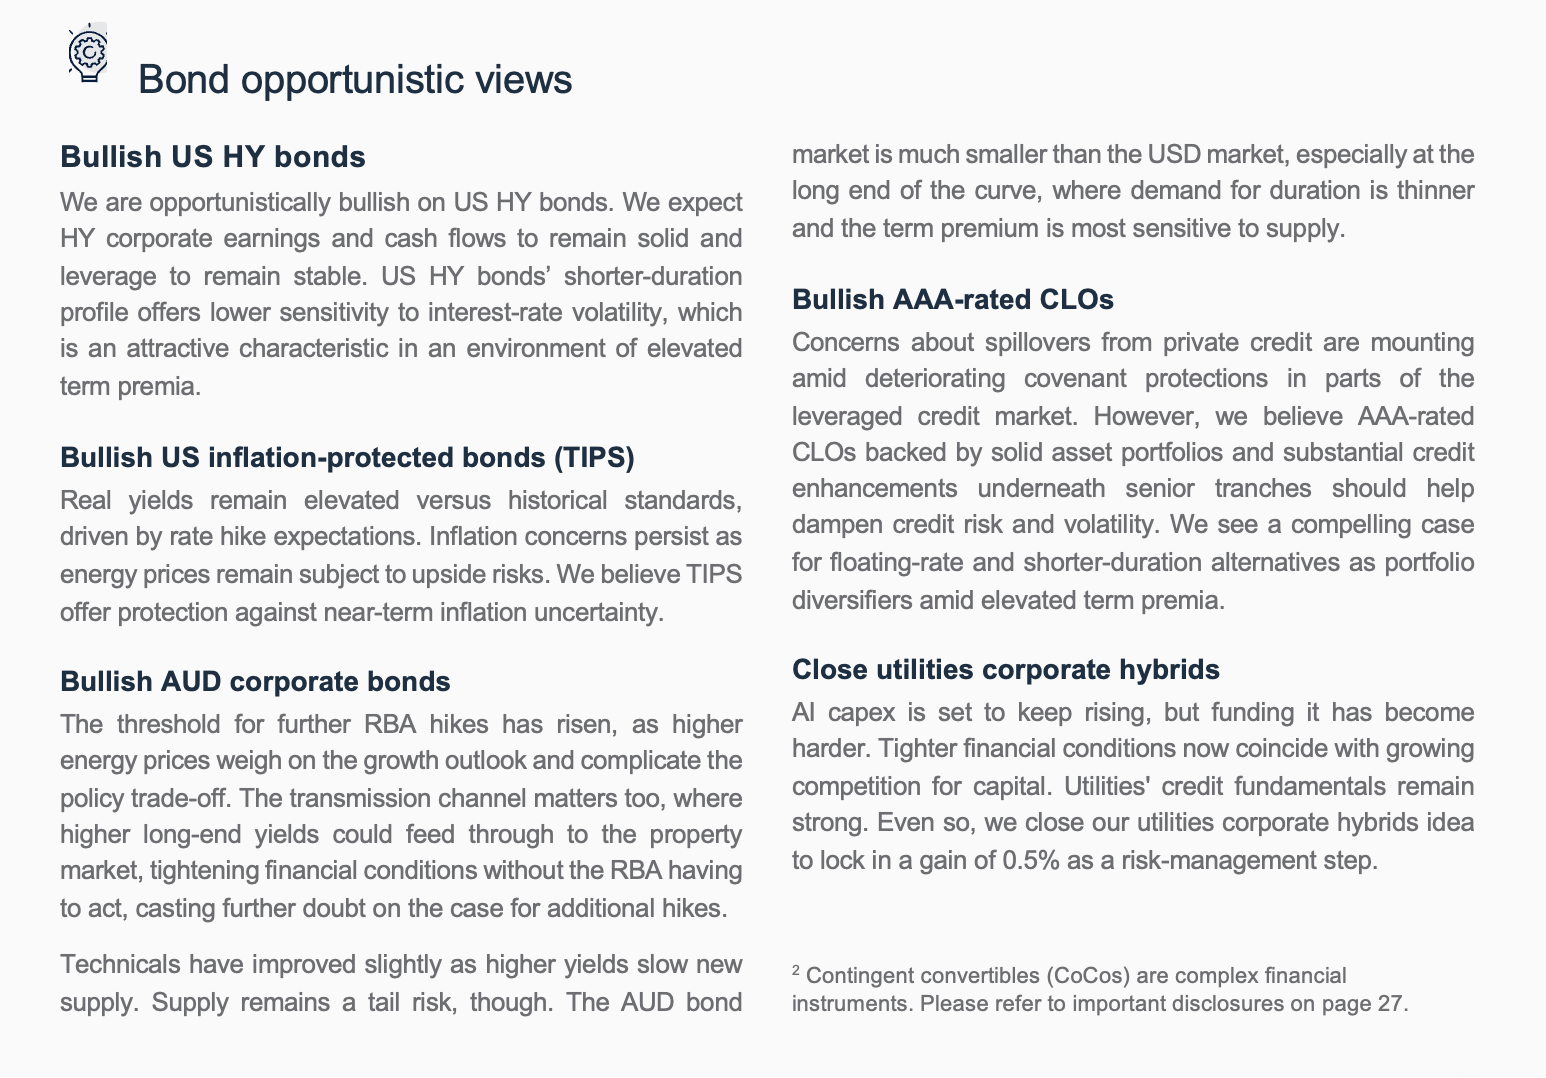
Opportunistic ideas: We are bullish on US TIPS, AAA-rated CLOs, broad US HYs and Australian dollar (AUD) corporate bonds.
Key charts
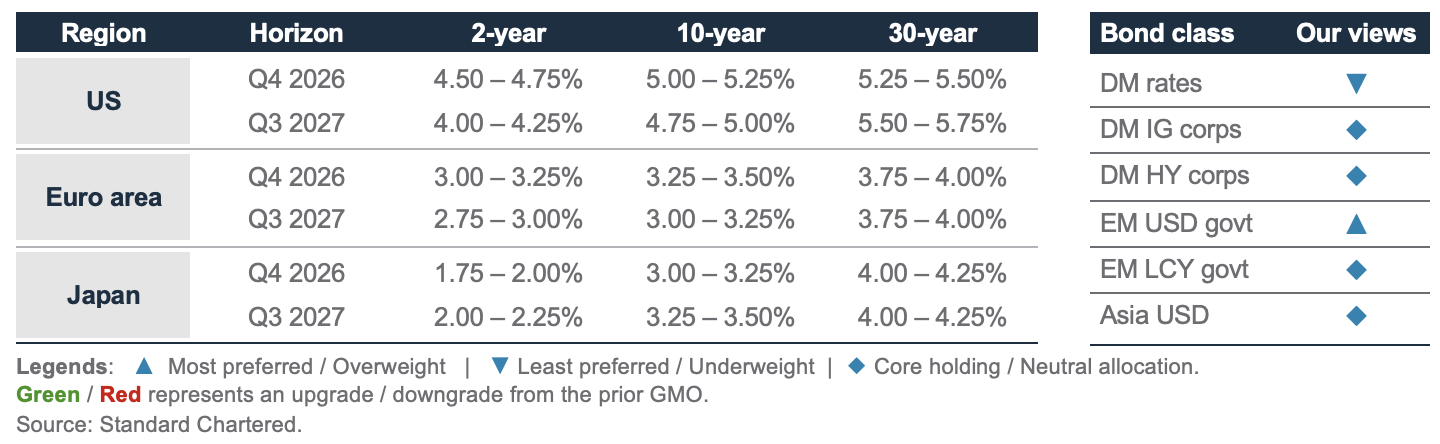
Fig. 11 Rate forecasts and our view of bond classes
DM rates – Underweight
We remain Underweight DM government bonds. In the US, government bond yields have retraced meaningfully after a sharp bear steepening through September and early October. We expect real yields to stay elevated over the next six months as AI capex and productivity growth continue to drive above-trend economic growth. We expect two more 25bps rate hikes by June 2027.
Over the next few months, we expect US government bond yields to remain rangebound. The near-term path hinges on five factors: 1) the 3 November US mid-term election, where a ‘Democratic sweep’ would likely be bond-supportive by constraining US President Trump’s fiscal spending agenda, while a ‘Republican sweep’ would likely weigh on bonds as markets price in further fiscal expansion and a higher term premium; 2) Fed communication at upcoming policy meetings;
3) the US Treasury’s quarterly refunding announcement on 4 November, where any signal of reduced long-end issuance would likely compress long-end yields; 4) softening auction demand and repatriation by foreign investors, which add uncertainty around demand for US government bonds; and 5) the fluid geopolitical situation in the Middle East, which is keeping oil prices elevated, with a risk of further upside.
Going into H2 2027, we expect moderating oil prices and the fading inflationary impact of tariffs to give the Fed room to consider rate cuts. The US 30-year yield, however, is likely to stay elevated as fiscal deficit remains substantial next year.
We expect a final ECB hike to 2.75% by December 2026, then a pause in H1 2027, followed by a 25bps cut in Q3 2027. In Japan, we expect quarterly pace of BoJ hikes, with one hike that takes the policy rate to 1.50% by December 2026 and two more in H1 2027, reaching 2.00% before pausing at mid-year.
DM corporates – Core holding
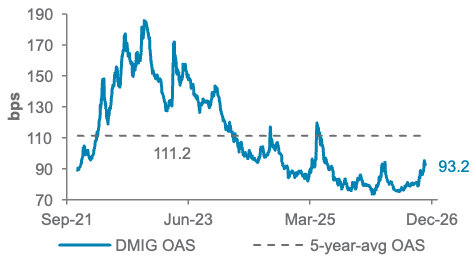
We maintain a Neutral allocation to both DM IG and DM HY corporate bonds, with a tactical bias to add exposure on episodic weakness, as carry continues to dominate total returns across DM credit. Credit spreads have widened from their lows but remain close to historical tights, while yields are still attractive, reinforcing a carry-led stance. This tight-spread regime is anchored by robust issuer fundamentals, strong profitability and resilient balance sheets, despite a visible moderation in rating upgrades over the past quarter.
Technical supply dynamics are reshaping sector dispersion, especially in the IG space, where heavy AI-related issuance is weighing on the long end of the curve. AI-driven supply is surpassing USD 250bn in 2026 and making up a growing share of US IG gross issuance, but there are growing signs that hyperscalers are turning to private markets for funding, which should help ease public bond market supply pressures.
We remain selective at the long end of the yield curve and favour a duration of 3-7 years, where risk-adjusted carry remains most durable. Issuance-driven concessions in sectors with strong capex cycles (notably technology, capital goods and basic industries) present opportunities for investors who can stomach near-term volatility.
Fig. 12 DM IG spreads have widened from their lows, but remain near historically tight levels
Bloomberg Global Aggregate Corp Index, option-adjusted spread (OAS)
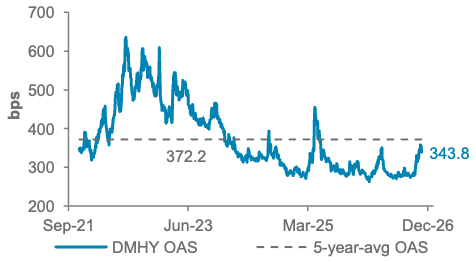
DM HY spreads have widened to roughly a six-month high. Persistent doubts about whether hyperscalers can generate adequate returns on massive AI capex investments triggered a broad risk asset sell-off. The CCC tier has become the focal point of genuine credit concern, with yields hovering near the high-15% range and spreads near a four-year high. Market focus has shifted to the funding pressures facing AI-related neocloud companies. We view this as idiosyncratic for now and see a limited impact on the broader HY universe. The underlying credit picture is mixed. Leverage is elevated and interest coverage is thin, but the broad market has not yet shown signs of systemic stress. The US HY default rate remains below trend in 2026.
HY offers an attractive income proposition, with all-in yields of over 8%. Its shorter-duration profile, combined with its lower sensitivity to changes in the term premium and rate volatility, make it an attractive sleeve in the current phase of the cycle. We remain attentive to evolving credit rating migration trends and sector-specific supply pressures, particularly as upgrades slow and new issuance clusters around key themes. However, healthy issuer fundamentals and stable credit metrics continue to support it as a Core holding allocation.
Fig. 13 DM HY spreads are off the tights
Bloomberg Global HY Aggregate Corporate Index, OAS
EM government bonds – Overweight USD/Core holding for LCY
We are Overweight EM USD government bonds and retain EM LCY government bonds as a Core holding, reflecting a balanced perspective across both regional performance and currency dynamics. In EM USD sovereign debt, the recent spread widening offered an attractive entry point to gain exposure to areas benefiting from resilient global growth and stable external conditions. Technicals remain favourable, with supply being front-loaded and investor positioning remaining relatively light compared with historical levels.
Many EM central banks having tightened earlier and more aggressively post-pandemic, preserving credibility and maintaining positive real rates. External balances have improved, reserve buffers have increased and greater reliance on domestic funding reduces external vulnerability. Lula’s surprise win in Brazil’s presidential election raises political risk. The country’s fiscal trajectory under the incoming administration is a key risk to monitor. Fiscal slippage could trigger a broader repricing of LATAM risk. In Asia, higher-rated issuers continue to offer a valuable buffer during bouts of global rate volatility, while select frontier exposures in EMEA remain more sensitive to liquidity shifts and changes in risk appetite. Index composition also shapes resilience: the EM USD benchmark is less exposed to oil price shocks, as countries that are not oil importers account for a larger share of the benchmark than in the LCY benchmark. We expect returns to be primarily driven by carry rather than further spread compression.
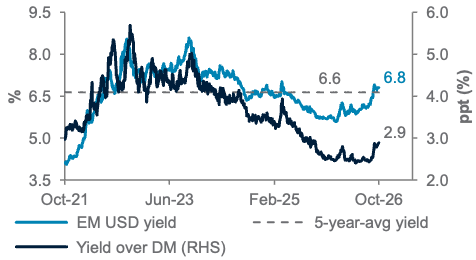
Fig. 14 EM USD government bonds offer a yield pick-up of nearly 3ppt over DM peers
Bloomberg EM USD Government Bond Index, yield to worst
EM LCY debt faces additional headwinds, especially as elevated US real yields and an appreciating USD dampen demand from foreign investors and reduce the comparative attractiveness of broad-based duration strategies. However, real yields remain comparatively supportive in several markets, and current valuations signal selective opportunities, especially given the restrictive monetary policy stances prevalent across many EM economies. Accordingly, EM LCY bonds retain their Core holding status, with portfolio emphasis
placed on country selection and measured duration exposure, reflecting the differentiated currency dynamics at play.
Key risks to both the USD and LCY segments include a potential escalation of the Middle East conflict, higher oil prices, renewed hawkishness from the Fed that could support further USD strength and weather-related disruptions, such as the effects of El Niño. Climate risks could prolong inflation pressures and hinder disinflation in vulnerable EM regions.
Asia USD bonds – Core holding
We retain a Neutral allocation to Asia USD bonds, an asset class that continues to reward investors with attractive nominal yields, favourable supply-demand technicals and robust credit fundamentals. Healthy corporate cash flows, low leverage and a high share of sovereign-linked issuers lend the segment a defensive quality relative to broader credit.
The resilience has been evident year to date (YTD). Asia USD bonds have outperformed both DM government and DM IG corporate bonds on a total-return basis. We expect this relative strength to persist. The combination of carry and credit quality (over 60% of issues are sovereign or sovereign-related) anchors our conviction in the asset class, even as we maintain a Neutral stance.
Equity – at a glance
|
|
||||
|
Our view
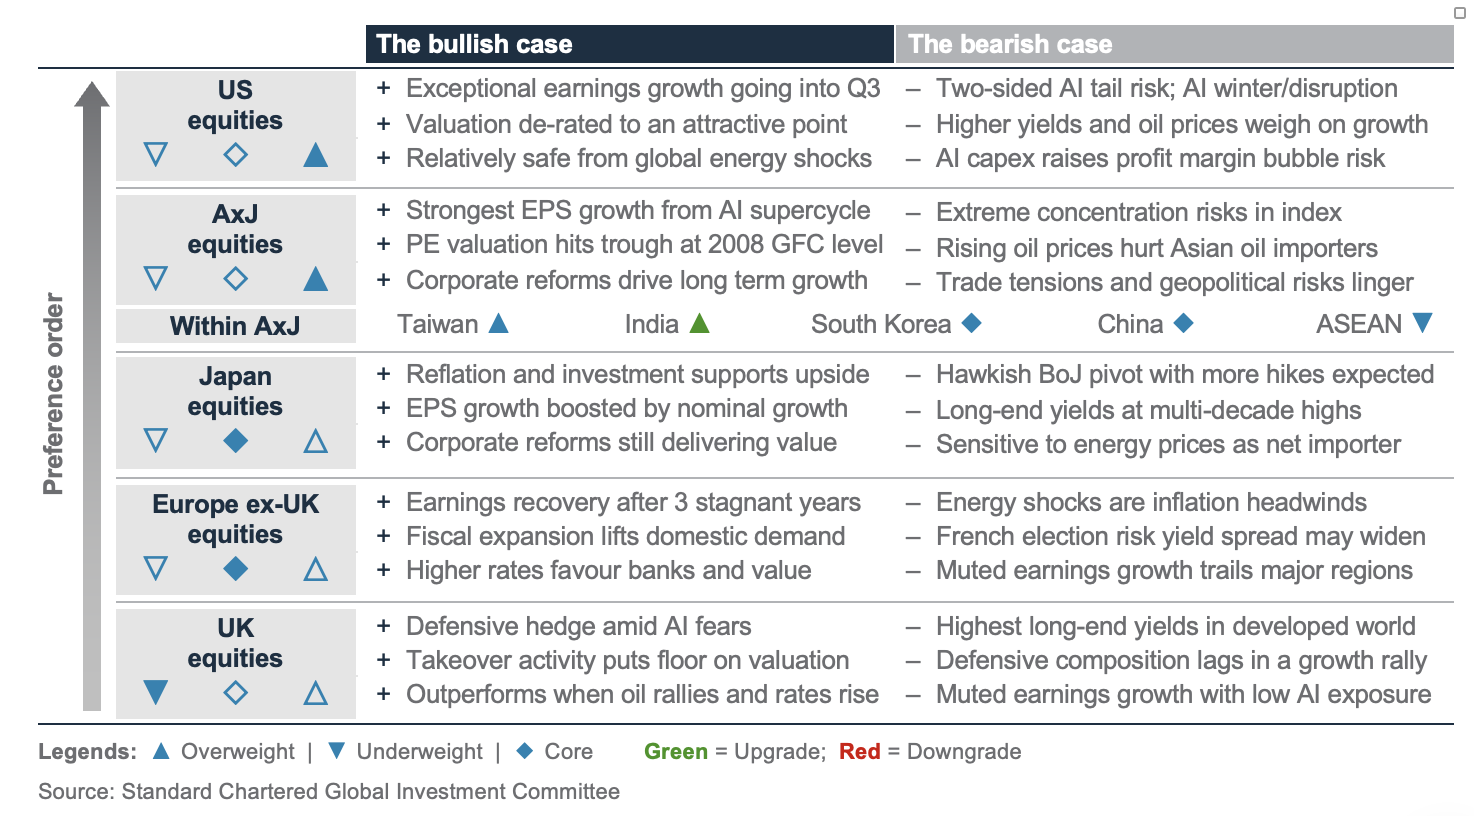
We downgrade global equities from Overweight to a Core allocation as we expect higher volatility in the near term. We expect this volatility to arise as equity market leadership broadens during the transition to a mid-cycle bull market. Equity returns will likely moderate from the 15-20% annualised range of the last few years but remain positive. We remain Overweight US and AxJ equities, which are expected to deliver the highest earnings growth in 2027 among the major regions.
Within AxJ, we remain Overweight Taiwan, given structural AI-driven growth, and upgrade India to Overweight, for diversified non-AI growth exposure. South Korea is a Core holding, with attractive valuations but extreme volatility. China is also a Core holding, with attractive valuations but lacking a positive catalyst. We are Underweight ASEAN, which has a weaker growth profile.
We maintain Japan as a Core holding as nominal growth supports broad-based earnings revisions. We also maintain a Core allocation to Europe ex-UK, which is enjoying an earnings recovery. We remain Underweight UK equities, given the market’s limited exposure to growth sectors.
Key chart
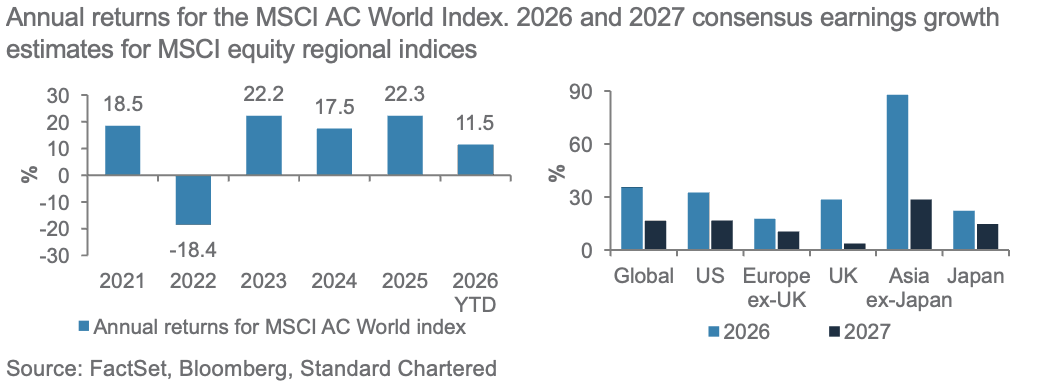
Earnings growth is driving gains in equities
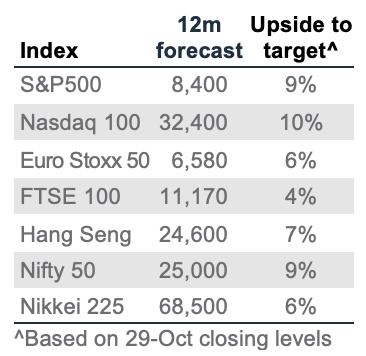
Fig. 15 Broad-based earnings strength is supporting global equities. Our Overweight views on AxJ and US equities are supported by robust earnings growth
Shifting to a mid-cycle bull market
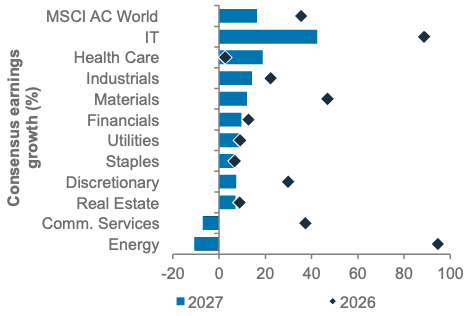
The last few years have seen strong annual returns of 15-20% for global equities, consistent with the early cycle of a bull market, driven in large part by a rapid AI buildout. As the AI infrastructure buildout is increasingly debt funded – we estimate 40% of AI capex in 2027 would be debt-financed – the market is increasingly concerned about the quality of this growth and execution risks. We remain positive on the structural AI theme, but we expect investor focus to shift from rapid buildout to monetisation. During this transition, we expect market leadership to broaden beyond technology. We believe this shift will also be accompanied by higher near-term volatility and a moderation in global equity returns, consistent with a transition to a mid-cycle bull market.
Fig. 16 Projected 16% earnings growth for global equities in 2027 provides a strong tailwind for positive equity returns
2026 and 2027 consensus earnings growth estimates for MSCI AC World sectors
US equities – Overweight
US equity valuations have declined this year, with the 12-month forward P/E falling to 19x from 22x at the start of the year. This reflects higher rates, a valuation headwind, and worries about the quality of growth, which is increasingly debt-funded. As market leadership broadens and the US mid-term election nears, we expect higher near-term volatility in the US market. Nonetheless, US equities have broad-based strength, with the ongoing Q3 earnings season pointing to a robust economy. In a world of rising geopolitical risks, the US is also relatively insulated by its domestically driven growth.
AxJ equities – Overweight
AxJ has the strongest earnings growth among major markets, as its technology sector remains a key beneficiary of the AI capex cycle. AxJ’s P/E valuations have also dropped to attractive trough levels, the lowest among major regions. Within AxJ, we are Overweight Taiwan, which benefits from clear visibility on AI-driven growth and dominance in manufacturing advanced AI chips. We also upgrade India to
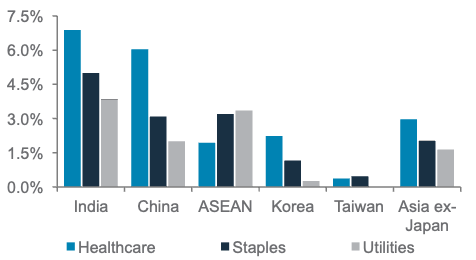
Overweight due to its resilient domestically driven earnings, providing diversification beyond AI-related growth. India offers the highest exposure to defensive sectors (healthcare, consumer staples and utilities) within AxJ. Both Taiwan and India offer attractive returns on equity.
South Korea equities remain a Core holding. We are positive on long-term agreements that improve earnings visibility for memory chipmakers. Valuations are attractive (the lowest in AxJ), with supportive corporate governance reforms. Still, extreme volatility remains the key overhang. China remains a Core holding, given inexpensive valuations, but re-rating potential appears delayed amid AI monetisation struggles, lingering regulatory risks and weak domestic demand. We remain Underweight ASEAN, as Indonesia’s downgrade warning, oil shocks and a well-supported USD could weigh on the region, although Singapore offers defensive growth.
Fig. 17 India offers highest AxJ exposure to defensive sectors (healthcare, consumer staples and utilities)
Sector weights for MSCI equity indices
Japan equities – Core holding
Rising nominal growth is supporting solid broad-based earnings revisions, with rising rates supportive of bank earnings. Corporate governance reforms also continue to boost shareholder value. The fiscal support for strategic industries is pro-growth, offsetting energy shocks.
Europe ex-UK equities – Core holding
Europe ex-UK is seeing an earnings recovery after three stagnant years, and we expect to see a continuation of this narrative with Q3 results. Rising rates are supportive of banks’ earnings and fiscal expansion is benefiting domestic demand. The fiscal situation in France has no easy solution, but we do not expect a contagion widening in government bond spreads, as the ECB has tools in place to limit contagion.
UK equities – Underweight
The UK lacks exposure to growth sectors, with relatively muted earnings growth. We expect this to weigh on the UK, making it lag the performance of other markets over the next 12 months, although UK equities tend to hold up better during bouts of volatility.
Equity opportunistic views
|
|
||||
|
Add MSCI Switzerland and US Healthcare, remove Global Power & Electrification, MSCI Taiwan, Global Semis and US Comm Services
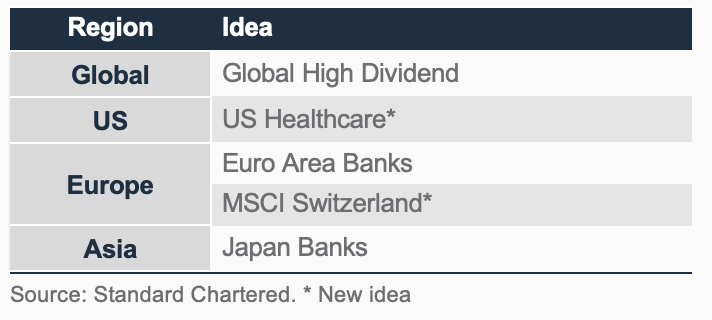
We initiate an opportunistic Idea on MSCI Switzerland on 29 October 2026, having initiated one on US Healthcare on 12 October 2026. Healthcare and Consumer Staples account for over 50% of the MSCI Switzerland Index’s weight, providing exposure to more resilient demand. It also has a sizeable financial sector supported by steady wealth management growth and well-capitalised insurers, which benefit from disciplined underwriting and resilient premium income.
We closed our opportunistic ideas in Global Semiconductors (9 September 2026 to 2 October 2026: +8.1%), MSCI Taiwan (9 July 2026 to 2 October 2026: +10.0%), US Communication Services (18 June 2026 to 12 October 2026: +1.9%), and Global Power & Electrification (30 July 2026 to 29 October 2026: -6.5%). This reflects a tactical reduction in exposure to tech-related sectors amid higher expected near-term volatility, rather than a deterioration in the fundamental outlook. Over the longer term, we remain constructive on these structural themes and may revisit these ideas at more attractive entry points.
Fig. 19 Opportunistic ideas
Ongoing Opportunistic Ideas
US Healthcare: We expect US Healthcare to offer resilience amid shifting market leadership, with the sector projected to grow by 23% in 2027, the second-fastest growth rate among MSCI US sectors, underpinned by healthcare innovation.
Euro area banks: A ‘higher-for-longer’ rate backdrop should extend the earnings upcycle, with further ECB tightening expected. Corporate loan demand is showing recovery, while non-interest income is growing. Strong capital generation supports higher dividends and continued share buybacks.
Japan Banks: BoJ policy normalisation drives net interest margin upside, while Japan’s reflation cycle supports nominal loan demand, corporate capex and household wealth activity. Governance reform is a re-rating driver independent of the
rate cycle. This includes recycling legacy holdings towards growth, buybacks and dividends.
Global High Dividend: Provides a higher-income equity allocation with historically lower volatility than the MSCI ACWI and modest downside cushioning on balance.
Sector views: Continue to broaden & diversify
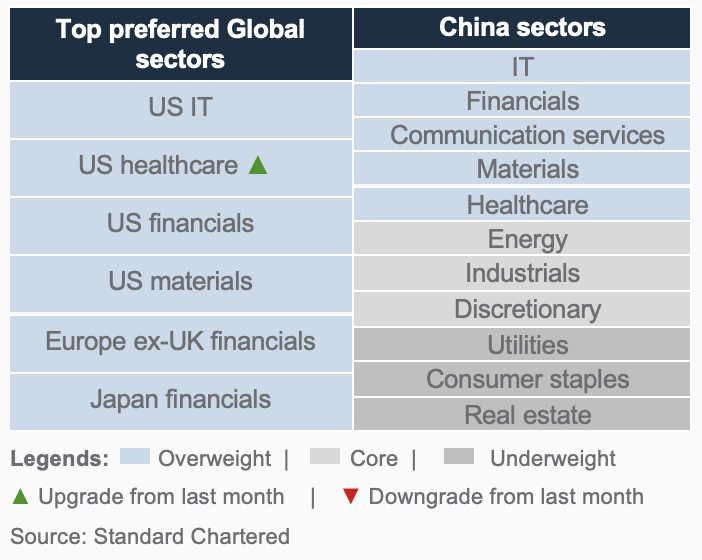
We made two changes on 12 October 2026: we downgraded US Communication Services to Neutral to reduce concentration in tech-related sectors and upgraded US Healthcare to Overweight, where its defensive exposure stands to benefit as investors diversify beyond concentrated AI exposure. This month, we downgrade Europe ex-UK Industrials to Neutral, as energy-cost shocks and supply-chain pressures outweigh fiscal support. Elsewhere, US Information Technology (IT) remains Overweight. Rising funding and execution risks warrant near-term caution, but structural AI tailwinds should continue to provide long-term growth opportunities. US Materials also stays Overweight on sustained demand for industrial metals and construction materials. We remain bullish on gold. The Financial sector remains Overweight across the US, Europe ex-UK and Japan, supported by stable earnings, elevated rates boosting net interest income and continued capital market recovery.
In China, we maintain a broad Overweight stance to preserve sector diversification. IT and Communication Services remain Overweight, with rapid innovation and investment in AI localisation providing tailwinds. Beyond these, we are also Overweight Materials on structurally elevated commodity prices, Healthcare on biotech innovation and a robust drug pipeline and the Financial sector on easing margin pressure, recovering fee income and capital market reform.
Fig. 19 Our sector views
Gold, crude oil – at a glance
|
Our view
- We remain Overweight gold, but trim our three- and 12-month price targets to USD 4,350/oz and 4,700/oz, respectively.
- We retain our three- and 12-month West Texas Intermediate (WTI) oil forecast at USD 100/bbl and USD 80/bbl, respectively.
Key chart
Fig. 20 EM central bank demand a key support for gold
Selected EM central bank gold reserve changes
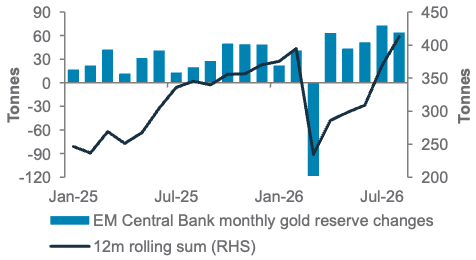
Fig. 22 WTI trails March-April conflict highs as tanker freight rates have more than doubled
WTI spot price vs. Baltic Dirty Tanker Index
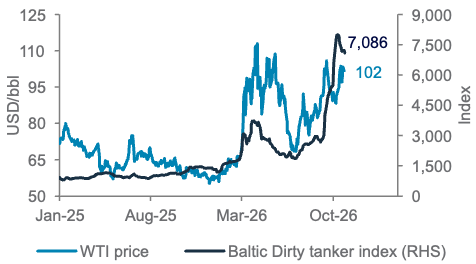
Fig. 21 Gold’s recent correction coincides with renewed USD strength
Gold price vs. DXY
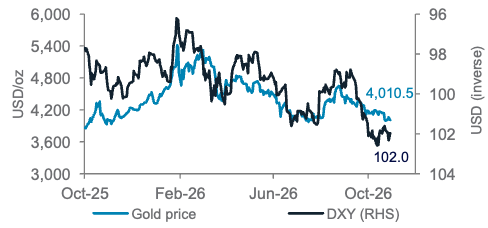
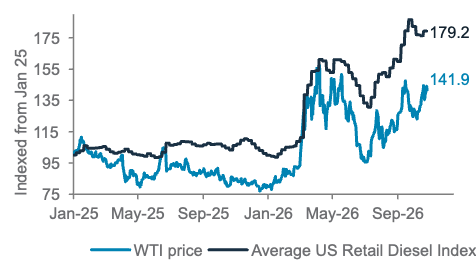
Fig. 23 Diesel prices have outpaced crude oil prices as downstream pressures intensify
WTI crude oil prices vs. US retail diesel prices, (Jan-25=100)
Gold outlook: We remain constructive over 6-12 months, viewing the latest pullback as liquidity-driven rather than a deterioration in fundamentals. USD strength is a headwind, but gold’s sensitivity to real yields has eased amid continued central bank buying, led by China, and resilient investor demand. Speculative positioning near May lows raises scope for renewed inflows. High oil prices sustain near-term volatility but may eventually lift gold if they constrain global growth.
Oil outlook: Crude prices remain elevated as shipping disruptions drive freight costs to multi-year highs, sustaining a geopolitical risk premium. While Middle East exports have proven resilient, threats to production infrastructure are mounting. Refined products, especially diesel, face the greatest supply pressure amid depleting inventories and constrained refining capacity. With limited emergency supply buffers, oil markets remain vulnerable to prolonged disruption.
FX – at a glance
|
|
||||
|
USD view
USD consolidation with limited upside: Our three-month US Dollar Index (DXY) forecast stands at 101, revised upwards from 100.20 last month, reflecting a higher expected Fed rate path. With the October Fed rate pause and a potential December rate hike largely priced in, further tightening would offer limited additional USD support. Persistent inflation, elevated US government bond yields and resilient business activity continue to underpin the USD’s interest-rate advantage. However, in September, payroll growth slowed sharply to 29,000 (from 133,000 in August), the unemployment rate rose to 4.2% from 4.1%, annual wage growth eased to 3.0% from 3.1% and housing starts fell 5.2% m/m. These signs of cooling demand temper expectations of more aggressive Fed tightening. We expect DXY to remain rangebound between 101 and 103, with our three-month forecast at 101.00.
Peaking Fed rates and narrowing rate differentials favour gradual USD weakness: We maintain our 12-month DXY forecast at 98.50. We expect a Fed rate hike in December 2026 and another in H1 2027, taking the federal funds target range to a peak of 4.25-4.50%, before easing in H2 2027. Further BoJ normalisation and the ECB’s relatively restrictive policy stance should progressively narrow the USD’s rate advantage. Persistent fiscal and current account deficits increase reliance on foreign capital inflows, adding to medium-term pressure on the USD. Resilient US growth, AI-related capital inflows and elevated US government bond yields remain important offsets, supporting DXY’s gradual decline towards 98.50.
Key charts
Fig. 24 USD to consolidate near-term; expected Fed hike peak in H1 2027 supports a decline to 98.50 over 12 months
DXY and interest rate differentials
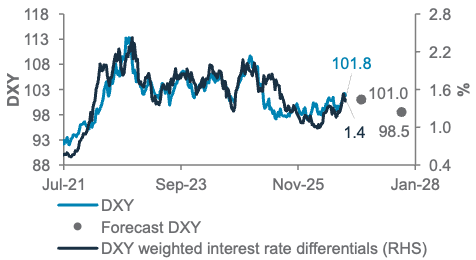
Fig. 26 CHF safe-haven demand limits USD/CHF upside, despite wide US-Swiss yield differentials
USD/CHF and US-Swiss 10-year bond yield differential
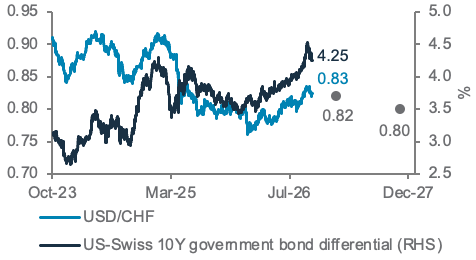
Fig. 25 France’s fiscal risks weigh on the EUR in the near term, despite a medium-term recovery
EUR/USD and Germany-France 10-year bond yield spread
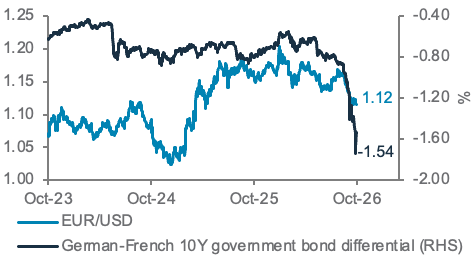
Fig. 27 USD/CNH declines alongside firmer PBoC fixing guidance
USD/CNH and the PBoC fixing rate
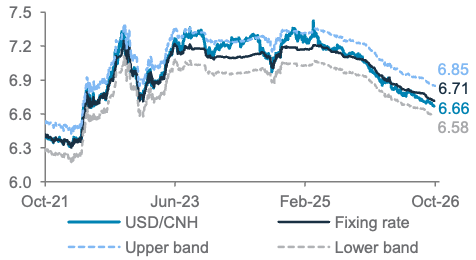
Fig. 29 Summary of G7 and select Asian FX forecasts and drivers
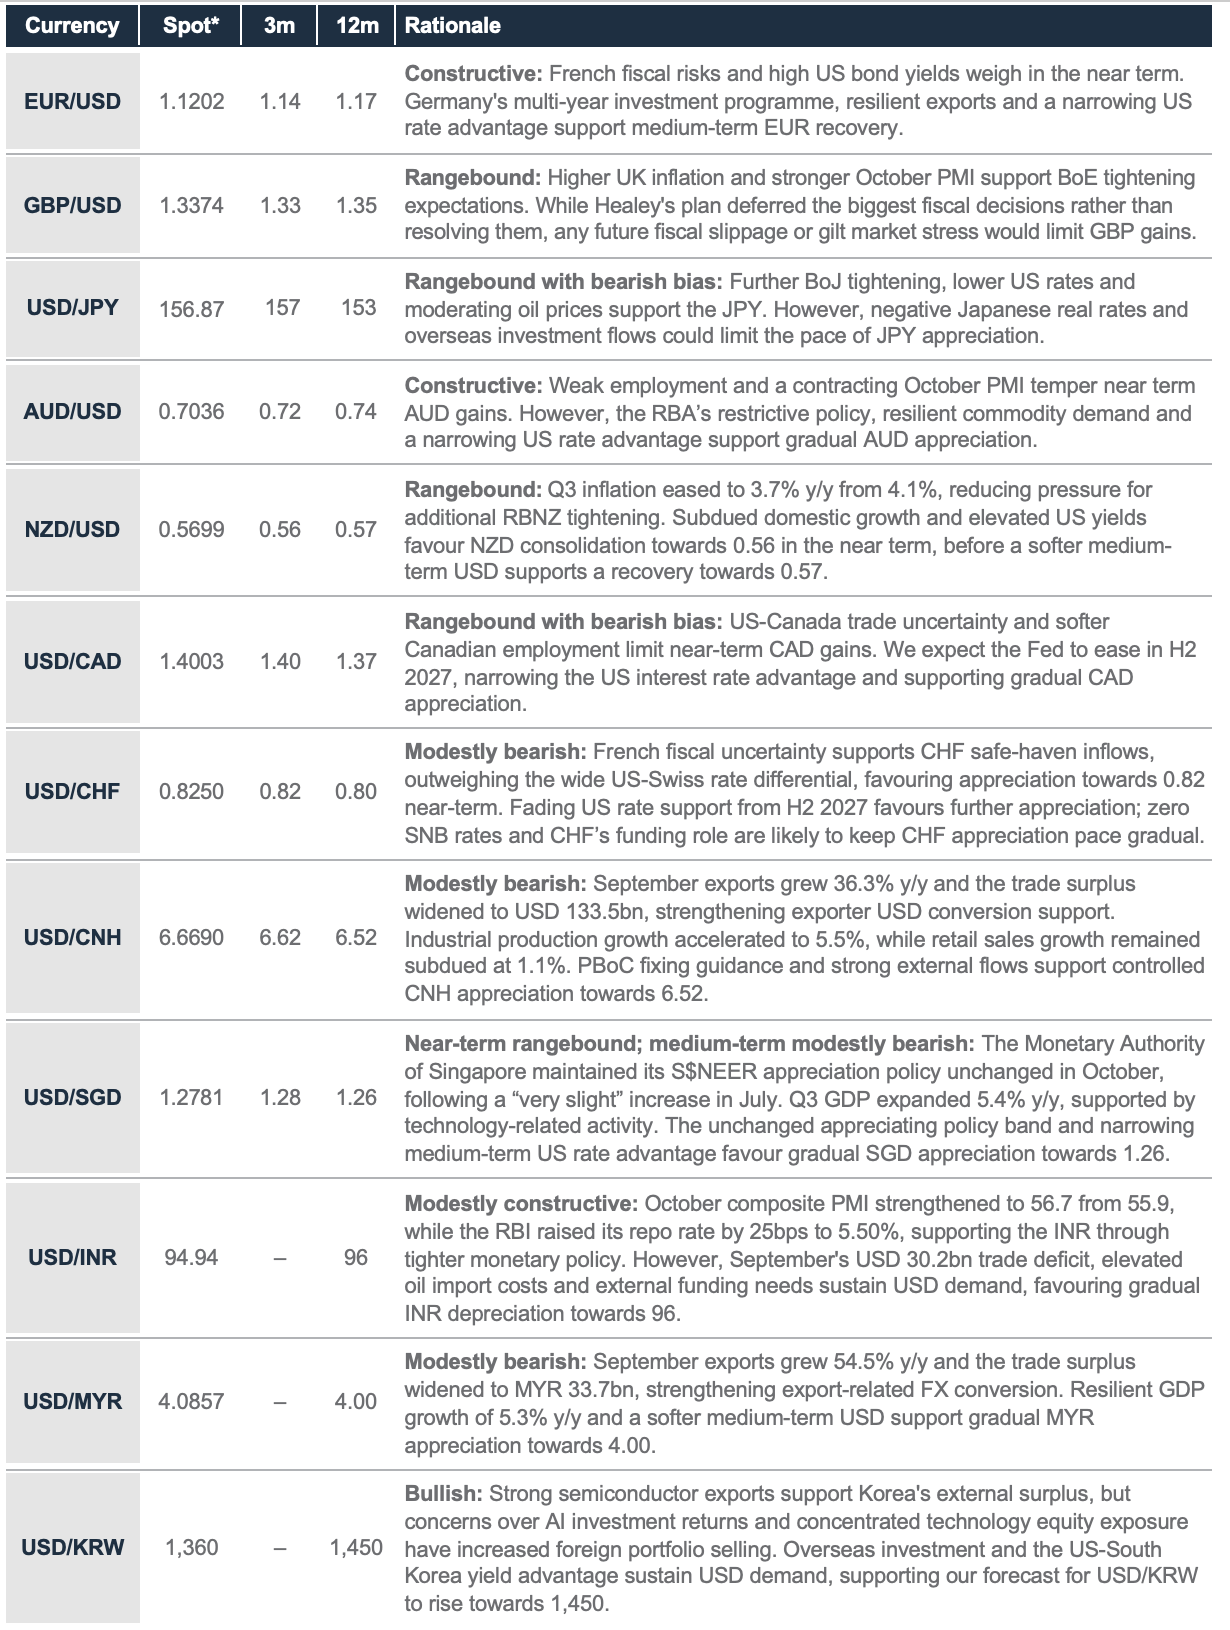
*As of 4am, 26 Oct 2026 SGT
Additional perspectives
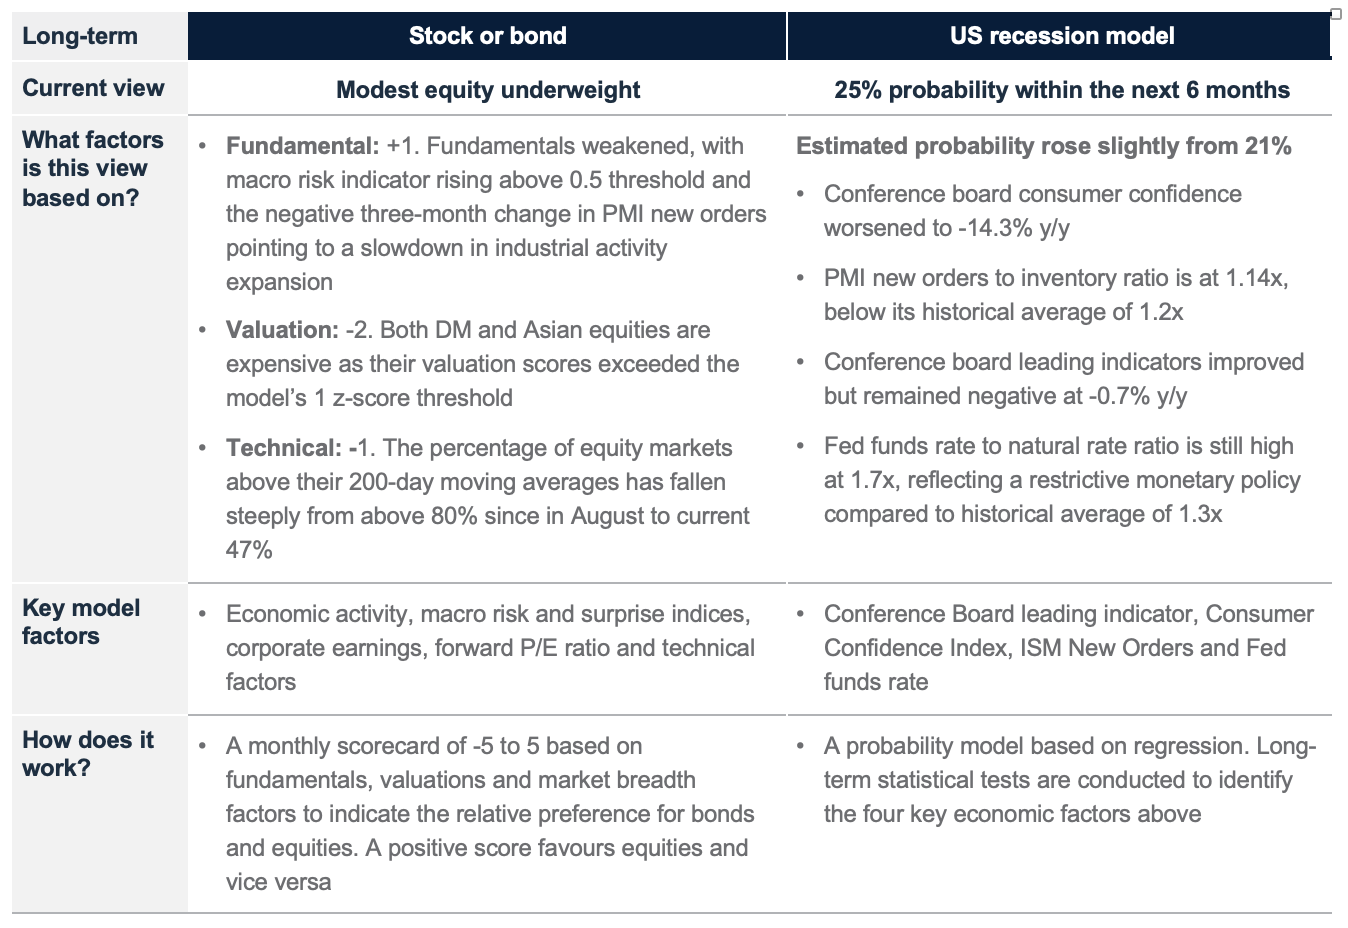
Quant perspective: Modestly UW equity as near-term risk rose
|
|
||||
Summary
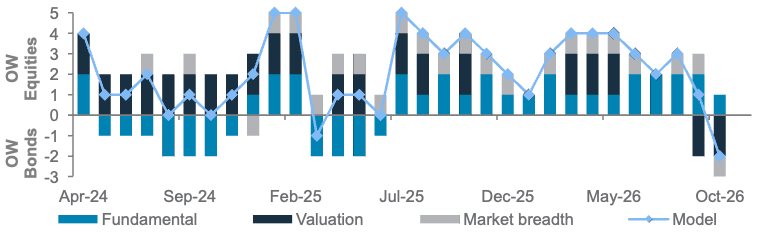
Our stock-bond model (3-6 months) is at -2 (minimum: -5) in October, signalling a modest Underweight (UW) in global equities. Historically, a decline in the model score to -2 has been associated with flat to slightly negative returns. The shift was driven by stretched valuations in both global and Asian equities, weaker fundamentals and deteriorating market technicals. On fundamentals, market risk aversion has risen sharply, while PMI new orders have declined over the past three months, pointing to a slowdown in the pace of industrial expansion. On technicals, the share of equity markets trading above their 200-day moving averages, a key gauge of long-term support, has fallen below 60% for the first time since January 2025. The model rebalances in the middle of each month and has generated 11bps of alpha from the equity Underweight initiated on 15 October 2026, lifting YTD alpha vs. the 60/40 equity-bond benchmark to 4.0%.
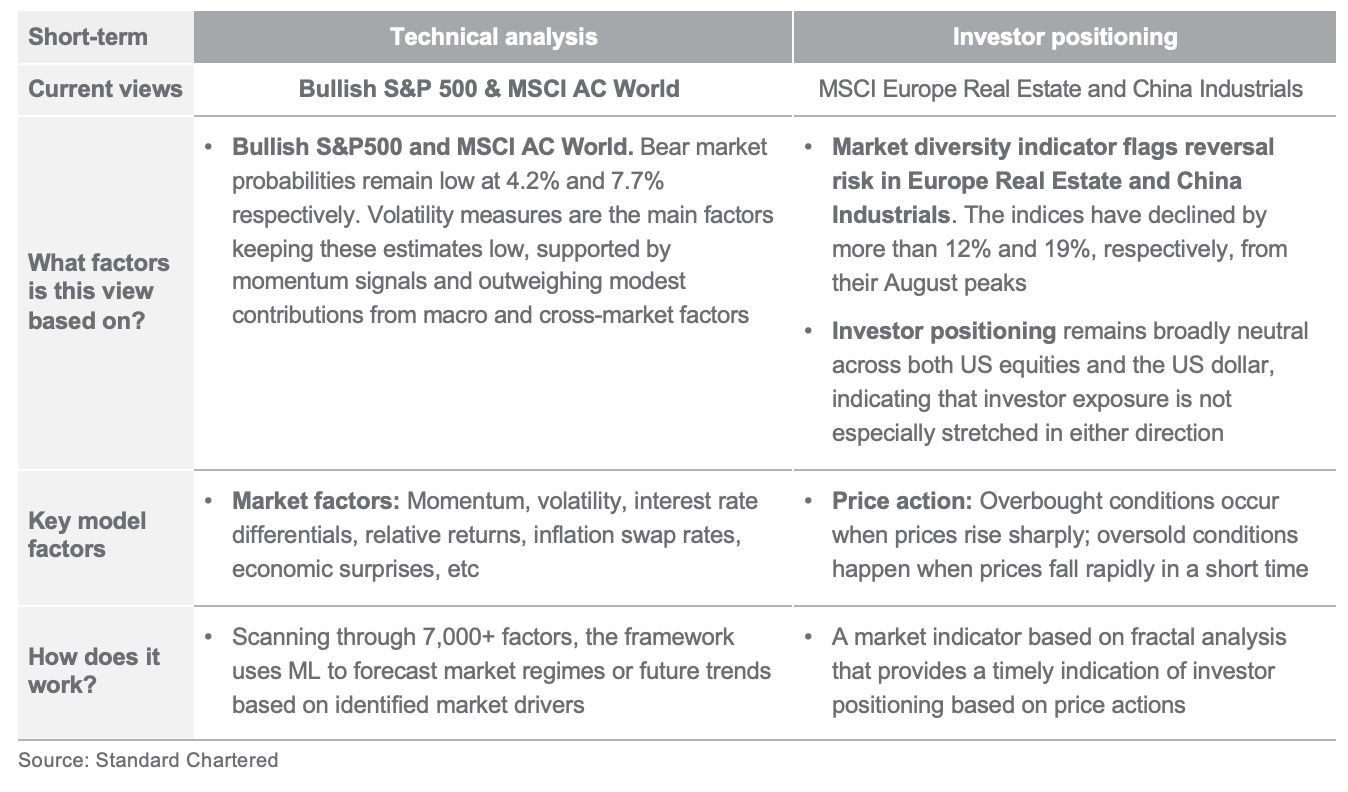
Our 1-3-month equity market regime model indicates contained bear market risks across US and global equities. Estimated bear market probabilities are 4.2% for the S&P500 and 7.7% for the MSCI AC World, compared with 0.9% and 6.4% respectively in the September outlook. Across both models, volatility measures are the main factors keeping probabilities low, supported by momentum signals. Together, these outweigh modest upward contributions from macro and cross-market factors, leaving little evidence of a bear market regime over the next 1-3 months.
Our market diversity indicator flags reversal risk in MSCI Europe Real Estate and MSCI China Industrials, which are down over 12% and 19% respectively from their August peaks. US equity and USD positioning remain broadly neutral.
Key chart
Our stock-bond model shifted its Overweight allocation towards bonds as valuation and technical signals weakened
Fig. 29 Breakdown of our stock-bond rotation model’s scores
Our model reduced equity weight to 36% from 68% as the model score fell to -2
Volatility and momentum signals continue to keep bear market probabilities low. The latest results remain consistent with a non-bear market regime over the next 1-3 months, rather than signalling a major downturn
|
|
Fig. 30 Our technical model remains bullish on the S&P500
S&P500 Index; model’s bearish signal; technical support and resistance levels
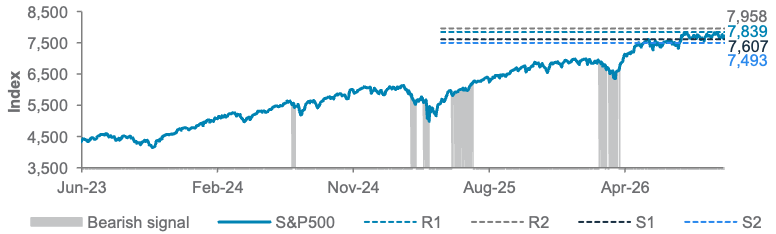
Fig. 32 Long- and short-term quantitative models remain bullish on risk assets
Long-term models below have a typical time horizon of 3-6 months, while short-term models have a 1-3-month horizon
Performance review
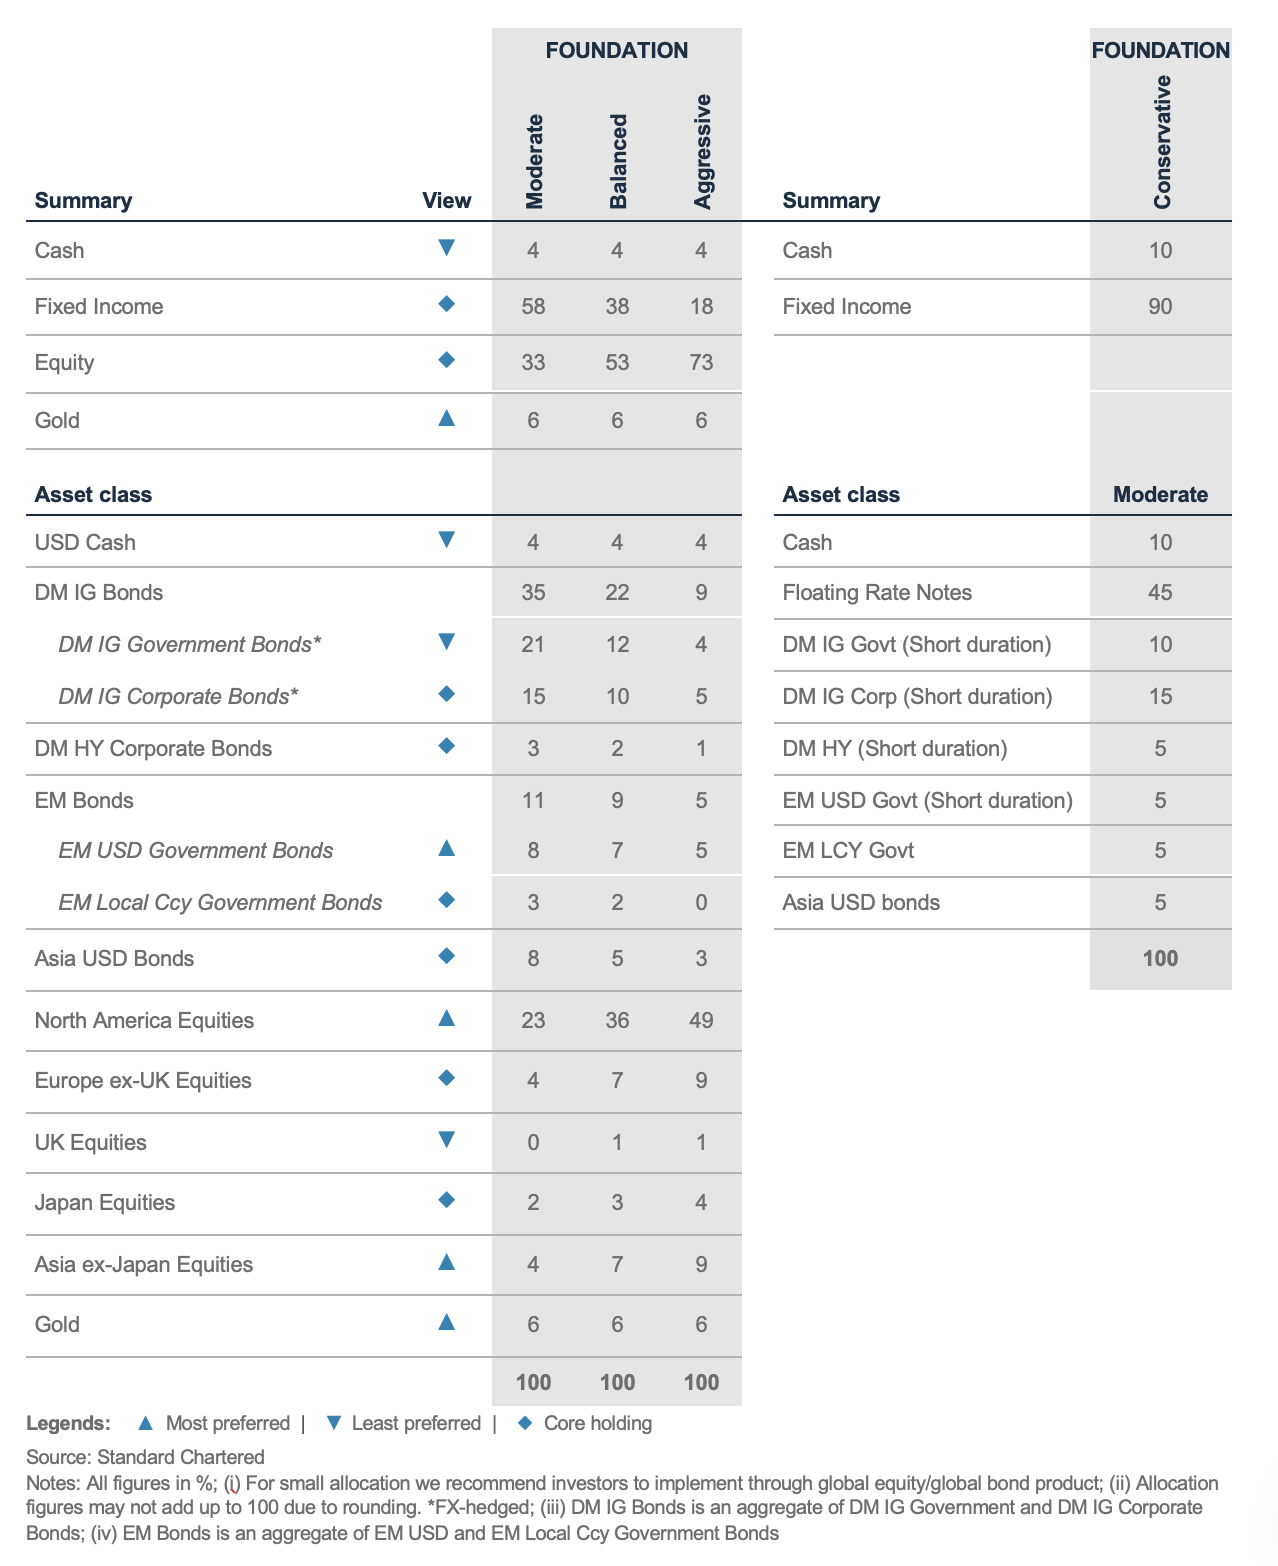
Foundation: Asset allocation summary
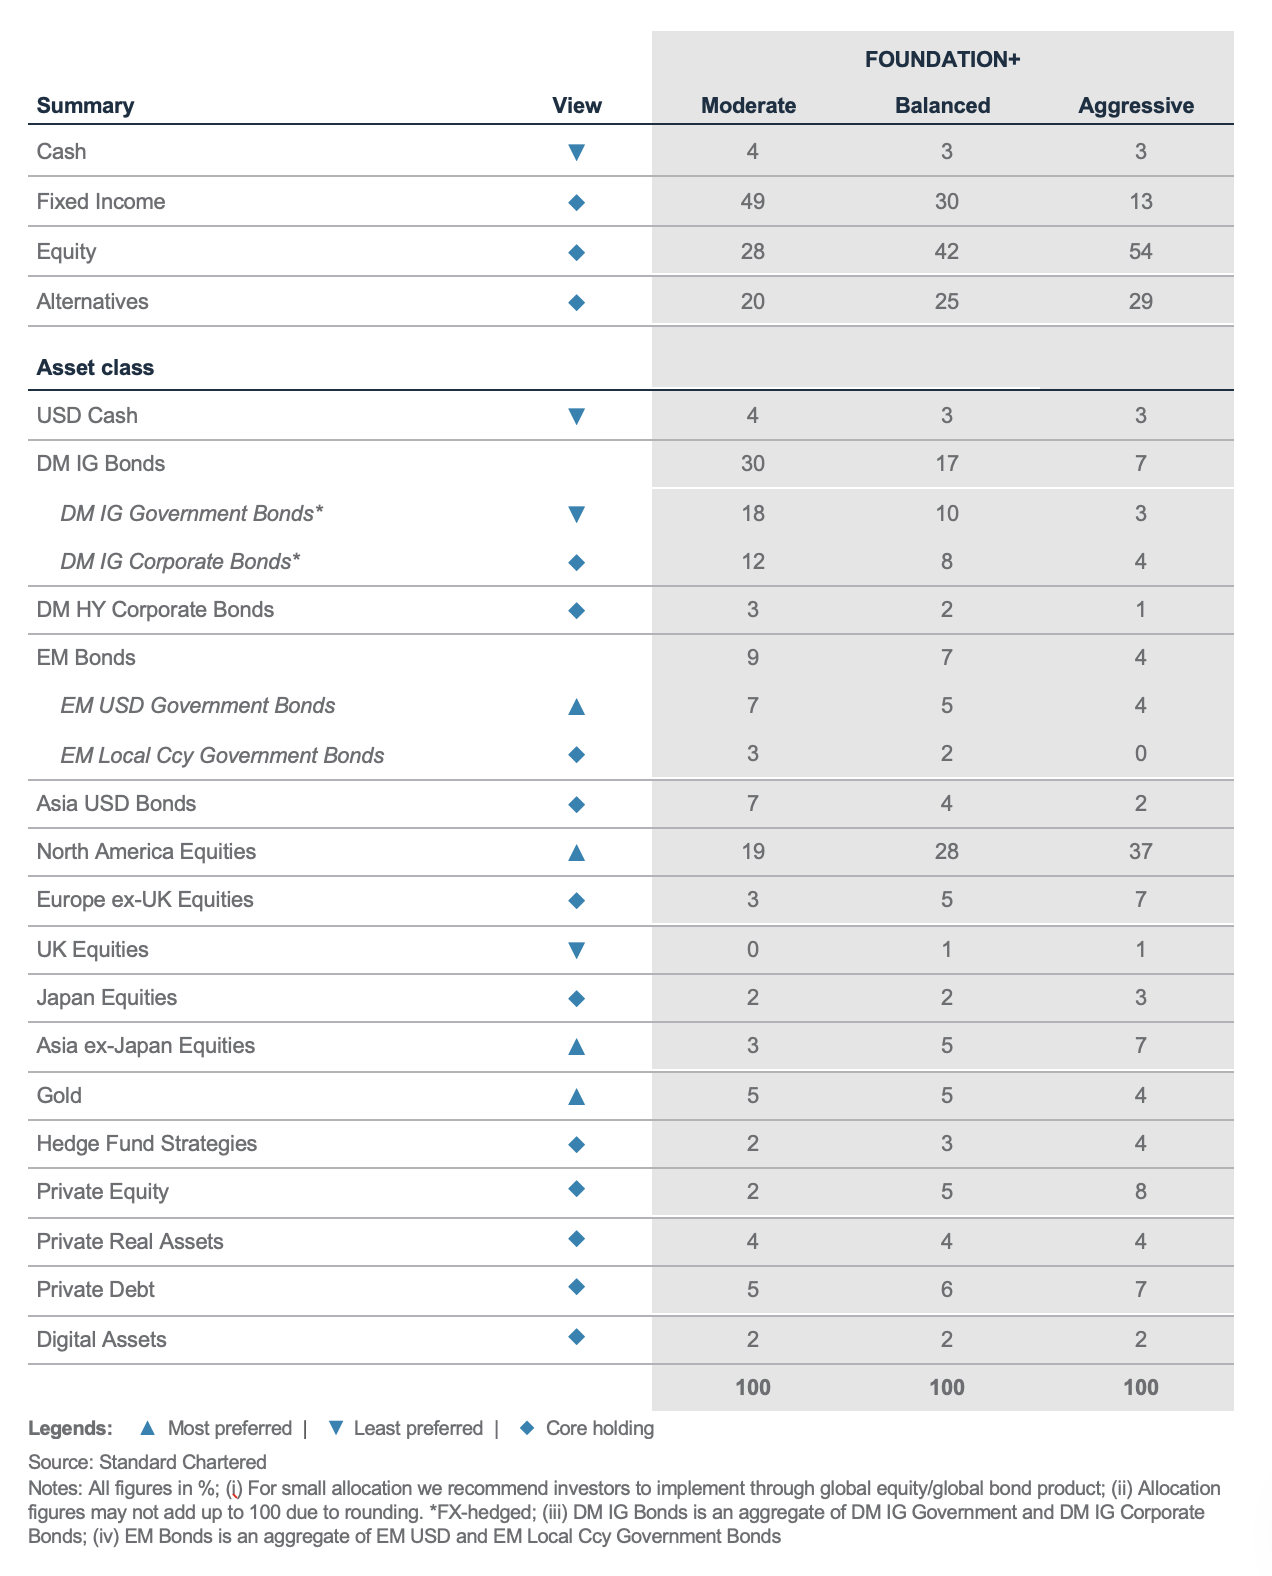
Foundation+: Asset allocation summary
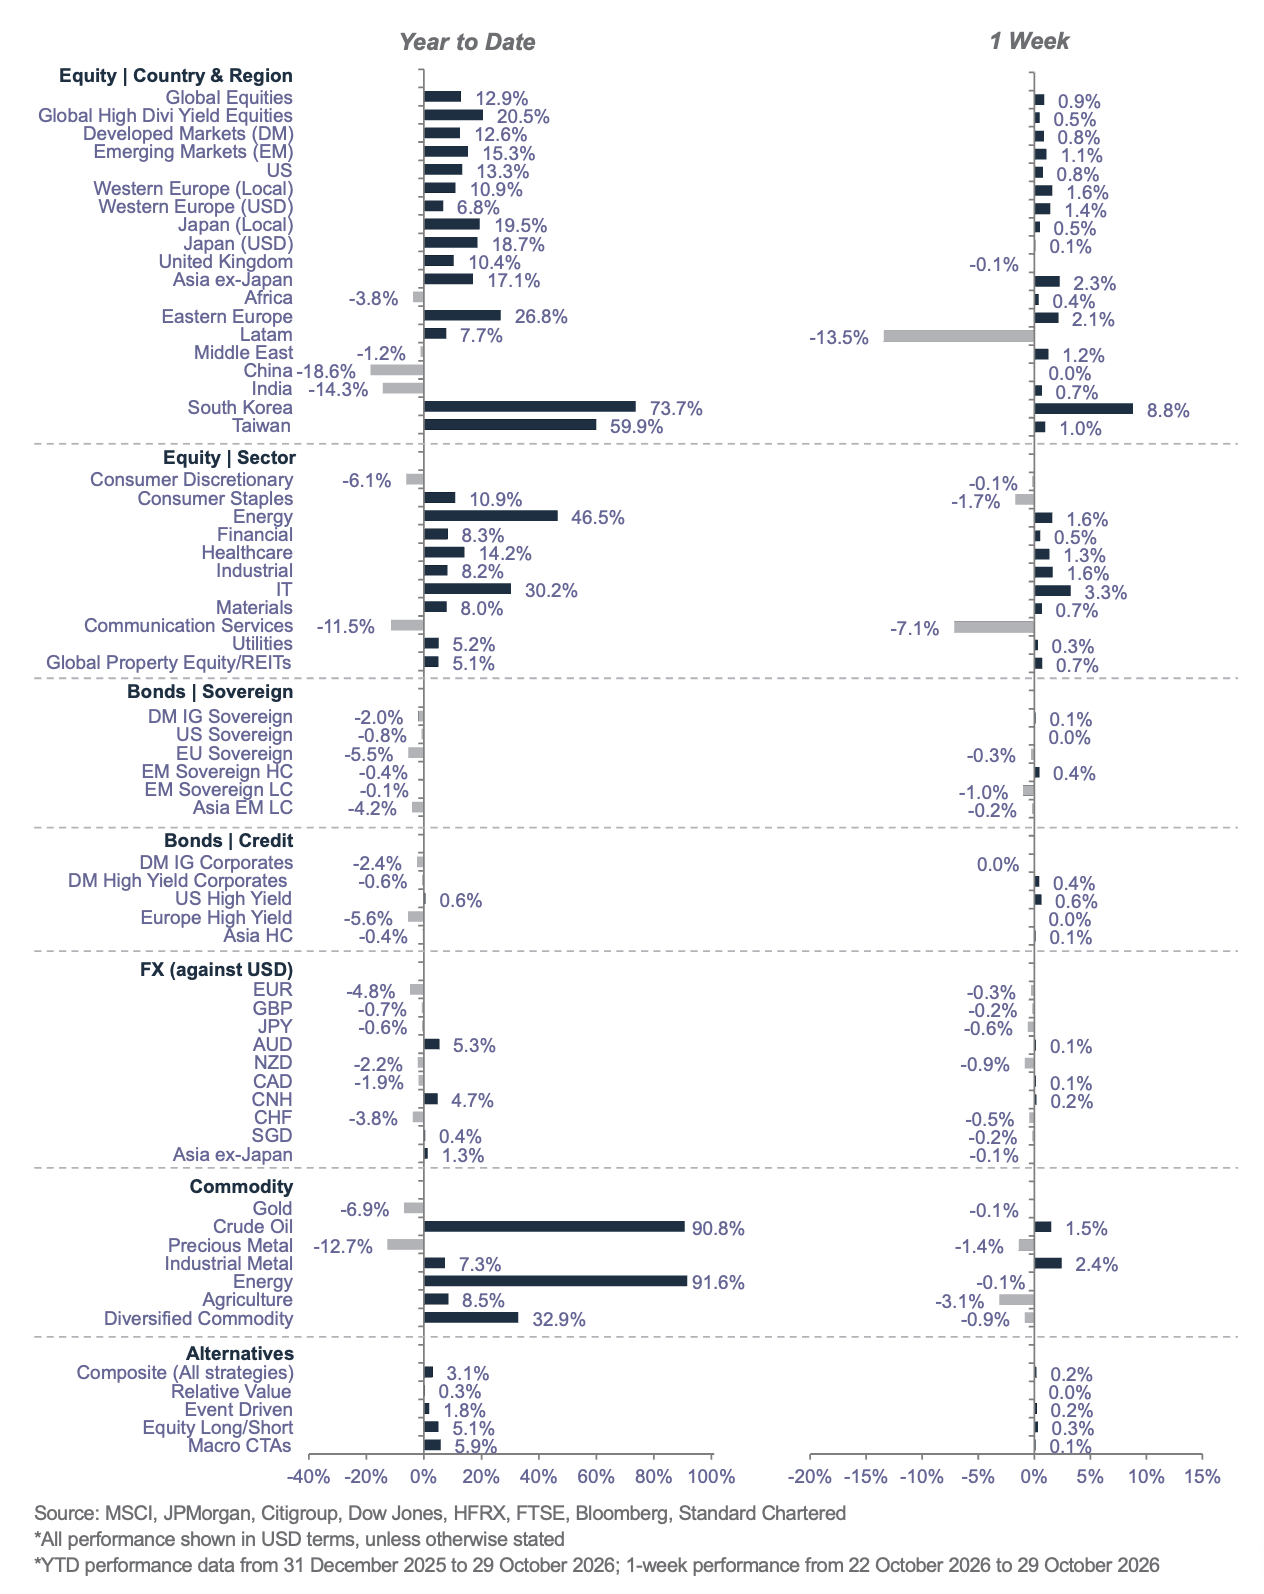
Market performance summary
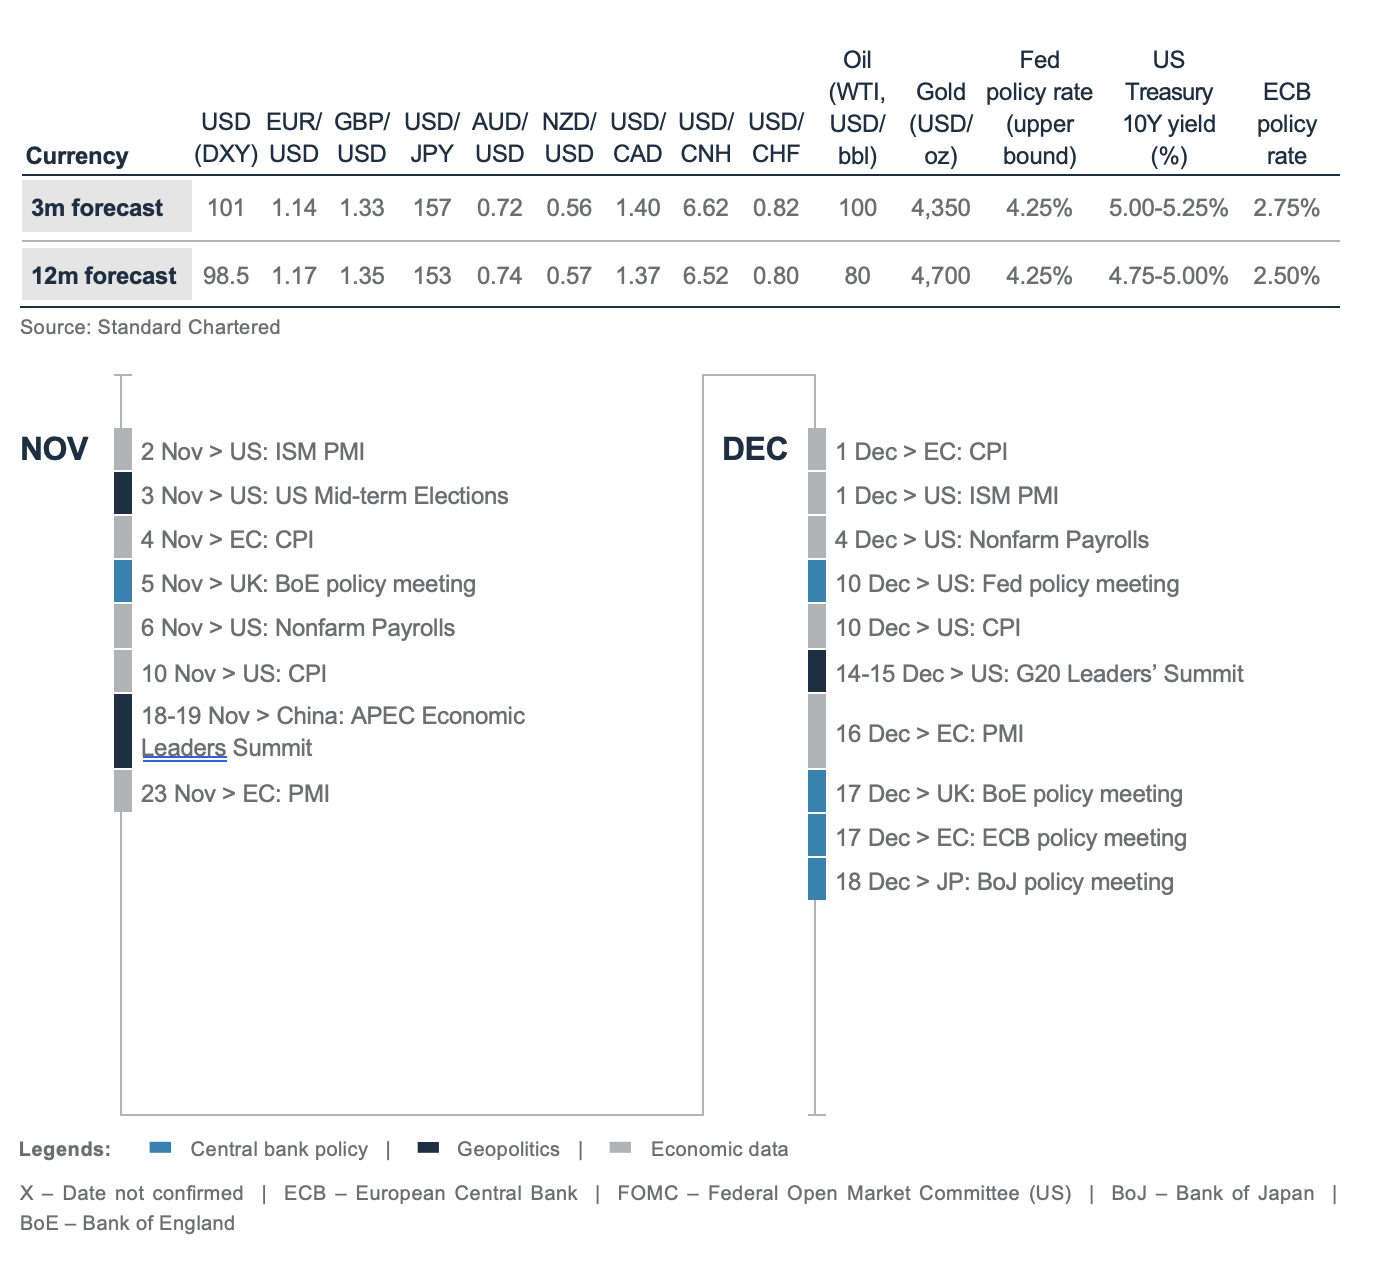
Our key forecasts and calendar events
SC Wealth Select
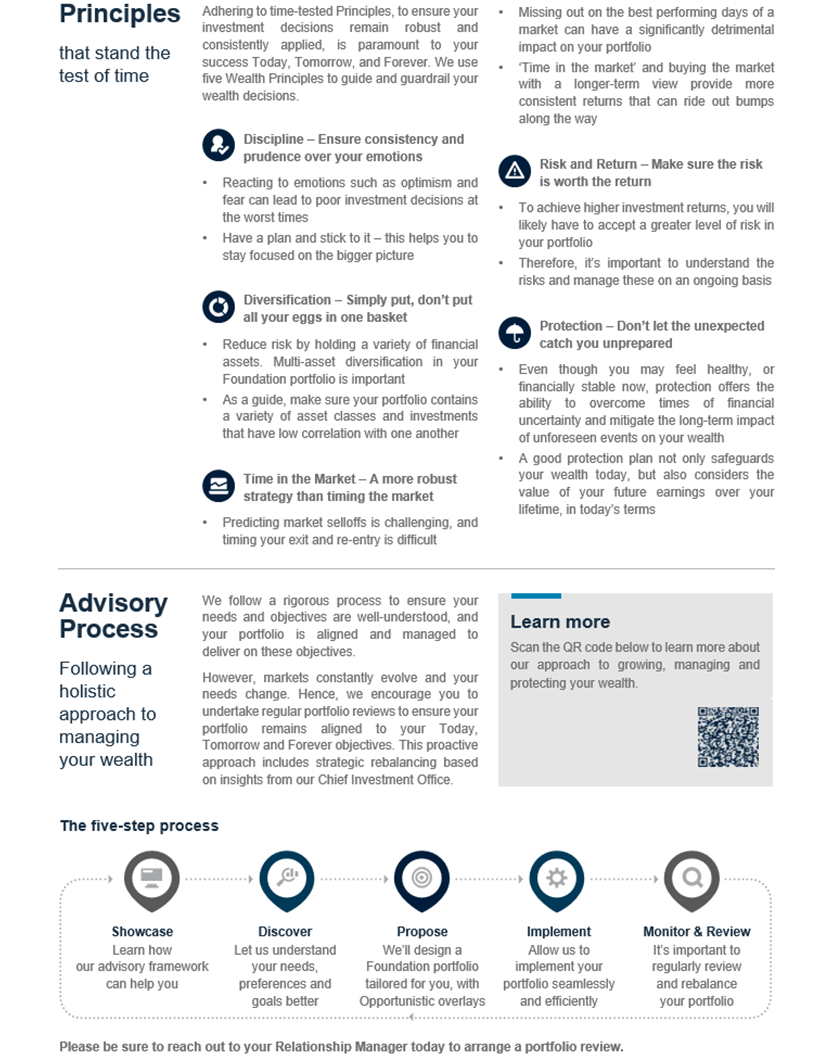
Explanatory notes
- The figures on page 5 show allocations for a moderately aggressive risk profile only – different risk profiles may produce significantly different asset allocation results. Page 5 is only an example, provided for general information only and they do not constitute investment advice, an offer, recommendation or solicitation. They do not take into account the specific investment objectives, needs or risk tolerances of a particular person or class of persons and they have not been prepared for any particular person or class of persons.
- Contingent Convertibles are complex financial instruments and are not a suitable or appropriate investment for all investors. This document is not an offer to sell or an invitation to buy any securities or any beneficial interests therein. Contingent convertible securities are not intended to be sold and should not be sold to retail clients in the European Economic Area (EEA) (each as defined in the Policy Statement on the Restrictions on the Retail Distribution of Regulatory Capital Instruments (Feedback to CP14/23 and Final Rules) (“Policy Statement”), read together with the Product Intervention (Contingent Convertible Instruments and Mutual Society Shares) Instrument 2015 (“Instrument”, and together with the Policy Statement, the “Permanent Marketing Restrictions”), which were published by the United Kingdom’s Financial Conduct Authority in June 2015), other than in circumstances that do not give rise to a contravention of the Permanent Marketing Restrictions.
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: Standard Chartered Bank, India (“Bank”) (ARN-1209) is an AMFI-registered distributor of select Mutual Funds and a referrer of certain third-party financial products. The Bank is not registered with SEBI as an Investment Adviser and does not provide investment advisory services or financial planning services as defined under the SEBI (Investment Advisers) Regulations, 2013. Any information contained herein is for informational purposes only and should not be construed as investment advice, recommendation, research report, or an offer to buy or sell any security or financial product. Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The services/products described herein are not intended for any person resident in a jurisdiction where their distribution, solicitation or use would be contrary to local laws or regulations. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom, and all business transacted with Standard Chartered Bank, Jersey Branch and other Standard Chartered Group Offices outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.