

9 October 2026
Weekly Market View
Will earnings resolve
the bond-equity split?
Bond and equity market volatility has sharply diverged. Elevated bond volatility and political risks in the US and Europe warrant near-term caution, prompting us to lock in tactical gains in semiconductors and Taiwan equities.
Our quantitative stock-bond model turned negative for the first time since March 2025, signalling near-term equity volatility. We stay invested in a diversified allocation slightly overweight equities and prefer to navigate the upcoming results and macro events before adding back high-beta exposure within equities.
Consensus estimates point to a 31% y/y rise in S&P500 Q3 earnings, driven by technology-sector earnings growth of 67%. Earnings have beaten lofty estimates in H1 as the AI build-out exceeds expectations. This favours tech-led equities in the medium term.
In Europe, French political and fiscal risks cloud the EUR outlook, but regional bank equities remain attractive on robust profitability, capital strength and valuations.
What are the market implications of France’s political and fiscal uncertainty?
What is your outlook for the US Q3 earnings season?
Do you see further upside for USD/JPY?
Charts of the week: Diverging volatility
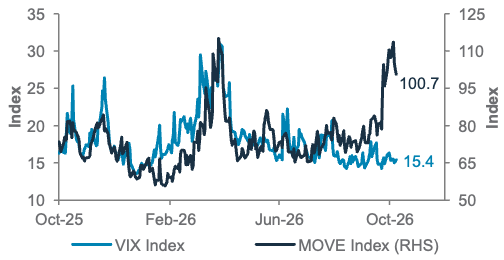
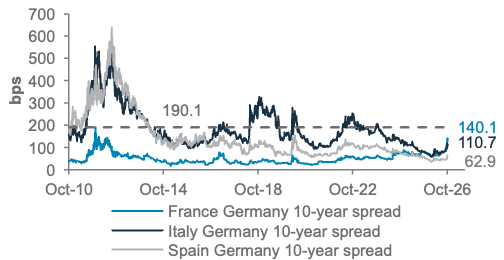
Strong earnings should resolve the bond and equity market divergence; French political risks remain largely contained
S&P500 volatility index (VIX); US bond volatility index (MOVE)*
10-year government bond yield spreads over German bonds
Source: Bloomberg, Standard Chartered; *measures US government bond volatility
Editorial
Will earnings resolve the bond-equity split?
Strategy summary: Bond and equity market volatility has sharply diverged. Elevated bond volatility and political risks in the US and Europe warrant near-term caution, prompting us to lock in tactical gains in semiconductors and Taiwan equities. Our quantitative stock-bond model turned negative for the first time since March 2025, signalling near-term equity volatility. We stay invested in a diversified allocation slightly overweight equities and prefer to navigate the upcoming results and macro events before adding high-beta exposure within equities.
Consensus estimates point to a c. 31% y/y rise in S&P500 Q3 earnings, driven by technology-sector earnings growth of c. 67%. Earnings have beaten lofty estimates in H1 as the AI build-out exceeds expectations. This favours tech-led equities in the medium term. In Europe, French political and fiscal risks cloud the EUR outlook, but regional bank equities remain attractive on robust profitability, capital strength and valuations.
Divergence between equities and bonds. Equity markets signal calm, with the S&P500 index near record highs and its volatility index (VIX) low at 15, while the US government bond volatility index (MOVE) is close to its highest since March. Bond stress reflects two-decade-high long yields amid strong growth, oil close to USD 100/bbl fuelling near-term inflation, fiscal uncertainty and crowded investor short positioning vulnerable to abrupt unwinds. High bond volatility could spill into equities.
Our quantitative stock-bond model turns negative. For the first time since March 2025, the model score has turned negative, driven by deteriorating equity market breadth and above-average risk aversion. History shows global equity volatility rises most in the month after the score dips to -1. However, equities still outperformed bonds over the following 1-12 months, on average, despite higher market risk.
Taking some chips off the table; locking in gains: Rising bond volatility, the negative stock-bond model signal, weak equity breadth and approaching US mid-term elections warrant near-term caution. US small-caps remain about 9% below August’s all-time highs even as large-caps reach new records.
The macro uncertainty prompted us to lock in gains in semiconductor and Taiwan equity opportunistic ideas.
Strong Q3 earnings season likely to overcome near-term challenges. Strong US and Asian earnings should ultimately resolve the equity-bond divergence in favour of stocks. Consensus S&P500 Q3 earnings growth has risen to 30.6% y/y, while technology is tracking 66.5%, driven by the AI infrastructure buildout. AI investment plans, monetisation and funding needs are key metrics to watch. Record memory-chip profits and higher long-term targets from AI leaders support staying long technology-led risk assets and using near-term volatility to scale into preferred sectors. Also, US equities have historically performed strongly in the 12 months after mid-term elections, particularly when the opposition regains control of the House and the Senate – as seems increasingly likely.
Medium-term constructive on equities. Beyond Q3 earnings, we expect US earnings to rise 15-20% next year. Almost half of the estimated USD 420 per share of S&P500 earnings in 2027 should come from tech-related sectors: information technology, communication services and consumer discretionary. We also favour US, Europe and Japan financial sectors as solid growth and higher rates lift lending income, while the AI buildout boosts advisory fees from IPOs and M&As. However, another 30-50bps rise in long-term bond yields, without earnings growth upgrades, could be a headwind for equities. Next week’s US inflation data for September is the next catalyst for bond yields.
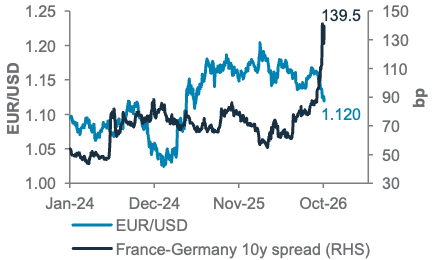
French uncertainty challenges near-term EUR view; continue to see opportunities in Euro area bank equities. Rising French political and fiscal risks have largely remained confined to France, with its bond yield spread versus German peers surging to the widest since the 2011-12 Euro area crisis. Nevertheless, EUR/USD has fallen around 4% since mid-August, and our three-month forecast of 1.15 is under review. Tighter financial conditions and political uncertainty in France and Spain raises the risk of an ECB rate hold. Euro area bank equities remain attractive on profitability, capital strength and valuations, subject to sovereign-spread and funding-cost risks.
— Rajat Bhattacharya and Sundeep Gantori
The weekly macro balance sheet
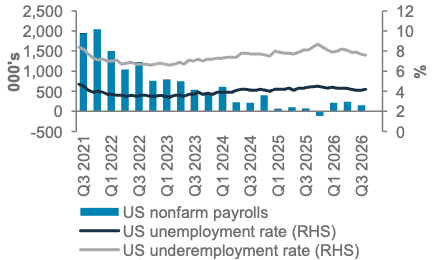
Our weekly net assessment: On balance, we see the past week’s data and policy as negative for risk assets in the near-term
(+) factors: Cooling US payrolls eased Fed hike concerns
(-) factors: Re-accelerating Euro area inflation; France’s fiscal crisis
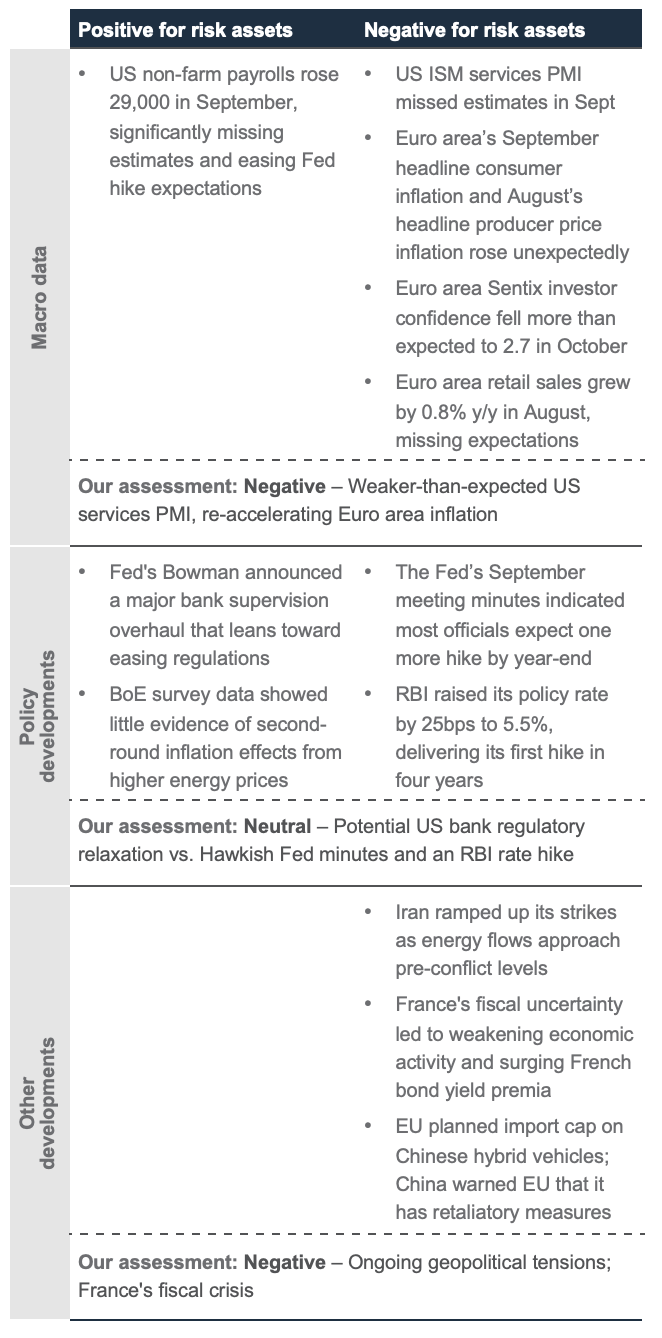
US non-farm payrolls came in below estimates in September and the unemployment rate rose, easing near-term Fed rate hike expectations
US non-farm payrolls (quarterly), unemployment rate and underemployment rate
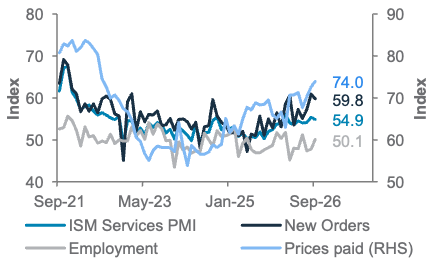
US ISM services PMI fell unexpectedly in September, with prices paid PMI for inputs rising to 74.0 and new orders PMI missing expectations
US services PMI and its components
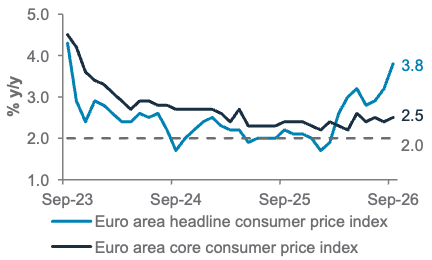
Euro area headline consumer inflation rose to 3.8% in September, marking the fastest rate of inflation since September 2023
Euro area headline and core consumer price inflation
Top client questions
What are the market implications of France’s political and fiscal uncertainty?
Our view: France’s political and fiscal uncertainty remain near-term headwinds for European assets. We are placing our three-month EUR/USD forecast (1.15) under review for a potential downward adjustment, while retaining our 12-month forecast at 1.18 as broader Euro area spillovers remain limited. Our base case remains one more ECB hike in December followed by a prolonged pause, although tighter financial conditions increase the risk of a delay. For equities, we retain Euro area banks as an Opportunistic idea, supported by strong profitability, capital buffers and reasonable valuations. For bank bonds, we prefer a subordinated capital structure to senior debt.
Rationale: France’s 10-year government bond yield has risen amid renewed political and fiscal concerns. This has tightened financial conditions and added to the near-term EUR risk premium. Together with elevated US yields, this raises downside risks to our three-month EUR/USD view. However, the stress has not yet developed into broad Euro area contagion, and recent expectations of progress on France’s 2027 budget have provided some relief. Broader Euro area growth and labour market fundamentals also remain relatively resilient, supporting our unchanged 12-month EUR/USD view.
For the ECB, higher sovereign yields are already delivering some monetary tightening. Markets have consequently pared expectations of additional ECB hikes. We continue to expect one more hike in December, given elevated near-term inflation, but persistent fiscal or political stress in France and Spain could delay further tightening.
For Euro area banks, wider sovereign spreads are likely to raise funding costs and pressure bond portfolios, while fewer ECB hikes would moderate further gains in net interest income. Nevertheless, profitability remains strong, capital buffers are healthy and price-to-book valuations remain reasonable, with returns on equity also improving. We, therefore, maintain Euro area banks as an Opportunistic idea, while monitoring sovereign spreads, funding costs and any deterioration in loan-loss provisions.
On the bond side, European bank junior subordinated bond prices fell by an average of 3-5 cash points before rebounding, with French bank subordinated bonds underperforming those of other European peers. As fundamentals remain strong, we view pullbacks as opportunities to add and maintain our preference for a subordinated capital structure over senior debt for European bank bonds.
— Vincent Tan, Senior Investment Strategist
— Fook Hien Yap, Senior Investment Strategist
— Ray Heung, Senior Investment Strategist
France’s fiscal concerns weigh on the EUR
EUR/USD vs. France-Germany 10Y government bond yield spread
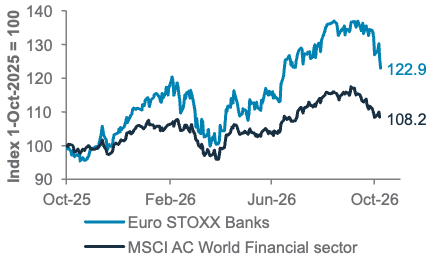
We remain positive on Euro area banks – they outperformed global financials over the past year, but gave up some of their outperformance over the past month
Euro STOXX Banks and MSCI AC World Financials indices over the past year, rebased
Top client questions (cont’d)
What is the likelihood of elevated long-end government bond yields evolving into a systemic risk for the financial sector and public finances?
Our view: We believe systemic risk remains a tail risk rather than a base case in the near term. The probability would rise materially if rollover stress, foreign demand withdrawal and private credit deterioration occur in combination.
Rationale: Higher bond yields worsen fiscal deficits and drive higher issuance requirements, exerting further upward pressure on yields. The resulting tighter financial conditions weigh on economic growth. This feedback loop is most acute in Developed Markets (DMs) where debt burdens are already elevated. For instance, projected 2026 debt-to-GDP ratios stand at 204% for Japan, 138% for Italy, 126% for the US, 118% for France and 104% for the UK. Countries with shorter average debt maturities face the sharpest near-term repricing risk as maturing obligations are refinanced at current rates. Meanwhile, evidence suggests that a positive equity-bond correlation increases the sensitivity of yields to bond supply.
Taking the US as an example, there has been no buyers’ strike on US government bonds yet, though foreign demand has softened, narrowing the margin of safety. The US government has shifted towards shorter-dated issuance to manage funding costs (reducing near-term expenses, but concentrating rollover risk). Economic resilience remains evident, underpinned by corporate confidence in AI-driven investment. The key question is whether this expansion can persist long enough to stabilise the fiscal trajectory.
Within the financial sector, corporate balance sheets remain strong, while High-Yield (HY) bond and leveraged loan default rates remain contained, though this reflects the lag between rate rises and credit deterioration, not immunity. Following the failure of the Silicon Valley Bank, liquidity discipline among banks has improved, but duration mismatches persist.
In private credit, default rates are trending upward while the asset class has come under continued scrutiny, with negative headlines and a rise in redemptions triggering fund gating at some private credit managers since Q1 2026. Hence, continued monitoring of default rates, redemptions and potential stress events in private credit remains essential. That said, higher rates could buoy medium-term returns and distribution yields in the asset class, as the majority of direct lending loans have a floating-rate structure.
— Ray Heung, Senior Investment Strategist
Most G8 economies have government debt-to-GDP ratios exceeding 100%
Projected government debt-to-GDP ratios, 2026
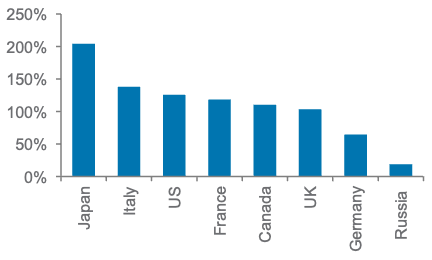
Top client questions (cont’d)
What is your outlook for the US Q3 2026 earnings season, especially for the banking sector?
Our view: We expect another quarter of robust US earnings growth to support our Overweight stance on US equities. We see major US banks, which begin reporting next week, also delivering healthy results, reinforcing our Overweight view on the US financial sector.
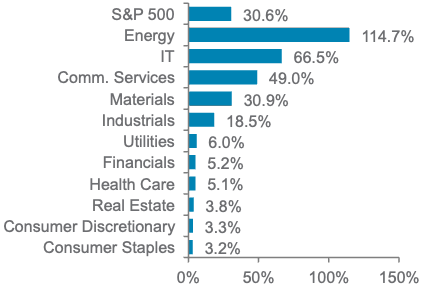
Rationale: Consensus forecasts S&P500 Q3 earnings growth of 30.6% y/y, up from 27.6% at the start of July. Energy is expected to post the strongest growth at 114.7%, supported by elevated oil prices amid ongoing geopolitical tensions. Information technology (66.5%) and communication services (49.0%) remain key earnings drivers, benefiting from sustained AI-related demand and investment. The broader outlook remains supportive, with full-year earnings growth projected at 35.8% in 2026 and 15.6% in 2027.
For banks, the recent underperformance amid concerns over higher long-term bond yields has, in our view, improved the forward-looking risk-reward profile. Over the medium term, strengthening loan growth and resilient credit quality should continue to support solid fundamentals. Capital markets activity also remains constructive, with industry leaders well-positioned to benefit from their strong investment banking and trading franchises.
— Jason Wong, Senior Equity Analyst
Strong US earnings continue to provide support for US equities, with S&P500 estimated earnings growth of 30.6% y/y in Q3 2026
Consensus Q3 earnings growth by sector in the S&P500 Index
How could upcoming semiconductor manufacturing and equipment earnings reshape the AI capex outlook?
Our view: We maintain our AI capex outlook as robust demand and ongoing supply constraints support a multi-year expansion cycle. In the near term, however, we take a more prudent stance on semiconductors amid an expected rise in equity volatility.
Rationale: Recent memory industry guidance points to sustained investment in advanced chip manufacturing, with customer commitments extending through 2031. Upcoming earnings should provide visibility into capacity expansion plans. This supports our AI capex outlook, which we will monitor through the earnings season.
That said, we expect equity volatility to rise in the near term amid elevated long-term yields and macroeconomic uncertainty. Recent media reports on AI lab revenues have also led to doubts over monetisation and the ability to sustain elevated capex spending. We thus took profit on our Global Semiconductors (8.1% return from 9-Sep-26 to 2-Oct-26) and MSCI Taiwan (10.0% return from 9-Jul-26 to 2-Oct-26) Opportunistic ideas following strong performance. This does not reflect a deterioration in fundamentals, but rather a need to be prudent on high-beta exposure. We remain constructive on the AI theme over the long term.
— Ryan Goh, Investment Strategist
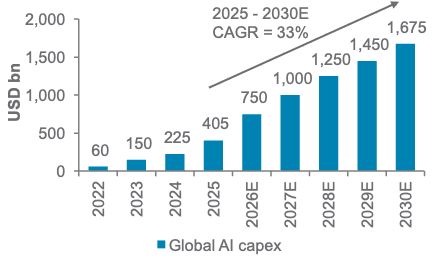
The AI capital expenditure (capex) outlook remains firm, despite near-term market risks from macroeconomic headwinds
Global AI capex is projected to reach USD 1.7trn by 2030
Top client questions (cont’d)
USD/CHF has rebounded sharply over the past two months. What are the key factors behind the move, and do you see the currency pair continuing to move higher?
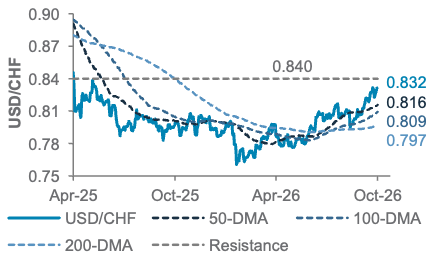
Our view: USD/CHF tested 0.84 amid strong momentum from the USD, but we see the pair remaining supported near-term before gradually moving lower towards 0.82 in three months.
Rationale: The Fed’s relatively high policy rate continues to support USD carry demand, while the Swiss National Bank maintains its policy rate at 0%. In the near term, however, the Swiss franc (CHF) could benefit from increased safe-haven demand amid mounting fiscal concerns in France and political uncertainty in Spain, particularly if European risk premia continue to rise. Beyond these cyclical factors, Switzerland’s substantial net foreign asset position, persistent current account surpluses and low public debt burden continue to underpin the CHF’s structural strength. Over the medium term, we expect the USD’s rate advantage to gradually diminish as the Fed approaches the end of its tightening cycle, while the CHF’s defensive characteristics should remain supportive.
— Vincent Tan, Senior Investment Strategist
— Iris Yuen, Investment Strategist
USD/CHF gains driven by higher US bond yields are likely to be offset by CHF safe-haven demand
USD/CHF and technical indicators
Do you see further upside for USD/JPY after recent dovish comments from BoJ officials and latest bond auctions?
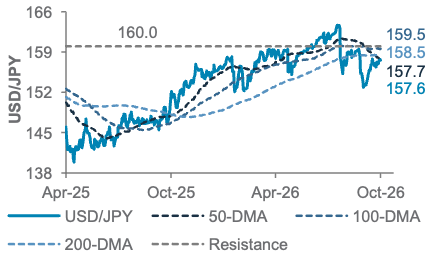
Our view: We see some near-term upside risk to USD/JPY from elevated US yields, but retain our medium-term constructive JPY view. USD/JPY remains below 159, suggesting markets are mindful of intervention risk as the pair approaches 160. We continue to expect further BoJ normalisation.
Rationale: Recent BoJ communication appears less dovish than the market narrative had suggested. BoJ Governor Ueda continues to emphasise the need to anchor underlying inflation around 2% and gradually reduce monetary accommodation, supporting our view that the tightening cycle is not yet over. An October pause would reflect a more measured pace of policy normalisation rather than a change in the BoJ’s policy direction.
Recent Japanese government bond (JGB) auctions have shown resilient demand despite higher yields. At the latest 10-year JGB auction, the bid-to-cover ratio improved to 3.76x from 3.29x previously, while the auction tail (spread between highest accepted yield and issued yield) narrowed to 0.2bps from 1.6bps. We see this asindicative ofan orderly, functioning market rather than a dovish BoJ signal. Intervention concerns around the 160 level should help limit near-term USD/JPY upside.
— Vincent Tan, Senior Investment Strategist
— Iris Yuen, Investment Strategist
USD/JPY upside is likely capped around 160
USD/JPY and technical indicators
Market performance summary*
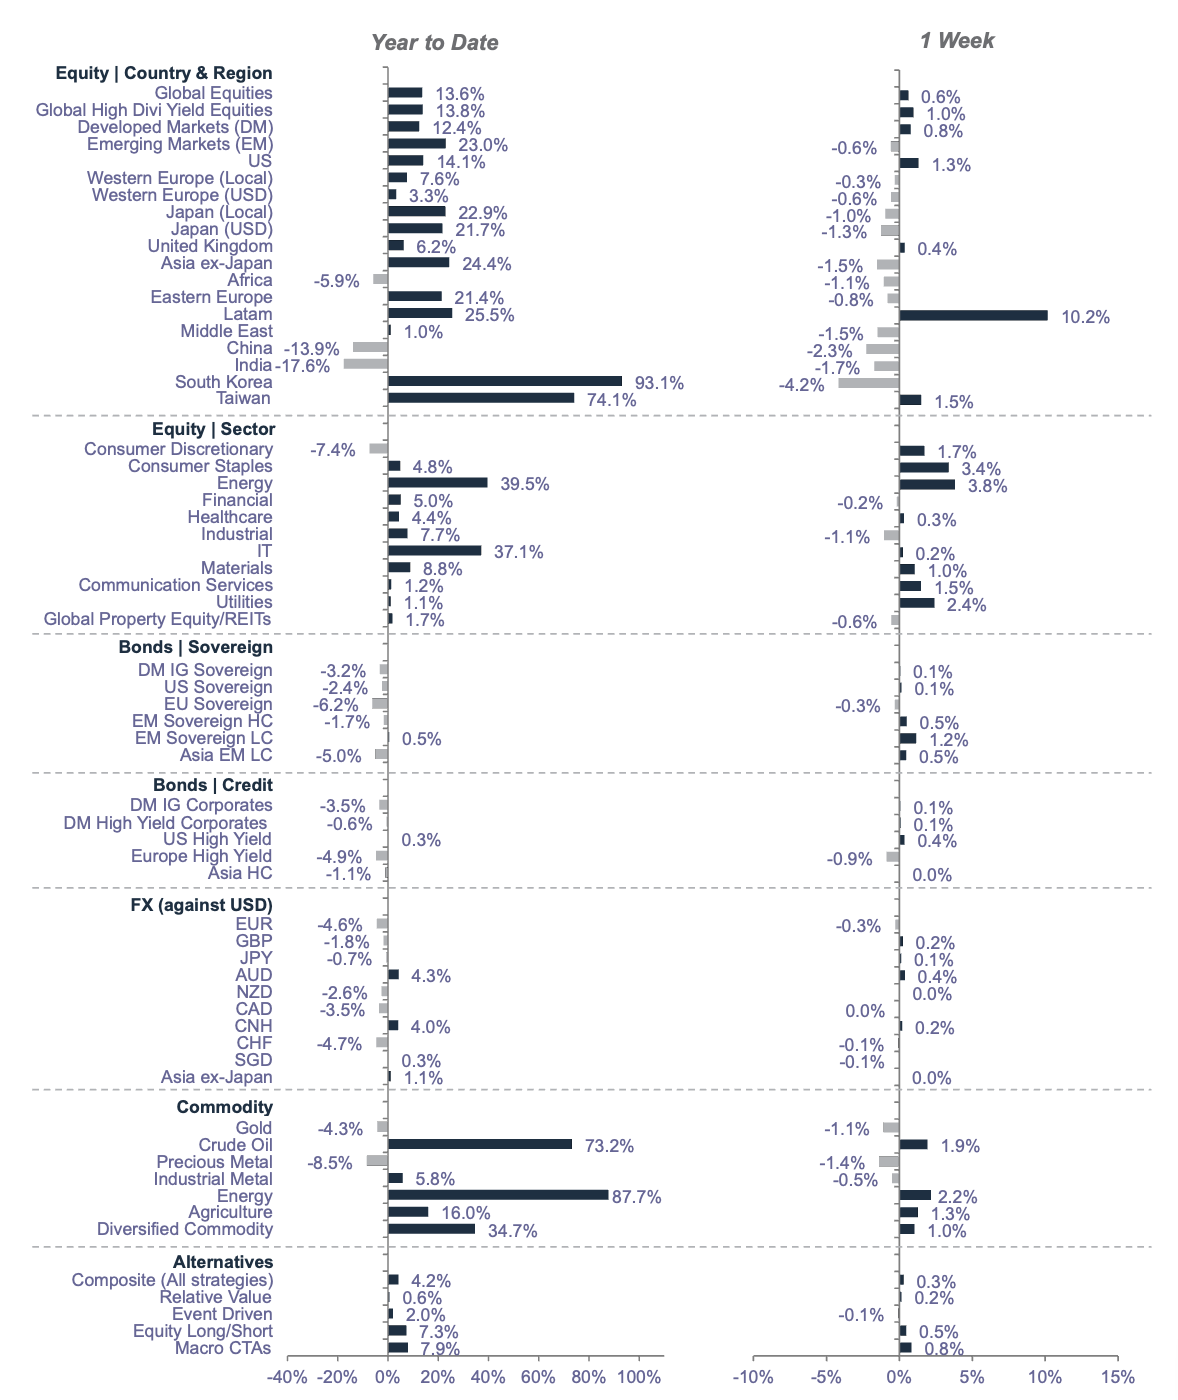
*Performance in USD terms unless otherwise stated, 2026 YTD performance from 31 December 2025 to 8 October 2026; 1-week period: 1 October 2026 to 8 October 2026
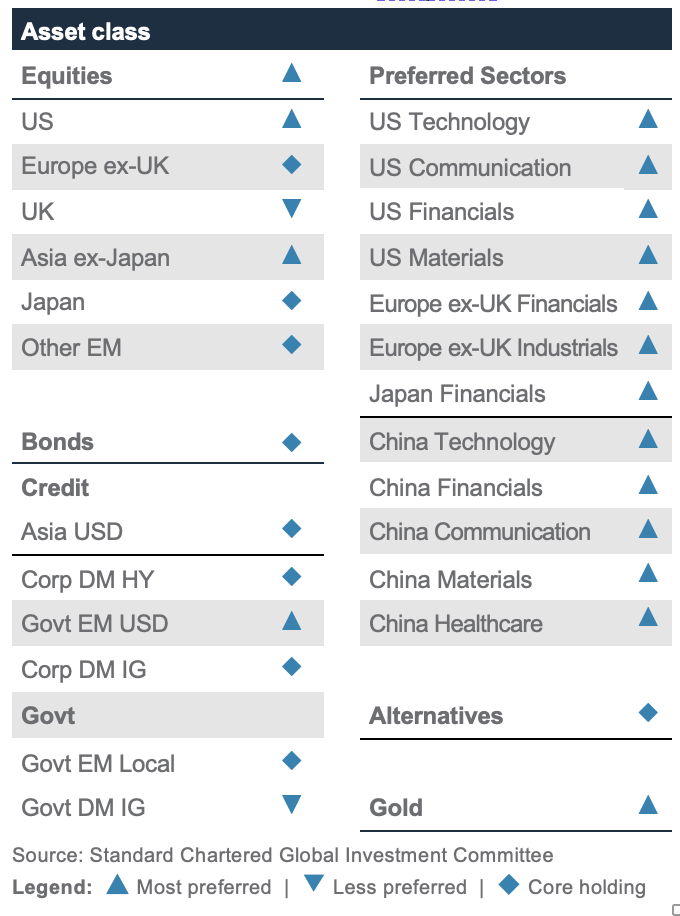
Our 12-month asset class views at a glance
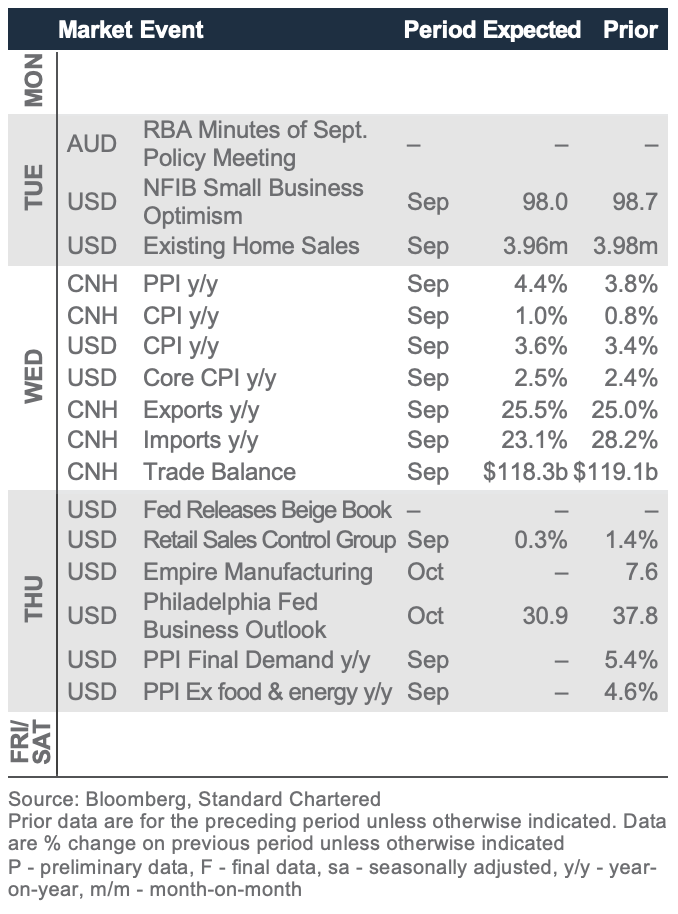
Economic and market calendar
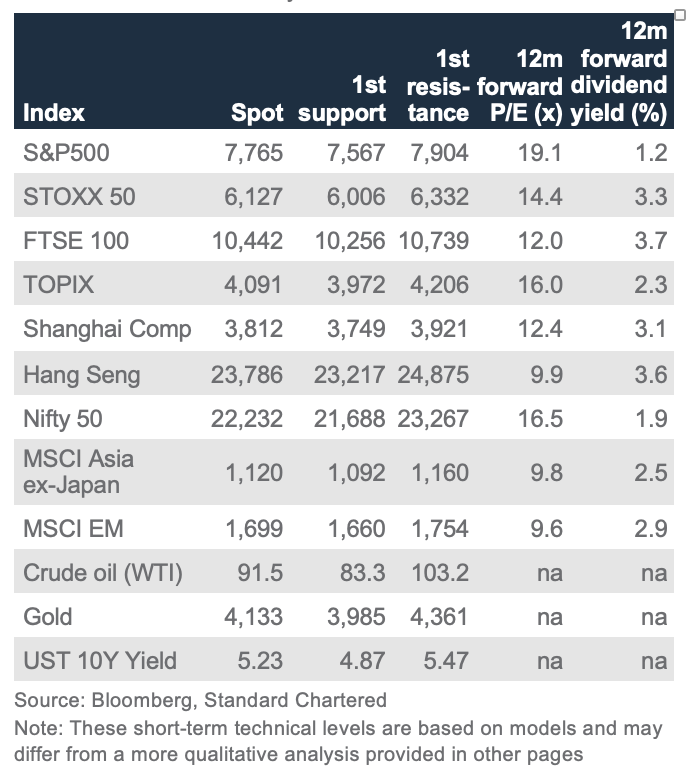
The S&P500 has next interim resistance at 7,904
Technical indicators for key markets as of 8 Oct close
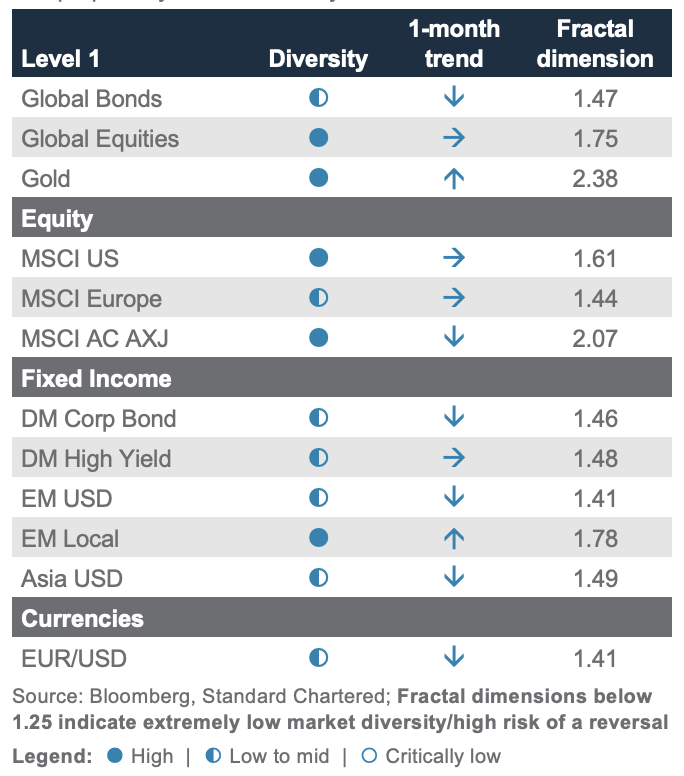
Investor diversity has normalised across asset classes
Our proprietary market diversity indicators as of 8 Oct close
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: This document is being distributed in India by Standard Chartered in its capacity as a distributor of mutual funds and referrer of any other third party financial products. Standard Chartered does not offer any ‘Investment Advice’ as defined in the Securities and Exchange Board of India (Investment Advisers) Regulations, 2013 or otherwise. Services/products related securities business offered by Standard Charted are not intended for any person, who is a resident of any jurisdiction, the laws of which imposes prohibition on soliciting the securities business in that jurisdiction without going through the registration requirements and/or prohibit the use of any information contained in this document. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: In Jersey, Standard Chartered Global Private Bank is the Registered Business Name of the Jersey Branch of Standard Chartered Bank. The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom and all business transacted with Standard Chartered Bank, Jersey Branch and other SC Group Entity outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.