

16 October 2026
Weekly Market View
Staying defensive
and diversified
We turned defensive towards equities two weeks ago. Since then, the Nasdaq-100 index has recorded its biggest weekly decline in three months as September’s hotter-than-expected US inflation report briefly lifted bond yields, tightening financial conditions
We have extended our defensive stance this week, closing our opportunistic bullish Communication Services idea and initiating a bullish idea on Healthcare, where earnings visibility and defensive characteristics appear more attractive.
In fixed income, we see opportunities in the US 10-year government bond. We await clearer AI profit margin and spending guidance, broader earnings growth or lower bond and equity market volatility before turning positive on equities. Until then, diversification and disciplined entry levels remain important.
What are the takeaways from US bank earnings? Are you still positive on Japan banks?
How does the September US inflation report impact your USD and bond views?
Can Big Tech earnings guidance sustain confidence in the AI investment cycle?
Charts of the week: No capitulation
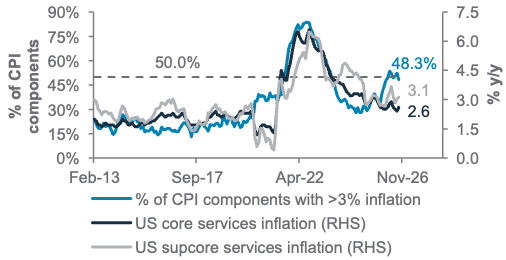
A hotter-than-expected US inflation report triggered a pullback in risk assets, but there are few signs of capitulation so far
US core and supercore inflation; US inflation breadth*
Our ‘Fear and Greed’ indicator
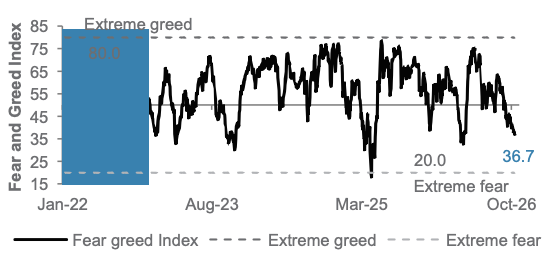
Source: Bloomberg, Standard Chartered; *share of US consumer inflation components rising more than 3%
Editorial
Staying defensive and diversified
Strategy summary: Two weeks ago, we turned defensive towards equities, locking in semiconductor equity gains amid elevated bond volatility, narrowing market breadth and political uncertainty before the US mid-term elections. The near-term outlook reflected a less favourable risk-reward balance. Since we turned defensive, the Nasdaq 100 index has recorded its biggest weekly decline in three months as September’s hotter-than-expected US inflation report briefly lifted bond yields.
We have extended our defensive stance this week, downgrading US Communication Services equities to Neutral and upgrading US Healthcare to Overweight. We also closed our opportunistic bullish Communication Services idea and initiated a bullish idea on Healthcare, where earnings visibility and defensive characteristics appear more attractive. In fixed income, we see opportunities in US 10-year government bonds. We await equity market capitulation, clearer AI profit margins and spending guidance, broader earnings growth or lower bond volatility before turning positive on equities. Until then, diversification and disciplined entry levels remain important.
Hot US inflation triggers equity pullback; not hot enough for an October Fed hike: Risk assets pulled back after September’s hotter-than-expected inflation data (headline 3.7% y/y; core 2.6% y/y). Higher gasoline and diesel prices were the main drivers, but passthrough appeared in airline fares, used cars and transportation services, showing pressures were not confined to energy. Almost half of inflation components are still rising above 3%, a measure recently cited by Fed Chair Warsh. Producer inflation also beat estimates. The reports revive the possibility of an October Fed rate hike, but we expect a divided Fed to weigh it against September’s soft jobs report and narrowly hold this month. A December hike appears more likely if inflation remains firm. Although Fed Chair Warsh did not comment on policy at an IMF speech this week, New York Fed chief Williams said he saw no need to hike in 2027. Our base case remains two further hikes by June 2027.
Limited equity pullback so far. Equities fell sharply after the US inflation report, but the pullback is limited. The Nasdaq 100
is 4.5% below its record high, while the S&P 500 remains close to all-time highs despite the latest decline. The S&P 500 volatility index (VIX) has risen from below 15 to 18.2, still well under the 25–30 range typically associated with capitulation and forced selling. Meanwhile, US government bond volatility (MOVE) remains elevated after surging since September. Our stock-bond quant model turned more negative (-2) this week, signalling elevated equity volatility in the near term.
When to turn more constructive on stocks? We would turn more constructive when capitulation signals align: the Nasdaq 100 approaches a 10% drawdown, the VIX rises to 25–30 and our ‘Fear and Greed’ index enters “extreme fear”. Greater confidence would also require easing concerns about AI spending and technology firms’ exposure to neocloud revenue, lower bond volatility and our stock-bond model turning positive again. Until these conditions emerge, volatility may remain elevated, favouring a defensive equity stance. Political risk should ease after the US mid-term elections. We continue to seek selective opportunities following excessive corrections.
US financials remain a preferred sector after Q3 earnings: US large banks’ earnings were mixed, but underlying trends remain encouraging. Healthy loan and deposit growth supports net interest income, while resilient consumer spending, wealth management activity and a solid M&A and refinancing pipeline strengthen the outlook. Credit risks appear manageable. We remain constructive and favour stronger, diversified franchises.
US government bonds offer value as yields spike: The reversal in US government bond yields after their initial inflation-driven spike suggests limited further upside. The 10-year yield briefly reached 5.32% before slumping as falling equities prompted short-covering. We expect a near-term 5.00–5.25% range and view moves above 5.25% as attractive entry points for our opportunistic 10-year government bond idea. Structural pressures, including term premium and increasing supply to fund fiscal deficits and AI investments, prevent us from turning outright bullish on longer maturities. We, therefore, continue to prefer 3–7-year maturities in broader bond allocations.
— Rajat Bhattacharya and Sundeep Gantori
The weekly macro balance sheet
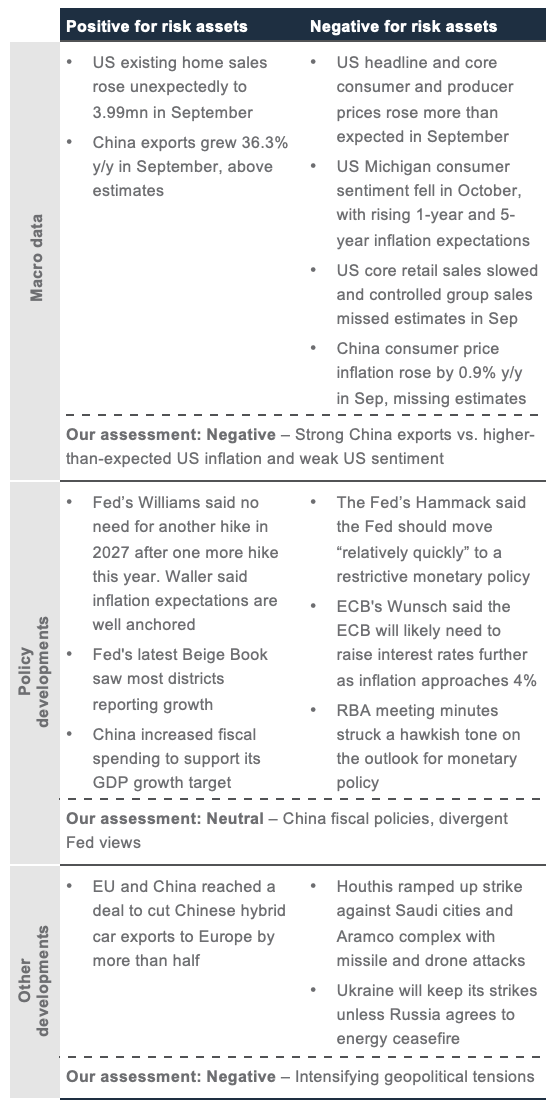
Our weekly net assessment: On balance, we see the past week’s data and policy as negative for risk assets in the near-term
(+) factors: Strong China exports, ramped up fiscal supports
(-)factors: Higher-than-expected US inflation and weak US sentiment; hawkish central banks
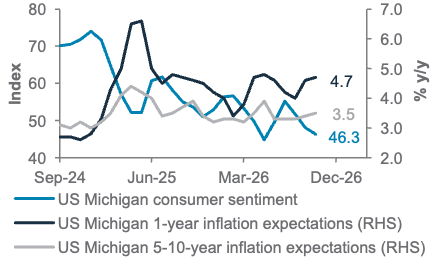
US Michigan consumer sentiment index fell to 46.3 as high prices and borrowing costs continue to weigh on households
US Michigan consumer sentiment, 1-year and 5-10-year inflation expectations
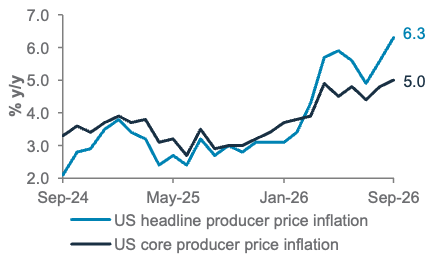
US headline producer price inflation rose to 6.3% y/y, beating estimates and marking its second-highest level since November 2022
US headline and core producer price inflation
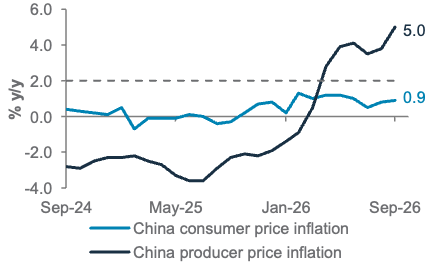
China consumer price inflation missed consensus estimates, while producer prices rose at the fastest pace since June 2022 due to fuel costs
China consumer and producer price inflation
Top client questions
How does the September 2026 US Consumer Price Index (CPI) report alter your view on the USD and bond yields?
Our view: The hotter-than-expected CPI print raises the odds of an October Fed hike, though we still expect a hold followed by a rate hike in December. In the near term, we maintain our view that the US 10-year government bond yield will range between 5.00% and 5.25%, while the USD will remain supported as markets reassess the likelihood of further Fed hikes. Additional gains would depend partly on markets pricing a faster or more prolonged tightening cycle, while clearer signs of an approaching policy rate peak could see the USD ease back.
Rationale: September US consumer inflation came in above consensus across the board – headline CPI rose 3.7% y/y (vs. 3.6% estimate), and core CPI rose 2.6% y/y (vs. 2.5% estimate) – marking the fastest headline acceleration in five months. This shifts the balance of risks modestly hawkish. Unsurprisingly, the market-implied probability of an October Fed hike rose over 50% overnight but closed the day at 32.7% – 9ppt higher than Tuesday’s close.
We believe a split Fed will weigh this inflation report against the soft September jobs report and narrowly vote to keep rates on hold this month. Our base case remains for two more Fed hikes by June 2027. A December rate hike now looks more like a done deal, especially as persistently higher oil prices keep headline and core inflation elevated for at least the next few months. Any re-escalation of the Middle East conflict after the US mid-term elections would exert pressure on the Fed, although we believe Republicans would show greater restraint in US foreign action if they suffer steep Senate losses, which looks increasingly likely.
The intra-day price action in US government bonds was instructive. The US 10-year yield briefly spiked to 5.32% on the print before closing materially lower, as pre-existing bearish positioning was unwound and Fed speakers (Barkin, Goolsbee) stopped well short of signalling an imminent move. This dynamic reinforces our view that the technical selling pressure driving yields towards the upper end of our range is fading. Structural drivers – term premium, fiscal supply concerns and ‘higher for longer’ Fed repricing – remain intact and keep us from turning outright bullish on duration. However, our opportunistic bullish idea in US 10-year government bonds initiated at September-end remains, as we continue to view spikes in US 10-year yields over 5.25% as a good risk-reward entry. From a longer-term portfolio standpoint, we continue to favour the 3-7-year tenor.
On FX, elevated US government bond yields should sustain the USD’s interest rate appeal. However, expected hikes alone will not drive further appreciation. Stronger data or firmer Fed guidance would provide fresh support, while evidence that tightening is nearing completion would temper the USD’s strength.
— Vincent Tan, Senior Investment Strategist
— Ray Heung, Senior Investment Strategist
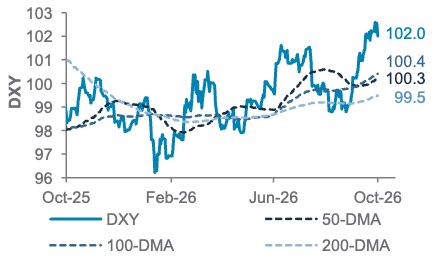
The US Dollar Index (DXY) is likely to stay rangebound between 102 and 103, supported by elevated US government bond yields
The DXY and technicals
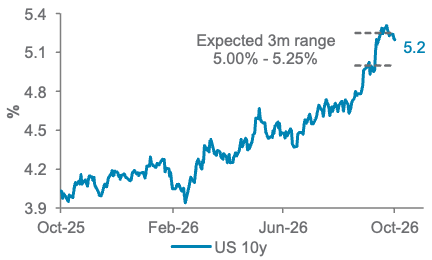
The US 10-year government bond yield spiked initially after the US CPI print, but closed the day lower. We expect the US 10-year yield to stay rangebound within 5.00-5.25% in the near term
US 10-year government bond yield
Top client questions (cont’d)
What are your key takeaways from US bank earnings?
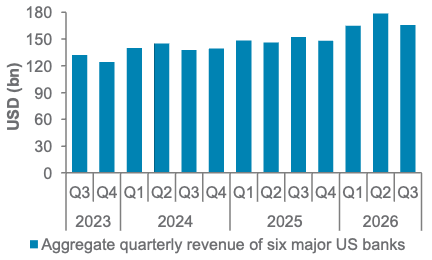
Our view: Q3 2026 earnings results from major US banks have been mixed, but underlying trends remain encouraging. Healthy loan and deposit growth, resilient consumer spending and wealth management activity continue to support the sector. Credit risks remain manageable. We remain constructive on the US financial sector, favouring stronger, diversified franchises.
Rationale: Healthy loan and deposit growth continue to support net interest income (NII), hinting that the US economy remains resilient. Capital markets revenue grew year-on-year (y/y), but moderated sequentially after a very strong Q2 2026, although performance varied across banks. Management commentary points to a healthy deal pipeline, supported by M&A activity and debt refinancing demand, although execution will depend on market conditions.
Provisioning and net charge-off trends were mixed across banks, with no clear signs of broad deterioration in credit quality. Firmer US inflation raises the risk of further monetary tightening. While higher rates can support asset yields, they can also increase funding costs, pressure borrowers and weigh on securities’ valuations. We will continue to monitor lending demand, credit costs, NII trends, capital markets momentum and capital returns.
— Robin Xie, Senior Investment Strategist
US banks’ revenues remain resilient despite moderation from a record-high Q2 2026
Aggregate quarterly revenue (USD bn) of six major US banks
Can Big Tech’s earnings guidance sustain confidence in the AI investment cycle?
Our view: We expect Big Tech’s AI spending to remain elevated, supporting our constructive AI capex outlook. However, we await guidance on the pace of capex growth and the sustainability of profit margins.
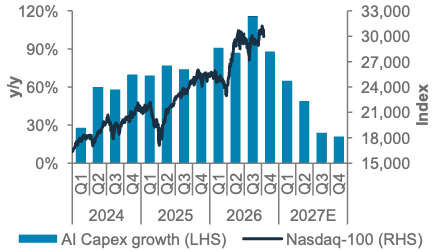
Rationale: Semiconductor leaders’ latest company guidance points to supply constraints extending through 2028, supporting continued capacity expansion for compute. However, while AI capex is still likely to rise, y/y growth is expected to moderate from c.100% in Q3 2026 to c.20% in Q3 2027. This normalisation in growth could raise concerns about the AI investment cycle’s durability.
The Nasdaq-100 Index has rallied alongside accelerating AI capex. Slower capex growth is likely to moderate semiconductor revenue growth, while hyperscalers continue to incur depreciation costs on past investments. The slower growth is already partially reflected in the Nasdaq-100’s valuation de-rating this year. While we remain constructive on the AI investment theme, we prefer to stay prudent in the near term and await Big Tech’s guidance for greater visibility into spending plans in H2 2027 and beyond.
— Ryan Goh, Investment Strategist
AI capital expenditure (capex) growth is expected to moderate to around 20% in Q3 2027
AI capex growth (y/y) vs. the Nasdaq-100 Index
Top client questions (cont’d)
Would France face a credit rating downgrade by rating agencies this month? What might be the market implications?
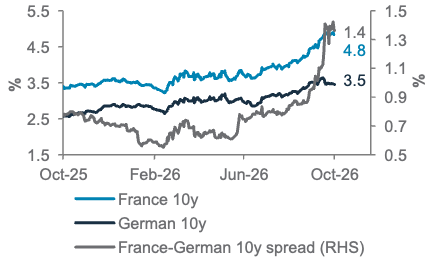
Our view: A rating downgrade is unlikely unless France’s 2027 budget passes the National Assembly very soon with material changes to the proposal. We see French government bond yields remaining elevated relative to German Bund yields.
Rationale: The French National Assembly began debating France’s 2027 draft budget on 13 October 2026, with the first vote scheduled for 20 October. Near-term budget approval appears unlikely, as opposition parties have tabled motions to reject the proposal. The French Parliament has up to 70 days from the budget’s submission to complete the legislative process, although its final adoption and the resolution of political challenges could extend into early 2027.
Last October, two of the three major rating agencies downgraded France by one notch to the high-single-A category with stable outlooks. The remaining agency rated France in the low-AA category with a negative outlook. As negative outlooks are typically resolved within 12-18 months, agencies have time to await fiscal clarity before acting. We believe downgrade risks are largely priced in after the recent rise in yields, but volatility is likely to persist amid fiscal uncertainty and the approaching presidential election. Banks and domestically-focused issuers would face the greatest near-term pressure. However, we would view wider spreads as an opportunity to add exposure, particularly to French banks’ subordinated debt, given their stronger balance sheets and the fact that France contributes less than 50% of major French banks’ overall revenue.
— Ray Heung, Senior Investment Strategist
France’s government bond yields remain elevated amid fiscal and political turmoil
France and Germany’s 10Y government bond yields and the yield spread
Are you still positive on Japanese banks?
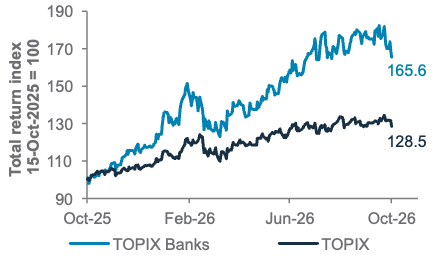
Our view: We are positive on Japanese banks despite the recent market correction, as the structural drivers of improving profitability and shareholder returns remain intact. While political risk and shifting BoJ rate hike odds could sustain near-term volatility, we see the recent pullback as an opportunity to build selective exposure to Japanese bank stocks.
Rationale: Japan’s gradual monetary policy normalisation should support banks’ NII as floating-rate loans reprice and maturing assets are reinvested at higher yields. Healthy corporate lending demand, improving capital efficiency and continued share buybacks provide further support. While uncertainty over the pace of BoJ tightening could weigh on sentiment, we see gradual interest rate normalisation as supportive of medium-term bank profitability.
Key risks include rising deposit costs, mark-to-market losses on bond portfolios and a disorderly increase in Japanese government bond yields. We continue to favour well-capitalised banks with strong domestic deposit franchises and improving returns on equity.
— Robin Xie, Senior Investment Strategist
Japanese banks’ longer-term outperformance puts recent volatility in perspective
TOPIX Banks vs. TOPIX performance (rebased to 100)
Top client questions (cont’d)
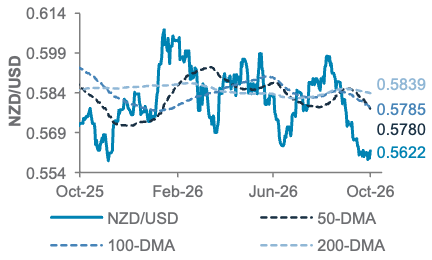
Could NZD/USD rebound from its one-year trough? If so, how far could it recover?
Our view: New Zealand’s improving domestic conditions, persistent inflation and technical support provide a basis for NZD/USD’s initial recovery towards the 0.57 level, although elevated US bond yields could slow its progress.
Rationale: In Q3, New Zealand’s seasonally-adjusted business confidence reading rose to a net 40% of firms expecting the economy to improve, up from net 14% in Q2. Hiring intentions improved, and filled jobs rose 0.2% m/m in August. These developments suggest domestic conditions remain supportive for the NZD.
New Zealand’s above-target inflation keeps further RBNZ tightening in focus. The 22 October consumer inflation data release and the 28 October RBNZ policy meeting are key catalysts: persistent price pressures and improving demand are expected to prompt firmer policy guidance and strengthen the NZD’s interest-rate appeal.
NZD/USD’s position near the lower boundary of its downtrend channel suggests scope for a technical rebound. We see 0.57 as the first recovery hurdle; a sustained break above this level would strengthen the case for further gains. Firmer US consumer inflation remains a headwind, making a gradual recovery more plausible than a sharp reversal.
— Vincent Tan, Senior Investment Strategist
— Iris Yuen, Investment Strategist
NZD/USD is likely to rebound towards near-term resistance at 0.57
NZD/USD and technical indicators
Can the proposed Russia-Ukraine ‘energy ceasefire’ contain oil prices as Middle East risks rise?
Our view: We expect escalating Middle East tensions to keep oil prices elevated. We maintain our three- and 12-month West Texas Intermediate (WTI) oil price forecasts at USD 100/bbl and USD 80/bbl, respectively, and continue to favour US Treasury Inflation-Protected Securities (TIPS) as a portfolio hedge against persistent inflation risks.
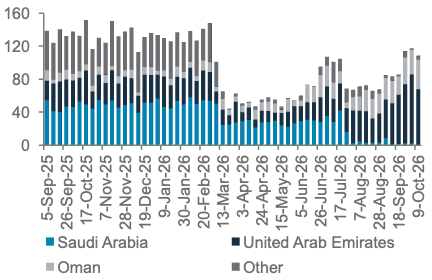
Rationale: The proposed Russia-Ukraine ‘energy ceasefire’ still looks some way off. In our view, even if an agreement is reached, it would do little to ease the supply risks building in the Middle East. Gulf oil exports have recovered to above 80% of pre-conflict levels in recent weeks, helping moderate the pace of price increases. However, the recovery remains vulnerable to disruptions, particularly following the latest Houthi attacks on Saudi energy infrastructure. Diesel and jet fuel remain under the most pressure, with Gulf exports of these fuels in September at only around 60% of pre-conflict levels. A sustained disruption to major Saudi production or export infrastructure remains the principal upside risk to oil prices.
— Anthony Naab, Investment Strategist
Robust Gulf oil exports are tempering oil price pressures, but supply risks should sustain a geopolitical risk premium
Weekly Gulf oil exports by source – September 2025 to date
Market performance summary*
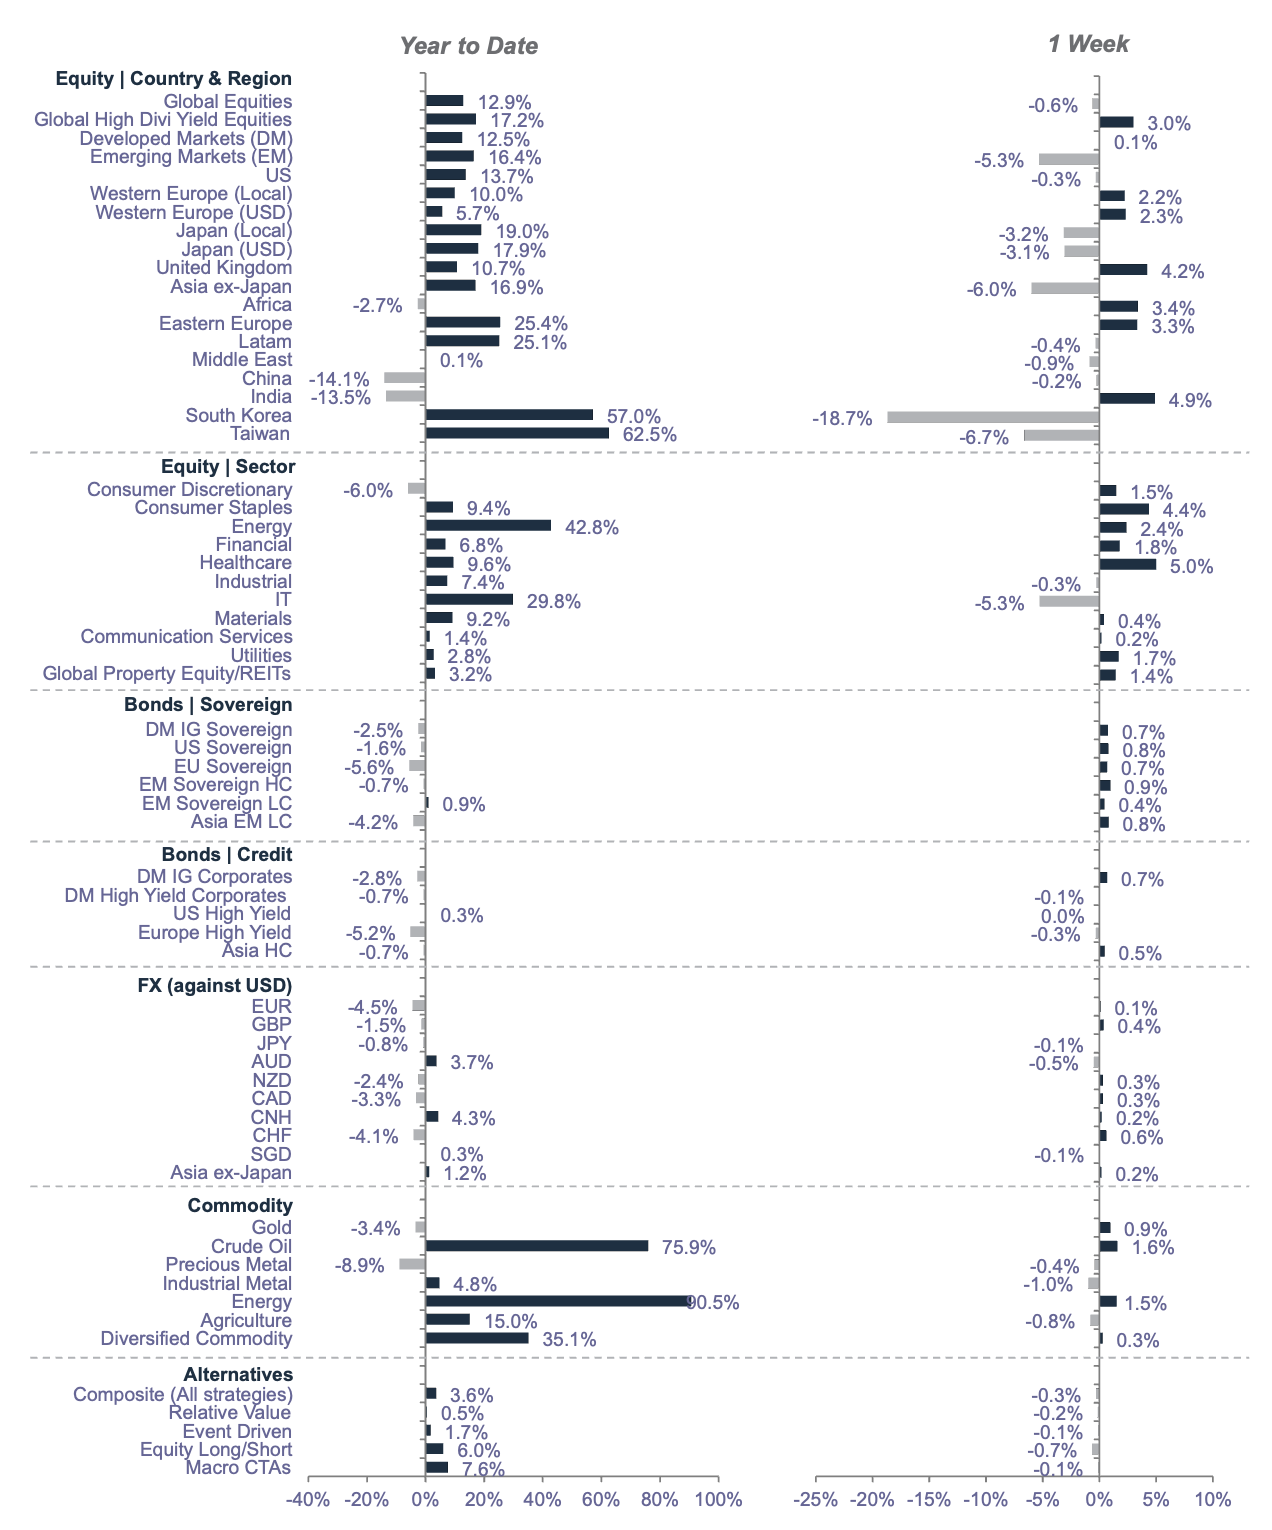
*Performance in USD terms unless otherwise stated, 2026 YTD performance from 31 December 2025 to 15 October 2026; 1-week period: 8 October 2026 to 15 October 2026
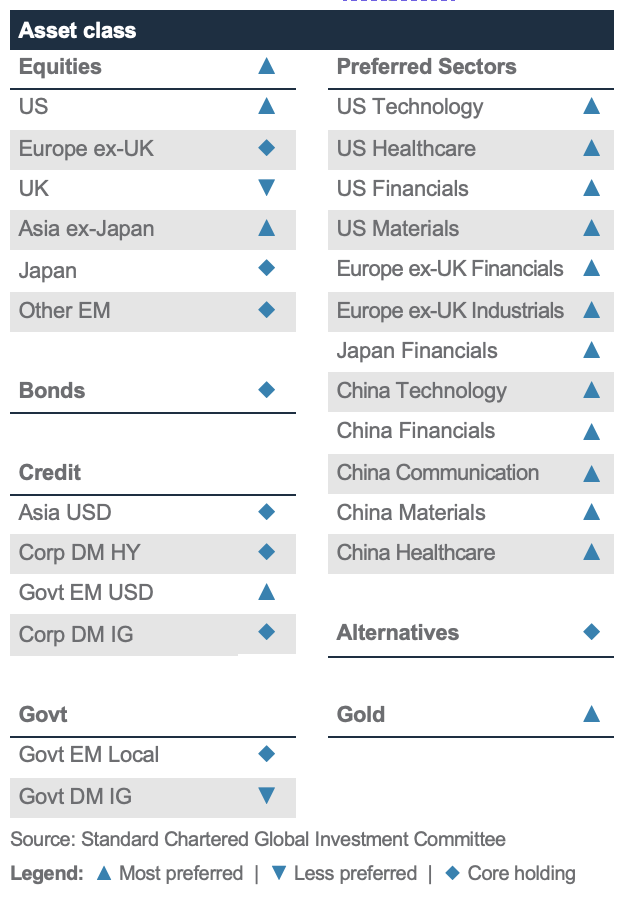
Our 12-month asset class views at a glance
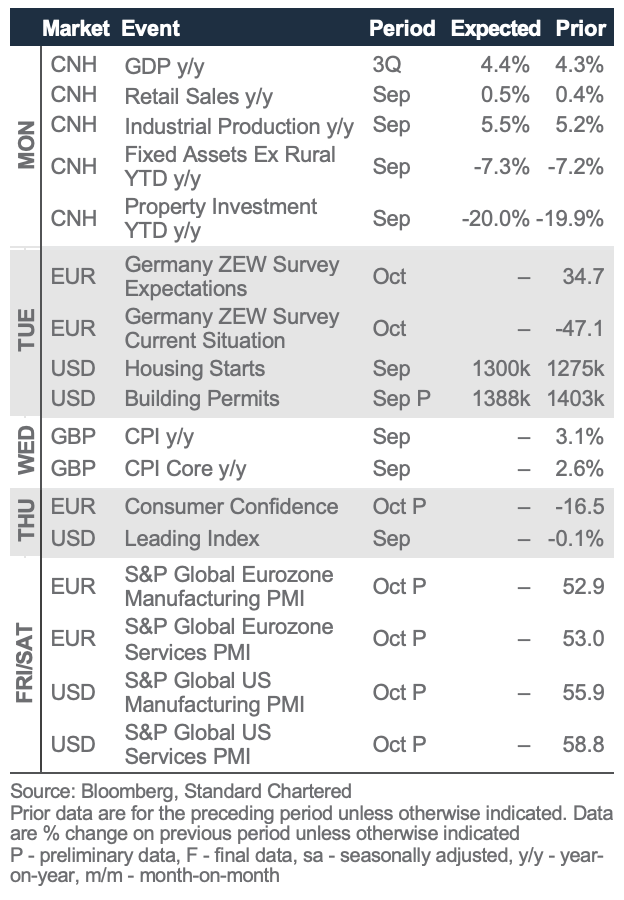
Economic and market calendar
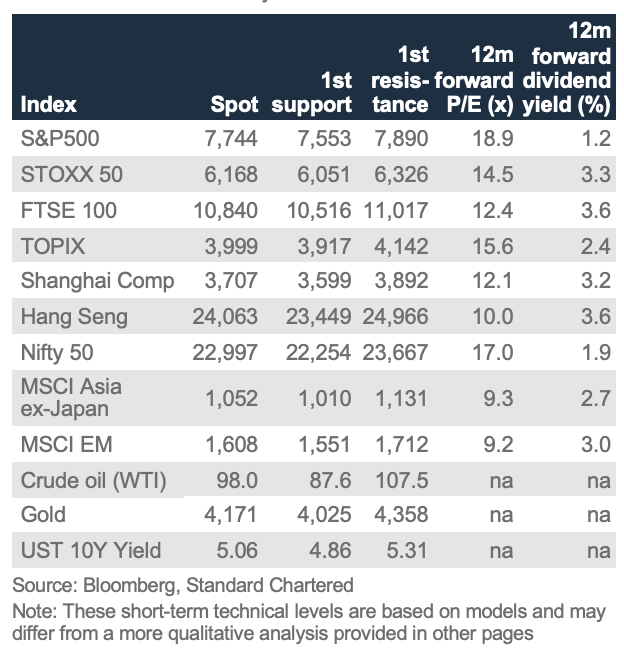
The S&P500 has next interim resistance at 7,890
Technical indicators for key markets as of 15 Oct close
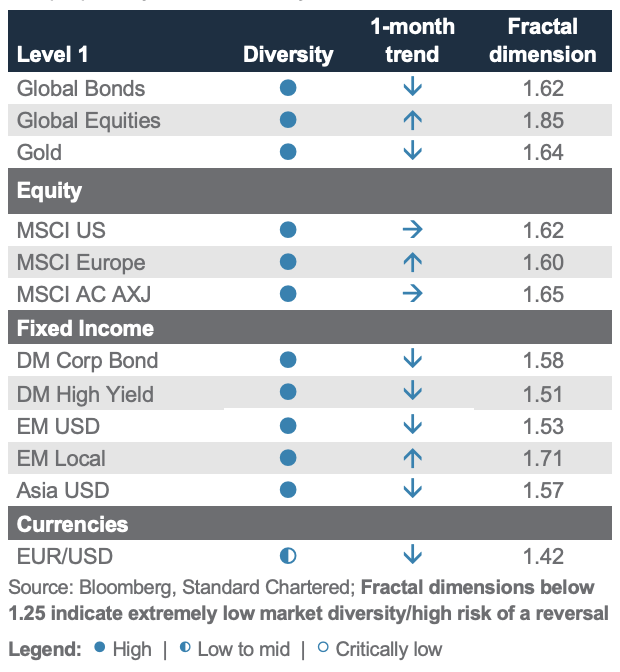
Investor diversity has normalised across asset classes
Our proprietary market diversity indicators as of 15 Oct close
Disclosure
This document is confidential and may also be privileged. If you are not the intended recipient, please destroy all copies and notify the sender immediately. This document is being distributed for general information only and is subject to the relevant disclaimers available at our Standard Chartered website under Regulatory disclosures. It is not and does not constitute research material, independent research, an offer, recommendation or solicitation to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This document is for general evaluation only. It does not take into account the specific investment objectives, financial situation or particular needs of any particular person or class of persons and it has not been prepared for any particular person or class of persons. You should not rely on any contents of this document in making any investment decisions. Before making any investment, you should carefully read the relevant offering documents and seek independent legal, tax and regulatory advice. In particular, we recommend you to seek advice regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs, before you make a commitment to purchase the investment product. Opinions, projections and estimates are solely those of SC at the date of this document and subject to change without notice. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. The value of investments, and the income from them, can go down as well as up, and you may not recover the amount of your original investment. You are not certain to make a profit and may lose money. Any forecast contained herein as to likely future movements in rates or prices or likely future events or occurrences constitutes an opinion only and is not indicative of actual future movements in rates or prices or actual future events or occurrences (as the case may be). This document must not be forwarded or otherwise made available to any other person without the express written consent of the Standard Chartered Group (as defined below). Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered PLC, the ultimate parent company of Standard Chartered Bank, together with its subsidiaries and affiliates (including each branch or representative office), form the Standard Chartered Group. Standard Chartered Global Private Bank is the private banking division of Standard Chartered. Private banking activities may be carried out internationally by different legal entities and affiliates within the Standard Chartered Group (each an “SC Group Entity”) according to local regulatory requirements. Not all products and services are provided by all branches, subsidiaries and affiliates within the Standard Chartered Group. Some of the SC Group Entities only act as representatives of Standard Chartered Global Private Bank and may not be able to offer products and services or offer advice to clients.
Copyright © 2026, Accounting Research & Analytics, LLC d/b/a CFRA (and its affiliates, as applicable). Reproduction of content provided by CFRA in any form is prohibited except with the prior written permission of CFRA. CFRA content is not investment advice and a reference to or observation concerning a security or investment provided in the CFRA SERVICES is not a recommendation to buy, sell or hold such investment or security or make any other investment decisions. The CFRA content contains opinions of CFRA based upon publicly-available information that CFRA believes to be reliable and the opinions are subject to change without notice. This analysis has not been submitted to, nor received approval from, the United States Securities and Exchange Commission or any other regulatory body. While CFRA exercised due care in compiling this analysis, CFRA, ITS THIRD-PARTY SUPPLIERS, AND ALL RELATED ENTITIES SPECIFICALLY DISCLAIM ALL WARRANTIES, EXPRESS OR IMPLIED, INCLUDING, BUT NOT LIMITED TO, ANY WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, to the full extent permitted by law, regarding the accuracy, completeness, or usefulness of this information and assumes no liability with respect to the consequences of relying on this information for investment or other purposes. No content provided by CFRA (including ratings, credit-related analyses and data, valuations, model, software or other application or output therefrom) or any part thereof may be modified, reverse engineered, reproduced or distributed in any form by any means, or stored in a database or retrieval system, without the prior written permission of CFRA, and such content shall not be used for any unlawful or unauthorized purposes. CFRA and any third-party providers, as well as their directors, officers, shareholders, employees or agents do not guarantee the accuracy, completeness, timeliness or availability of such content. In no event shall CFRA, its affiliates, or their third-party suppliers be liable for any direct, indirect, special, or consequential damages, costs, expenses, legal fees, or losses (including lost income or lost profit and opportunity costs) in connection with a subscriber’s, subscriber’s customer’s, or other’s use of CFRA’s content.
Market Abuse Regulation (MAR) Disclaimer
Banking activities may be carried out internationally by different branches, subsidiaries and affiliates within the Standard Chartered Group according to local regulatory requirements. Opinions may contain outright “buy”, “sell”, “hold” or other opinions. The time horizon of this opinion is dependent on prevailing market conditions and there is no planned frequency for updates to the opinion. This opinion is not independent of Standard Chartered Group’s trading strategies or positions. Standard Chartered Group and/or its affiliates or its respective officers, directors, employee benefit programmes or employees, including persons involved in the preparation or issuance of this document may at any time, to the extent permitted by applicable law and/or regulation, be long or short any securities or financial instruments referred to in this document or have material interest in any such securities or related investments. Therefore, it is possible, and you should assume, that Standard Chartered Group has a material interest in one or more of the financial instruments mentioned herein. Please refer to our Standard Chartered website under Regulatory disclosures for more detailed disclosures, including past opinions/ recommendations in the last 12 months and conflict of interests, as well as disclaimers. A covering strategist may have a financial interest in the debt or equity securities of this company/issuer. All covering strategist are licensed to provide investment recommendations under Monetary Authority of Singapore or Hong Kong Monetary Authority. This document must not be forwarded or otherwise made available to any other person without the express written consent of Standard Chartered Group.
Sustainable Investments
Any ESG data used or referred to has been provided by Morningstar, Sustainalytics, MSCI or Bloomberg. Refer to 1) Morningstar website under Sustainable Investing, 2) Sustainalytics website under ESG Risk Ratings, 3) MCSI website under ESG Business Involvement Screening Research and 4) Bloomberg green, social & sustainability bonds guide for more information. The ESG data is as at the date of publication based on data provided, is for informational purpose only and is not warranted to be complete, timely, accurate or suitable for a particular purpose, and it may be subject to change. The ESG data providers may not provide data coverage of all companies or securities in our Sustainable Investment Universe or Fund Select funds. As a result, a small subset of companies or securities will not be in scope for exclusionary screening. Sustainable Investments (SI): This refers to funds that have been classified as ‘ESG Intentional Investments – Overall’ by Morningstar. SI funds have explicitly stated in their prospectus and regulatory filings that they either incorporate ESG factors into the investment process or have a thematic focus on the environment, gender diversity, low carbon, renewable energy, water or community development. For equity, it refers to shares/stocks issued by companies with Sustainalytics ESG Risk Rating of Low/Negligible. For bonds, it refers to debt instruments issued by issuers with Sustainalytics ESG Risk Rating of Low/Negligible, and/or those being certified green, social, sustainable bonds by Bloomberg. For structured products, it refers to products that are issued by any issuer who has a Sustainable Finance framework that aligns with Standard Chartered’s Green and Sustainable Product Framework, with underlying assets that are part of the Sustainable Investment universe or separately approved by Standard Chartered’s Sustainable Finance Governance Committee. Sustainalytics ESG risk ratings shown are factual and are not an indicator that the product is classified or marketed as “green”, “sustainable” or similar under any particular classification system or framework.
Shariah (“Shariah Compliant or Shariah Compliance”)
For any reason to enter only into transactions which comply or are consistent with the principles of the Shariah, the client certifies that he/she/it has made his /her/its own investigation into and satisfied itself as to the Shariah compliance of the Islamic security and all necessary action to confirm that the Islamic security is Shariah compliant has been taken (including the obtaining of a fatwa, where required) and the Client will not claim any dispute on the grounds of any lack of Shariah compliance of these investments. The Client has not relied on Standard Chartered Group or any written declaration, fatwa, opinion or other documents prepared by, on behalf or at the request of Standard Chartered Group for the purposes of a determination or confirmation that these instruments are Shariah compliant.
Country/Market Specific Disclosures
Bahrain: This document is being distributed in Bahrain by Standard Chartered Bank, Bahrain Branch, having its address at P.O. 29, Manama, Kingdom of Bahrain, is a branch of Standard Chartered Bank and is licensed by the Central Bank of Bahrain as a conventional retail bank. Botswana: This document is being distributed in Botswana by, and is attributable to, Standard Chartered Bank Botswana Limited which is a financial institution licensed under the Section 6 of the Banking Act CAP 46.04 and is listed in the Botswana Stock Exchange. Brunei Darussalam: This document is being distributed in Brunei Darussalam by, and is attributable to, Standard Chartered Bank (Brunei Branch) | Registration Number RFC/61 and Standard Chartered Securities (B) Sdn Bhd | Registration Number RC20001003. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18. Standard Chartered Securities (B) Sdn Bhd is a limited liability company registered with the Registry of Companies with Registration Number RC20001003 and licensed by Brunei Darussalam Central Bank as a Capital Markets Service License Holder with License Number BDCB/R/CMU/S3-CL and it is authorised to conduct Islamic investment business through an Islamic window. China Mainland: This document is being distributed in China by, and is attributable to, Standard Chartered Bank (China) Limited which is mainly regulated by National Financial Regulatory Administration (NFRA), State Administration of Foreign Exchange (SAFE), and People’s Bank of China (PBOC). Hong Kong: In Hong Kong, this document, except for any portion advising on or facilitating any decision on futures contracts trading, is distributed by Standard Chartered Bank (Hong Kong) Limited (“SCBHK”), a subsidiary of Standard Chartered PLC. SCBHK has its registered address at 32/F, Standard Chartered Bank Building, 4-4A Des Voeux Road Central, Hong Kong and is regulated by the Hong Kong Monetary Authority and registered with the Securities and Futures Commission (“SFC”) to carry on Type 1 (dealing in securities), Type 4 (advising on securities), Type 6 (advising on corporate finance) and Type 9 (asset management) regulated activity under the Securities and Futures Ordinance (Cap. 571) (“SFO”) (CE No. AJI614). The contents of this document have not been reviewed by any regulatory authority in Hong Kong and you are advised to exercise caution in relation to any offer set out herein. If you are in doubt about any of the contents of this document, you should obtain independent professional advice. Any product named herein may not be offered or sold in Hong Kong by means of any document at any time other than to “professional investors” as defined in the SFO and any rules made under that ordinance. In addition, this document may not be issued or possessed for the purposes of issue, whether in Hong Kong or elsewhere, and any interests may not be disposed of, to any person unless such person is outside Hong Kong or is a “professional investor” as defined in the SFO and any rules made under that ordinance, or as otherwise may be permitted by that ordinance. In Hong Kong, Standard Chartered Global Private Bank is the private banking division of SCBHK, a subsidiary of Standard Chartered PLC. Ghana: Standard Chartered Bank Ghana Limited accepts no liability and will not be liable for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. Past performance is not indicative of future results and no representation or warranty is made regarding future performance. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to feedback.ghana@sc.com. Please do not reply to this email. Call our Priority Banking on 0302610750 for any questions or service queries. You are advised not to send any confidential and/or important information to Standard Chartered via e-mail, as Standard Chartered makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Standard Chartered shall not be responsible for any loss or damage suffered by you arising from your decision to use e-mail to communicate with the Bank. India: This document is being distributed in India by Standard Chartered in its capacity as a distributor of mutual funds and referrer of any other third party financial products. Standard Chartered does not offer any ‘Investment Advice’ as defined in the Securities and Exchange Board of India (Investment Advisers) Regulations, 2013 or otherwise. Services/products related securities business offered by Standard Charted are not intended for any person, who is a resident of any jurisdiction, the laws of which imposes prohibition on soliciting the securities business in that jurisdiction without going through the registration requirements and/or prohibit the use of any information contained in this document. Indonesia: This document is being distributed in Indonesia by Standard Chartered Bank, Indonesia branch, which is a financial institution licensed and supervised by Otoritas Jasa Keuangan (Financial Service Authority) and Bank Indonesia. Jersey: In Jersey, Standard Chartered Global Private Bank is the Registered Business Name of the Jersey Branch of Standard Chartered Bank. The Jersey Branch of Standard Chartered Bank is regulated by the Jersey Financial Services Commission. Copies of the latest audited accounts of Standard Chartered Bank are available from its principal place of business in Jersey: PO Box 80, 15 Castle Street, St Helier, Jersey JE4 8PT. Standard Chartered Bank is incorporated in England with limited liability by Royal Charter in 1853 Reference Number ZC 18. The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. The Jersey Branch of Standard Chartered Bank is also an authorised financial services provider under license number 44946 issued by the Financial Sector Conduct Authority of the Republic of South Africa. Jersey is not part of the United Kingdom and all business transacted with Standard Chartered Bank, Jersey Branch and other SC Group Entity outside of the United Kingdom, are not subject to some or any of the investor protection and compensation schemes available under United Kingdom law. Kenya: This document is being distributed in Kenya by and is attributable to Standard Chartered Bank Kenya Limited. Investment Products and Services are distributed by Standard Chartered Investment Services Limited, a wholly owned subsidiary of Standard Chartered Bank Kenya Limited that is licensed by the Capital Markets Authority in Kenya, as a Fund Manager. Standard Chartered Bank Kenya Limited is regulated by the Central Bank of Kenya. Malaysia: This document is being distributed in Malaysia by Standard Chartered Bank Malaysia Berhad (“SCBMB”). Recipients in Malaysia should contact SCBMB in relation to any matters arising from, or in connection with, this document. This document has not been reviewed by the Securities Commission Malaysia. The product lodgement, registration, submission or approval by the Securities Commission of Malaysia does not amount to nor indicate recommendation or endorsement of the product, service or promotional activity. Investment products are not deposits and are not obligations of, not guaranteed by, and not protected by SCBMB or any of the affiliates or subsidiaries, or by Perbadanan Insurans Deposit Malaysia, any government or insurance agency. Investment products are subject to investment risks, including the possible loss of the principal amount invested. SCBMB expressly disclaim any liability and responsibility for any loss arising directly or indirectly (including special, incidental or consequential loss or damage) arising from the financial losses of the Investment Products due to market condition. Nigeria: This document is being distributed in Nigeria by Standard Chartered Bank Nigeria Limited (SCB Nigeria), a bank duly licensed and regulated by the Central Bank of Nigeria. SCB Nigeria accepts no liability for any loss or damage arising directly or indirectly (including special, incidental or consequential loss or damage) from your use of these documents. You should seek advice from a financial adviser on the suitability of an investment for you, taking into account these factors before making a commitment to invest in an investment. To unsubscribe from receiving further updates, please send an email to clientcare.ng@sc.com requesting to be removed from our mailing list. Please do not reply to this email. Call our Priority Banking on 02 012772514 for any questions or service queries. SCB Nigeria shall not be responsible for any loss or damage arising from your decision to send confidential and/or important information to Standard Chartered via e-mail. SCB Nigeria makes no representations or warranties as to the security or accuracy of any information transmitted via e-mail. Pakistan: This document is being distributed in Pakistan by, and attributable to Standard Chartered Bank (Pakistan) Limited having its registered office at PO Box 5556, I.I Chundrigar Road Karachi, which is a banking company registered with State Bank of Pakistan under Banking Companies Ordinance 1962 and is also having licensed issued by Securities & Exchange Commission of Pakistan for Security Advisors. Standard Chartered Bank (Pakistan) Limited acts as a distributor of mutual funds and referrer of other third-party financial products. Singapore: This document is being distributed in Singapore by, and is attributable to, Standard Chartered Bank (Singapore) Limited (Registration No. 201224747C/ GST Group Registration No. MR-8500053-0, “SCBSL”). Recipients in Singapore should contact SCBSL in relation to any matters arising from, or in connection with, this document. SCBSL is an indirect wholly owned subsidiary of Standard Chartered Bank and is licensed to conduct banking business in Singapore under the Singapore Banking Act, 1970. Standard Chartered Global Private Bank is the private banking division of SCBSL. IN RELATION TO ANY SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT REFERRED TO IN THIS DOCUMENT, THIS DOCUMENT, TOGETHER WITH THE ISSUER DOCUMENTATION, SHALL BE DEEMED AN INFORMATION MEMORANDUM (AS DEFINED IN SECTION 275 OF THE SECURITIES AND FUTURES ACT, 2001 (“SFA”)). THIS DOCUMENT IS INTENDED FOR DISTRIBUTION TO ACCREDITED INVESTORS, AS DEFINED IN SECTION 4A(1)(a) OF THE SFA, OR ON THE BASIS THAT THE SECURITY OR SECURITIES-BASED DERIVATIVES CONTRACT MAY ONLY BE ACQUIRED AT A CONSIDERATION OF NOT LESS THAN S$200,000 (OR ITS EQUIVALENT IN A FOREIGN CURRENCY) FOR EACH TRANSACTION. Further, in relation to any security or securities-based derivatives contract, neither this document nor the Issuer Documentation has been registered as a prospectus with the Monetary Authority of Singapore under the SFA. Accordingly, this document and any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the product may not be circulated or distributed, nor may the product be offered or sold, or be made the subject of an invitation for subscription or purchase, whether directly or indirectly, to persons other than a relevant person pursuant to section 275(1) of the SFA, or any person pursuant to section 275(1A) of the SFA, and in accordance with the conditions specified in section 275 of the SFA, or pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. In relation to any collective investment schemes referred to in this document, this document is for general information purposes only and is not an offering document or prospectus (as defined in the SFA). This document is not, nor is it intended to be (i) an offer or solicitation of an offer to buy or sell any capital markets product; or (ii) an advertisement of an offer or intended offer of any capital markets product. Deposit Insurance Scheme: Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured. This advertisement has not been reviewed by the Monetary Authority of Singapore. Taiwan: SC Group Entity or Standard Chartered Bank (Taiwan) Limited (“SCB (Taiwan)”) may be involved in the financial instruments contained herein or other related financial instruments. The author of this document may have discussed the information contained herein with other employees or agents of SC or SCB (Taiwan). The author and the above-mentioned employees of SC or SCB (Taiwan) may have taken related actions in respect of the information involved (including communication with customers of SC or SCB (Taiwan) as to the information contained herein). The opinions contained in this document may change, or differ from the opinions of employees of SC or SCB (Taiwan). SC and SCB (Taiwan) will not provide any notice of any changes to or differences between the above-mentioned opinions. This document may cover companies with which SC or SCB (Taiwan) seeks to do business at times and issuers of financial instruments. Therefore, investors should understand that the information contained herein may serve as specific purposes as a result of conflict of interests of SC or SCB (Taiwan). SC, SCB (Taiwan), the employees (including those who have discussions with the author) or customers of SC or SCB (Taiwan) may have an interest in the products, related financial instruments or related derivative financial products contained herein; invest in those products at various prices and on different market conditions; have different or conflicting interests in those products. The potential impacts include market makers’ related activities, such as dealing, investment, acting as agents, or performing financial or consulting services in relation to any of the products referred to in this document. UAE: DIFC – Standard Chartered Bank is incorporated in England with limited liability by Royal Charter 1853 Reference Number ZC18.The Principal Office of the Company is situated in England at 1 Basinghall Avenue, London, EC2V 5DD. Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. Standard Chartered Bank, Dubai International Financial Centre having its offices at Dubai International Financial Centre, Building 1, Gate Precinct, P.O. Box 999, Dubai, UAE is a branch of Standard Chartered Bank and is regulated by the Dubai Financial Services Authority (“DFSA”). This document is intended for use only by Professional Clients and is not directed at Retail Clients as defined by the DFSA Rulebook. In the DIFC we are authorised to provide financial services only to clients who qualify as Professional Clients and Market Counterparties and not to Retail Clients. As a Professional Client you will not be given the higher retail client protection and compensation rights and if you use your right to be classified as a Retail Client we will be unable to provide financial services and products to you as we do not hold the required license to undertake such activities. For Islamic transactions, we are acting under the supervision of our Shariah Supervisory Committee. Relevant information on our Shariah Supervisory Committee is currently available on the Standard Chartered Bank website in the Islamic banking section. For residents of the UAE – Standard Chartered UAE (“SC UAE”) is licensed by the Central Bank of the U.A.E. SC UAE is licensed by Securities and Commodities Authority to practice Promotion Activity. SC UAE does not provide financial analysis or consultation services in or into the UAE within the meaning of UAE Securities and Commodities Authority Decision No. 48/r of 2008 concerning financial consultation and financial analysis. Uganda: Our Investment products and services are distributed by Standard Chartered Bank Uganda Limited, which is licensed by the Capital Markets Authority as an investment adviser. United Kingdom: In the UK, Standard Chartered Bank is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and Prudential Regulation Authority. This communication has been approved by Standard Chartered Bank for the purposes of Section 21 (2) (b) of the United Kingdom’s Financial Services and Markets Act 2000 (“FSMA”) as amended in 2010 and 2012 only. Standard Chartered Bank (trading as Standard Chartered Global Private Bank) is also an authorised financial services provider (license number 45747) in terms of the South African Financial Advisory and Intermediary Services Act, 2002. The Materials have not been prepared in accordance with UK legal requirements designed to promote the independence of investment research, and that it is not subject to any prohibition on dealing ahead of the dissemination of investment research. Vietnam: This document is being distributed in Vietnam by, and is attributable to, Standard Chartered Bank (Vietnam) Limited which is mainly regulated by State Bank of Vietnam (SBV). Recipients in Vietnam should contact Standard Chartered Bank (Vietnam) Limited for any queries regarding any content of this document. Zambia: This document is distributed by Standard Chartered Bank Zambia Plc, a company incorporated in Zambia and registered as a commercial bank and licensed by the Bank of Zambia under the Banking and Financial Services Act Chapter 387 of the Laws of Zambia.