
Key Takeaways:
- Dollar cost averaging (or DCA) refers to investing a fixed amount in unit trusts and/or stocks via a regular savings plan (RSP), regardless of market conditions.
- It helps mitigate market volatility and the impact of costs on one’s returns by buying fewer units in an asset when its net asset value (NAV) rises, and more units when NAV falls.
- Dollar cost averaging helps provide for long-term value creation, eliminate emotional decision making, and allows a hands-off approach to wealth creation.
Table of Contents
Objectivity and consistency are central to long-term wealth creation and portfolio stability. To achieve these goals amidst market volatility, dollar cost averaging has long been a favoured approach as it offers one a way to stay invested and focused on growth.
Here is all you need to know about what it is and how it works.
What is dollar cost averaging?
Dollar cost averaging (or DCA) is a long-term strategy that helps investors consistently build up their holdings via a regular savings plan (RSP) , such as the one offered through SC Invest. It refers to investing a fixed amount of capital at regular intervals, regardless of market conditions.
For example, Mr. Lee invests SGD 500 per month for six months through SC Invest’s Regular Savings Plan (or RSP). While the unit prices may change each month, the amount Mr. Lee invests never changes. Over time, this allows him to buy more units when prices are low and fewer when prices are high, lowering his average cost per unit.
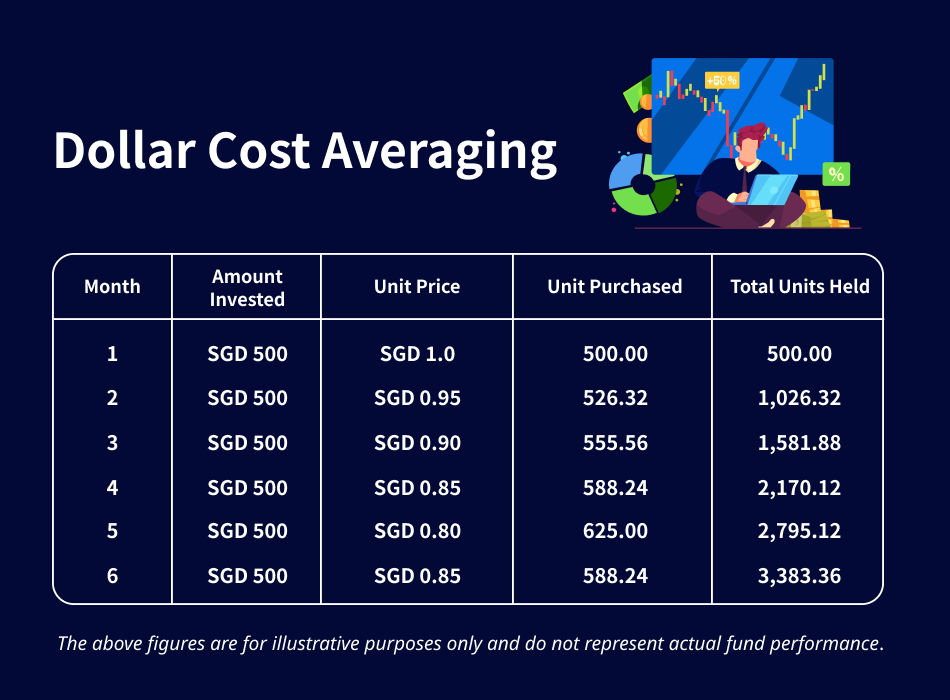
By the end of the six months, Mr. Lee has invested SGD 3,000 in total and has 3,383.36 units at an average cost of SGD 0.887 per unit, lower than the period’s average unit price of SGD 0.892. If the value of his investment grows over time, he stands to benefit from a positive return.
How does dollar cost averaging work for new investors
Dollar cost averaging brings to the table three primary benefits, each of which helps one build a more resilient investment portfolio that can weather varied market cycles.
Stabilise long-term returns
When markets rise, the same investment amount buys fewer units. When markets fall, it buys more units. This can help smooth out the average cost of investing over time and reduce the impact of market volatility on a portfolio.
Eliminate emotional decision-making
Fear of mistiming markets may lead to inaction or hasty decisions. Dollar cost averaging, however, creates a routine by investing consistently, helping investors stay disciplined and avoid reacting emotionally to short term market movements.
Build long-term wealth
As investors’ income grows, they may have more spare cash to put towards long term investments. Through an RSP, dollar cost averaging can make investing more automatic, while helping manage the effects of costs and market volatility.
Before you start to invest: Things to remember
As with all investments, there are a few essentials one must consider when it comes to adopting a dollar-cost averaging strategy.
Be consistent in investing
Market downturns may tempt investors to sell or pause their investments. However, this goes against the core principle of dollar cost averaging: to keep investing consistently and buy more units when prices are lower.
Investors should avoid changing their approach based only on short-term price movements. Investing more when markets are rising means buying units at higher prices, which can reduce the benefit of the strategy.
Choose the right asset
Dollar cost averaging does not help investors choose what to invest in. Long-term outcomes still depend on selecting assets that are aligned with their financial goals, investment horizon, and risk tolerance. Investors should also consider whether an asset serves a clear purpose, such as diversification, income generation, or capital appreciation.
Factor in the transaction costs
Regular investments mean more transactions, which may increase costs. This is especially relevant when transaction fees are fixed, for example, if a brokerage charges SGD 10 per transaction and an investor contributes SGD 500 a month, the fee will represent 2% of each monthly investment.
For this reason, some investors using dollar cost averaging may prefer lower-cost investment options, such as passively managed index funds.
You may accumulate fewer units than you think
As the prices of unit trusts rise, each RSP contribution buys fewer units. Dollar cost averaging does not guarantee that investors will accumulate a large number of units in a bullish market. However, even if unit accumulation slows, the overall value of the portfolio may still grow as unit prices increase.
Alternative strategies to dollar cost averaging
Should one be looking to take on a more hands-on approach to their investments, there are several alternative strategies to dollar cost averaging.
Value averaging
Value averaging is similar to dollar cost averaging because it involves investing regularly. The key difference is that the amount invested changes based on how the portfolio is performing. Investors add more when the portfolio is below target and less when it is above target.
For example, an investor may set a target portfolio value of SGD 50,000 in 10 years, starting from SGD 20,000 today. Each month, he checks his portfolio’s actual value against where it should be to stay on track for that goal. If the portfolio falls short, he invests more that month to catch up; if it’s ahead of schedule, he invests less.
This approach may help investors buy more when prices are lower and avoid investing too much when prices are higher. However, it requires closer monitoring and more flexibility with cash flow. Investors may need to set aside extra funds for periods when markets fall, which can make value averaging harder to maintain than dollar cost averaging.
Lump sum investing
Investors may also choose to invest a large lump sum upfront when an investor has sufficient capital ready to invest, as markets tend to rise over the long term and idle cash may miss out on potential returns.
That said, no investment strategy is perfect. Dollar cost averaging is a disciplined approach that can help investors build long-term wealth, particularly when they are starting their investment journey. The key is to stay consistent.
If you are looking to get started on your investment journey, visit Standard Chartered Bank’s SC Invest today.
FAQs on dollar cost averaging:
What’s the difference between dollar cost averaging and value averaging?
Dollar cost averaging invests the same amount at regular intervals; value averaging adjusts the amount invested based on a target portfolio value — investing more when the portfolio is below target, and less when it is above target. Value averaging may improve returns, but it requires more monitoring and cash flow flexibility.
How does dollar cost averaging (DCA) work in Singapore?
Dollar cost averaging means investing fixed amounts at regular intervals, regardless of market conditions, typically through a regular savings plan (RSP).
What are the benefits of dollar cost averaging?
Dollar cost averaging allows investors to buy more units when prices fall and fewer units when prices rise. This smooths out your average cost per unit and helps to cushion the impact of market volatility.
Do I need a large sum of money to start doing dollar cost averaging?
No, dollar cost averaging is designed for investors who don’t have a large lump sum on hand, as it allows investors to build a portfolio gradually over time. Products such as SC Invest’s RSP allow for contributions as low as SGD 100 per month.
Does dollar cost averaging guarantee profits?
No, it does not eliminate the investment risks or guarantee returns. Dollar cost averaging helps investors to manage volatility and average costs.


Your feedback is valuable to us. Did you find this article helpful?
This article is for general information only and it does not constitute an offer, recommendation or solicitation of an offer to enter into any transaction or adopt any hedging, trading or investment strategy, in relation to any securities or other financial instruments. This article has not been prepared for any particular person or class of persons and does not constitute and should not be construed as investment advice or an investment recommendation. It has been prepared without regard to the specific investment objectives, financial situation or particular needs of any person or class of persons. You should seek advice from a licensed or an exempt financial adviser on the suitability of a product for you, taking into account these factors before making a commitment to purchase any product or invest in an investment. In the event that you choose not to seek advice from a licensed or an exempt financial adviser, you should carefully consider whether the product or service described herein is suitable for you.
You are fully responsible for your investment decision, including whether the investment is suitable for you. The products/services involved are not principal-protected and you may lose all or part of your original investment amount.
Standard Chartered Bank (Singapore) Limited will not accept any responsibility or liability of any kind, with respect to the accuracy or completeness of information in this article.
Deposit Insurance Scheme
Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. For clarity, these investment products are not deposits and do not qualify as an insured deposit under the Singapore Deposit Insurance and Policy Owners’ Protection Schemes Act 2011. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured.
The information stated in this article is accurate as at the date of publication.